SOLARA ACTIVE PHARMA SCIENCES
(NSE: SOLARA)
Business:
Pure play API manufacturer supplying regulated markets globallyPortfolio covers APIs across multiple therapeutic areas, with growing focus on higher value products and CRAMSThe company is working to move from a reset phase towards sustainable and scalable growthQ1 FY27 Performance 📊
Revenue: ₹381.6 Cr | +19.6% YoYEBITDA: ₹63.5 Cr | +10% YoYPAT: ₹16.3 Cr | +55% YoYQ1 EBITDA and PAT were the highest in the last 18 quartersBase business revenue grew 24% YoY to ₹307.7 CrKey Positive 🚀
The most important part of the story is the base business.
Base business EBITDA stood at around ₹72.2 Cr, up 8% YoYGrowth APIs are showing significantly better profitabilityThe commodity Ibuprofen business continues to drag consolidated margins, but its losses improved sequentiallyNet debt reduced by approximately ₹135 Cr during Q1, bringing net debt to around ₹480 CrGrowth Triggers 🟢
Higher contribution from growth APIsExpansion of CRAMS businessNew API launches and regulated market opportunitiesContinued debt reductionBetter product mixPotential improvement in Ibuprofen profitabilityWhat I’m Watching ⚠️
Ibuprofen remains the biggest profitability challengeInput costs can impact marginsDebt is still meaningful and needs continued reductionCRAMS and growth API businesses need to scale consistentlyMargin expansion needs confirmation over multiple quartersOverall View:
Solara is showing signs of a meaningful earnings recovery.
For me, the interesting part is the improving quality of the base API business, while the company simultaneously works on CRAMS, higher value APIs and debt reduction.
The key confirmation from here is continued base business growth + margin expansion + further debt reduction.
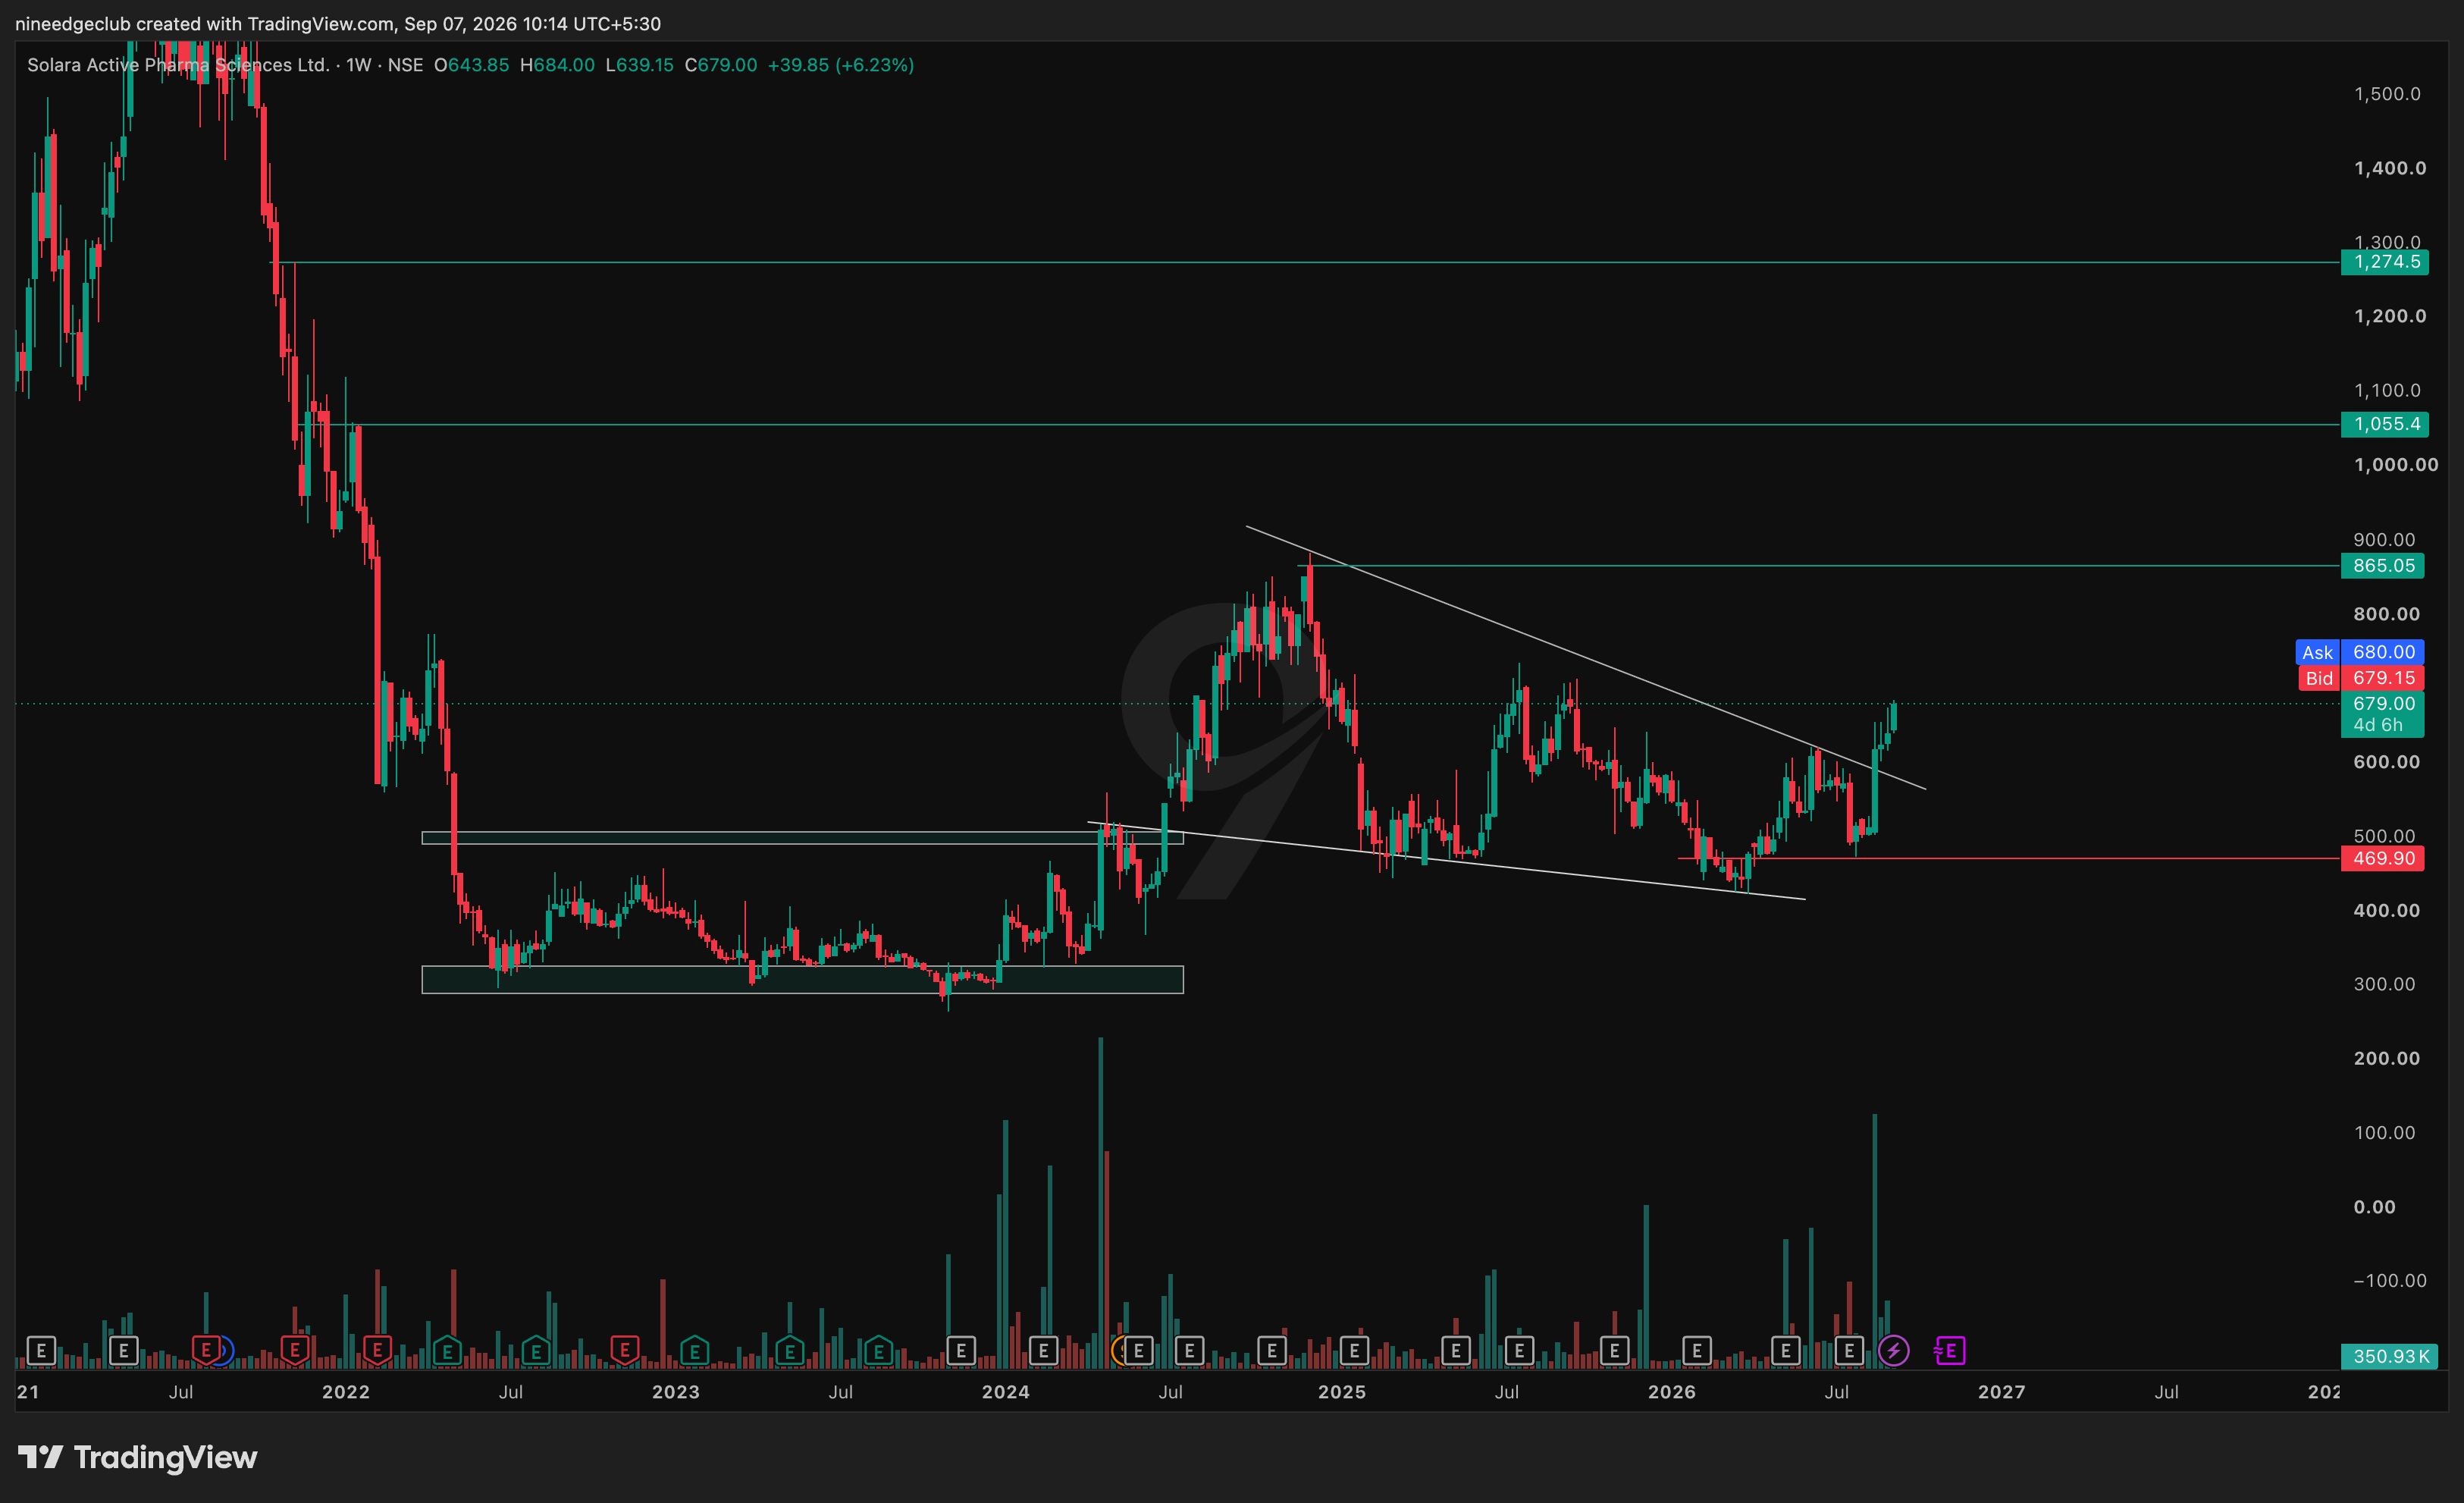
Technical Setup:
👉 Refer to the chart for my technical levels, support/resistance zones and price action view.
Disclaimer: Educational content only. Not investment advice. Please do your own research.