SHIPPING CORPORATION OF INDIA
(NSE: SCI)
Business:
SCI is India’s largest shipping company by fleet size, operating across:
Crude oil tankersProduct tankersGas carriersBulk carriersContainer and liner servicesOffshore vesselsSCI currently has 58 vessels with around 5.26 million DWT capacity, giving it exposure to India’s energy imports, global trade and maritime transportation.
Q1 FY27 Performance 🚀
Revenue from operations ₹1,846 Cr, up 40.3% YoYOperating profit ₹837 Cr, up 71.3% YoYPBT ₹628 Cr, up 71.5% YoYPAT ₹619 Cr, up 80.5% YoYThe important point is that profitability is improving much faster than revenue, indicating strong operating leverage during the current shipping cycle.
Fleet Renewal Is The Bigger Story
SCI is entering an important fleet replacement and expansion phase.
The company has been working on fleet acquisition plans across tankers, bulk carriers, gas carriers and container vessels. Newer vessels can improve operating efficiency and reduce the impact of an ageing fleet.
SCI also recently extended the time charter of its 9,034 TEU container vessel SCI Delhi for another seven years, providing longer term revenue visibility for that vessel.
Why The Story Is Interesting 🚢
📌 India’s crude and LPG import dependence
📌 Growth in seaborne trade
📌 Higher demand for tankers and gas carriers
📌 Fleet renewal and expansion
📌 Potential benefits from higher freight rates
📌 Strategic importance of an Indian controlled shipping fleet
📌 Long term growth in India’s maritime infrastructure
The Cyclical Factor ⚠️
SCI’s earnings are highly dependent on freight rates, vessel utilisation, crude movements and global shipping conditions.
A strong shipping cycle can produce exceptional profits, but the same earnings cannot simply be annualised indefinitely.
This is why I would focus more on cash generation, fleet utilisation and vessel economics than just quarterly PAT.
What I’m Watching:
New vessel additionsFleet age and replacementFreight rates across tanker and dry bulk segmentsVessel utilisationCharter coverageCapex and debtReturn on new vessel investmentsDividend and cash generationOverall View:
SCI is becoming interesting as a combination of shipping cycle + fleet renewal + India’s growing maritime requirements.
Q1 FY27 showed strong operating leverage, while fleet expansion can create another leg of growth if executed at attractive economics.
For me, the key question is whether SCI can convert the current strong shipping environment into long term fleet strength and sustainable cash generation, rather than depending only on favourable freight rates.
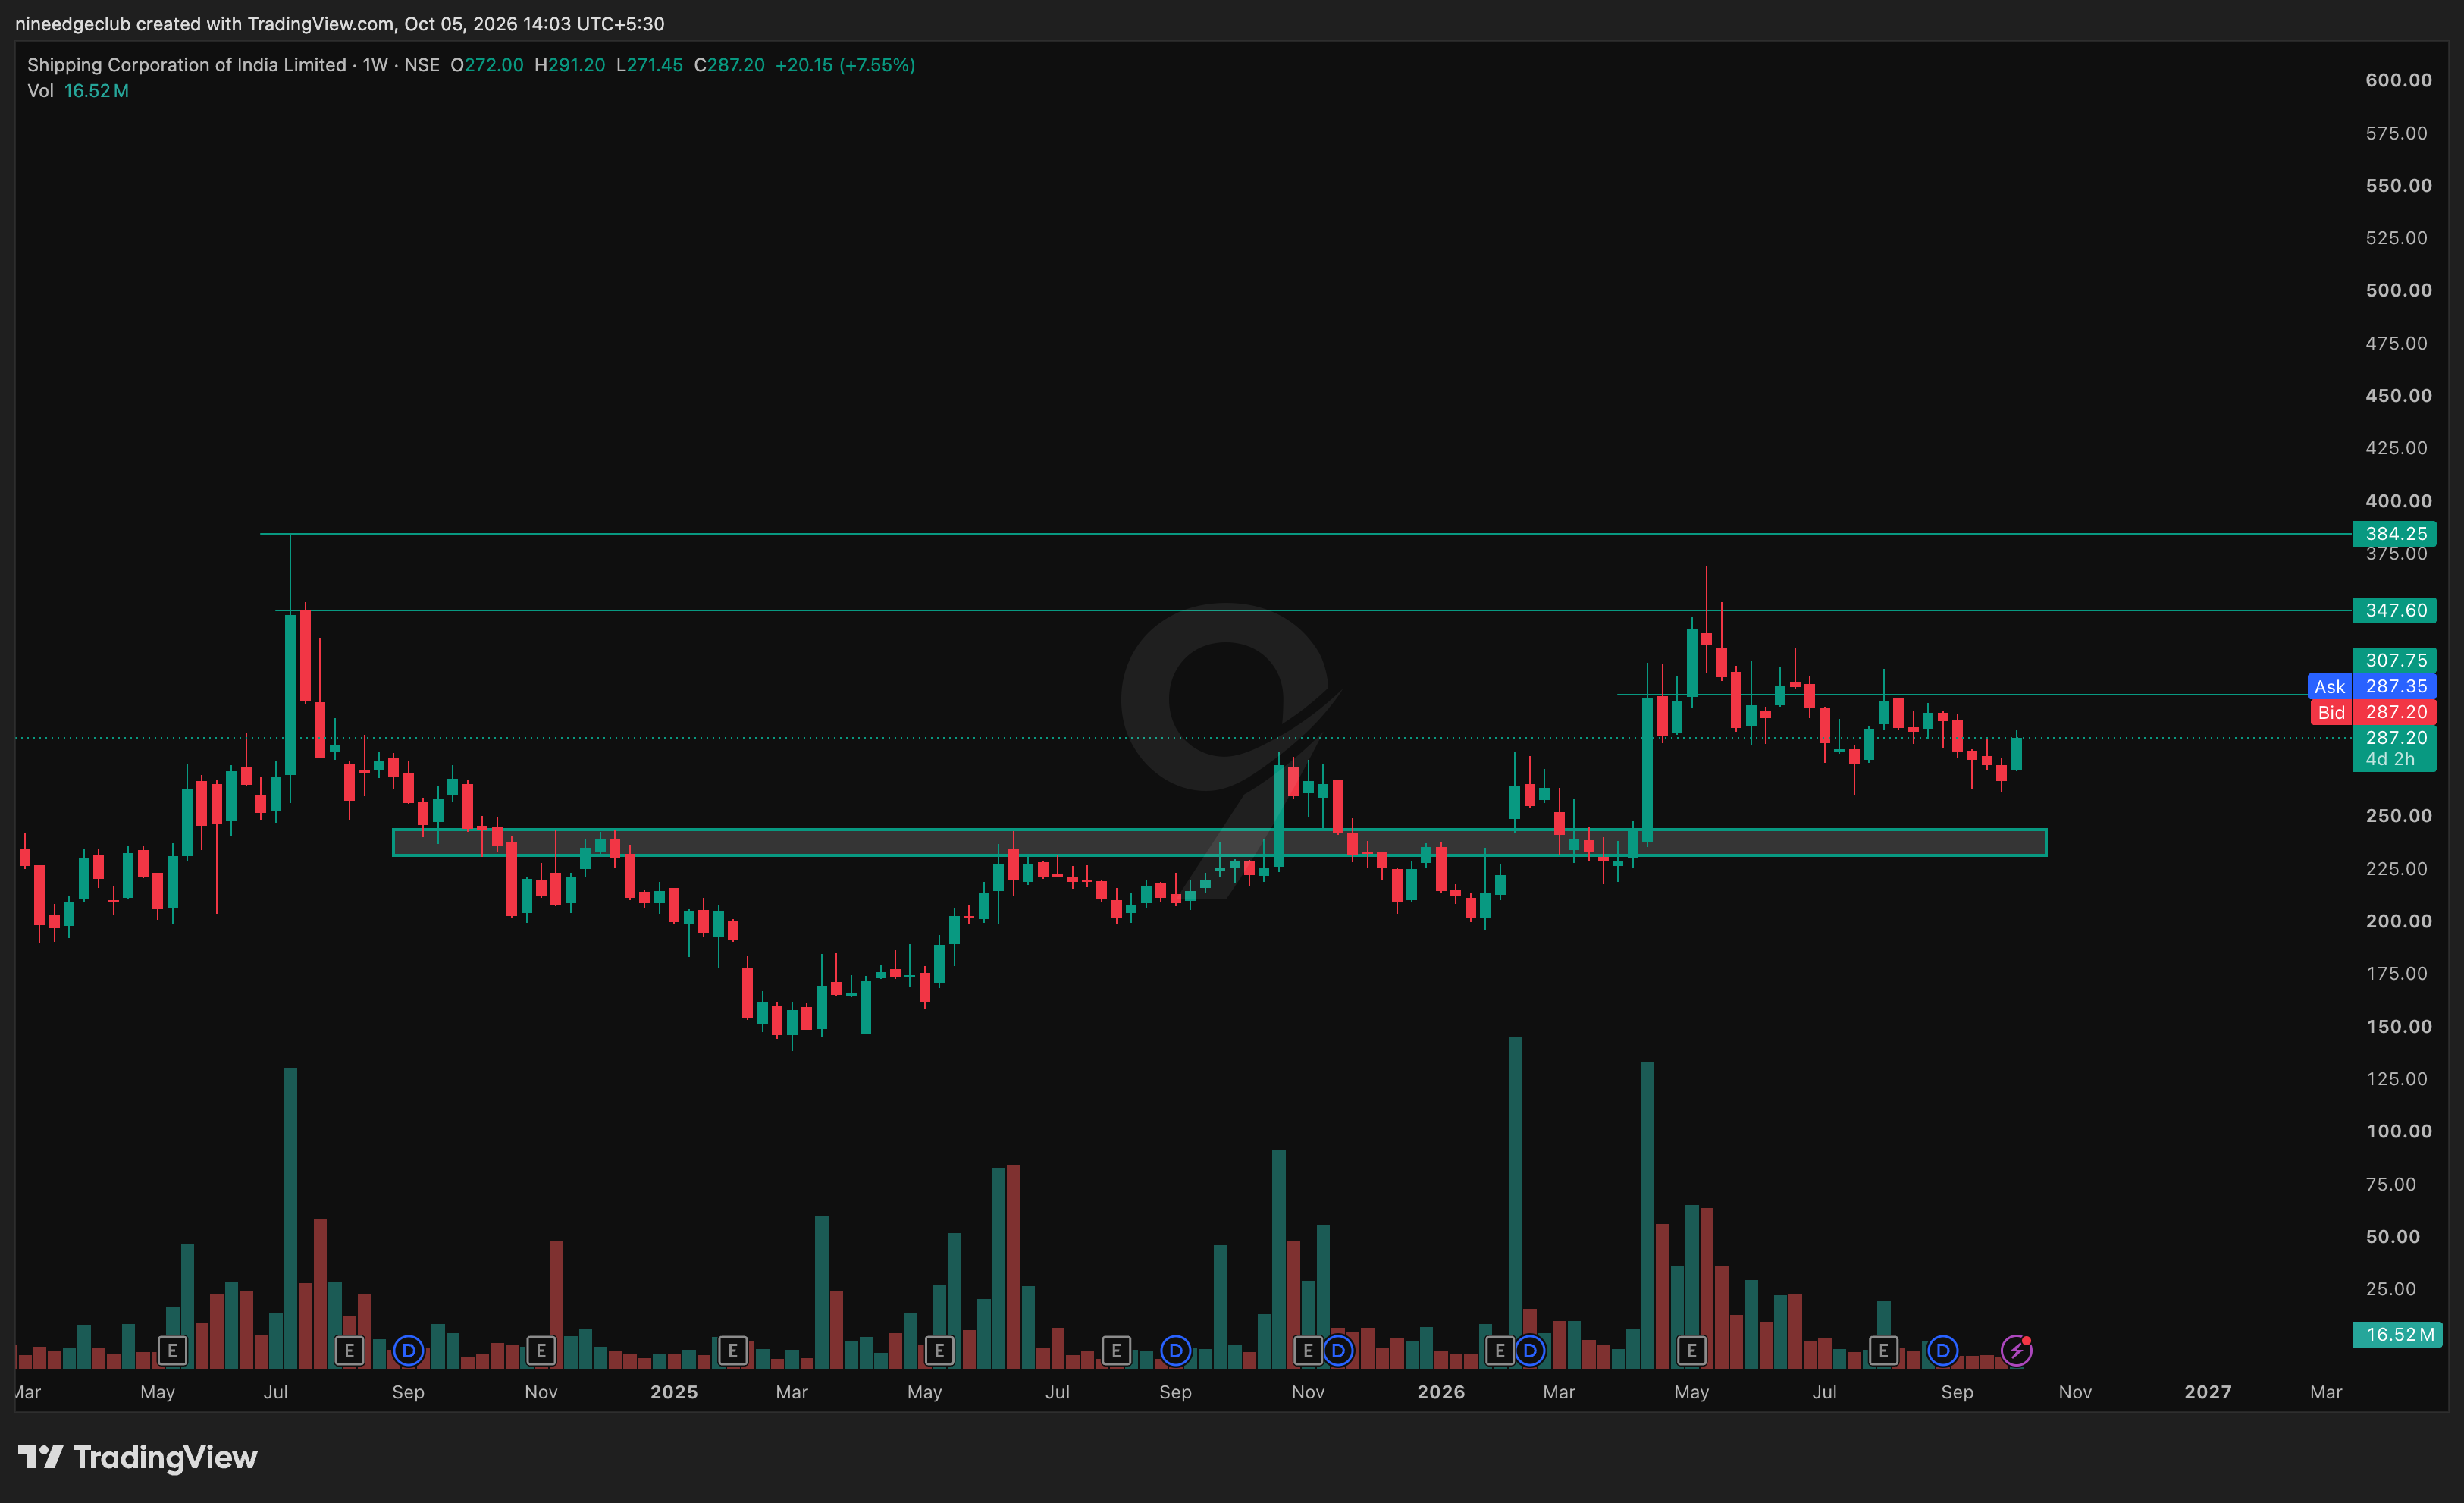
Technical Setup:
👉 Refer to the chart for my technical levels, support/resistance zones and price action view.
Disclaimer: Educational content only. Not investment advice. Please do your own research.