PIRAMAL PHARMA LIMITED
(NSE: PPLPHARMA)
Business:
Piramal Pharma operates through three major businesses:
Contract Development & Manufacturing Organization, CDMOComplex Hospital Generics, CHGPiramal Consumer Healthcare, PCHThe company has a global presence with manufacturing and development capabilities across India, the US and other markets.
Q1 FY27 Performance 📊
Revenue ₹2,270 Cr, up 17% YoYCDMO revenue ₹1,187 Cr, up 19%CHG revenue ₹743 Cr, up 17%Consumer Healthcare revenue ₹347 Cr, up 15%EBITDA ₹285 Cr, up 72%EBITDA margin improved to 12.5% from 8.5%PAT remained negative at ₹69 Cr, but loss narrowed from ₹102 Cr YoYThe important part is the 72% EBITDA growth against 17% revenue growth, showing meaningful operating leverage.
CDMO 🚀
CDMO remains the largest business and contributed more than half of consolidated revenue.
Growth is being supported by healthy order inflows, higher capacity utilisation, improved execution and better commercial coverage.
The company is also expanding its capabilities in ADCs, sterile injectables and other complex technologies.
Biopharma funding has improved RFP activity, although customer decision timelines remain extended.
Complex Hospital Generics:
Piramal continues to have a strong position in specialised hospital products.
US Sevoflurane value share around 48%Maintained leadership in US intrathecal BaclofenKenalog integration progressing, with supplies expected from Q2 FY27Continued focus on differentiated generics and 505(b)(2) productsThe Kenalog integration and new product launches can become additional growth drivers.
Consumer Healthcare:
This segment is also showing strong momentum.
Power Brands grew 23% YoYPower Brands contributed 53% of Consumer Healthcare salesE commerce grew 40% YoYE commerce contributed 28% of salesPremiumisation, wider distribution and digital commerce are supporting the segment.
Major Growth Triggers:
📌 CDMO order conversion
📌 Higher capacity utilisation
📌 ADC and complex injectable capabilities
📌 Kenalog integration
📌 Growth in differentiated hospital generics
📌 Consumer Healthcare brand expansion
📌 Improving operating leverage
What I’m Watching:
The biggest monitorable is conversion of EBITDA growth into sustainable PAT and cash flow.
Despite strong operating improvement, the company reported a ₹69 Cr consolidated loss in Q1.
Interest expense was ₹88 Cr and depreciation was ₹224 Cr, so improving operating profitability needs to continue for the bottom line to turn consistently positive.
Overall View:
PPLPHARMA is moving into an important phase where CDMO growth + complex generics + consumer healthcare are working together.
The Q1 numbers show clear operating leverage, but the next confirmation will be sustained EBITDA growth followed by a consistent return to profitability.
For me, the key things to track are CDMO order conversion, margin expansion, Kenalog contribution, capacity utilisation and the path to positive PAT and cash flow.
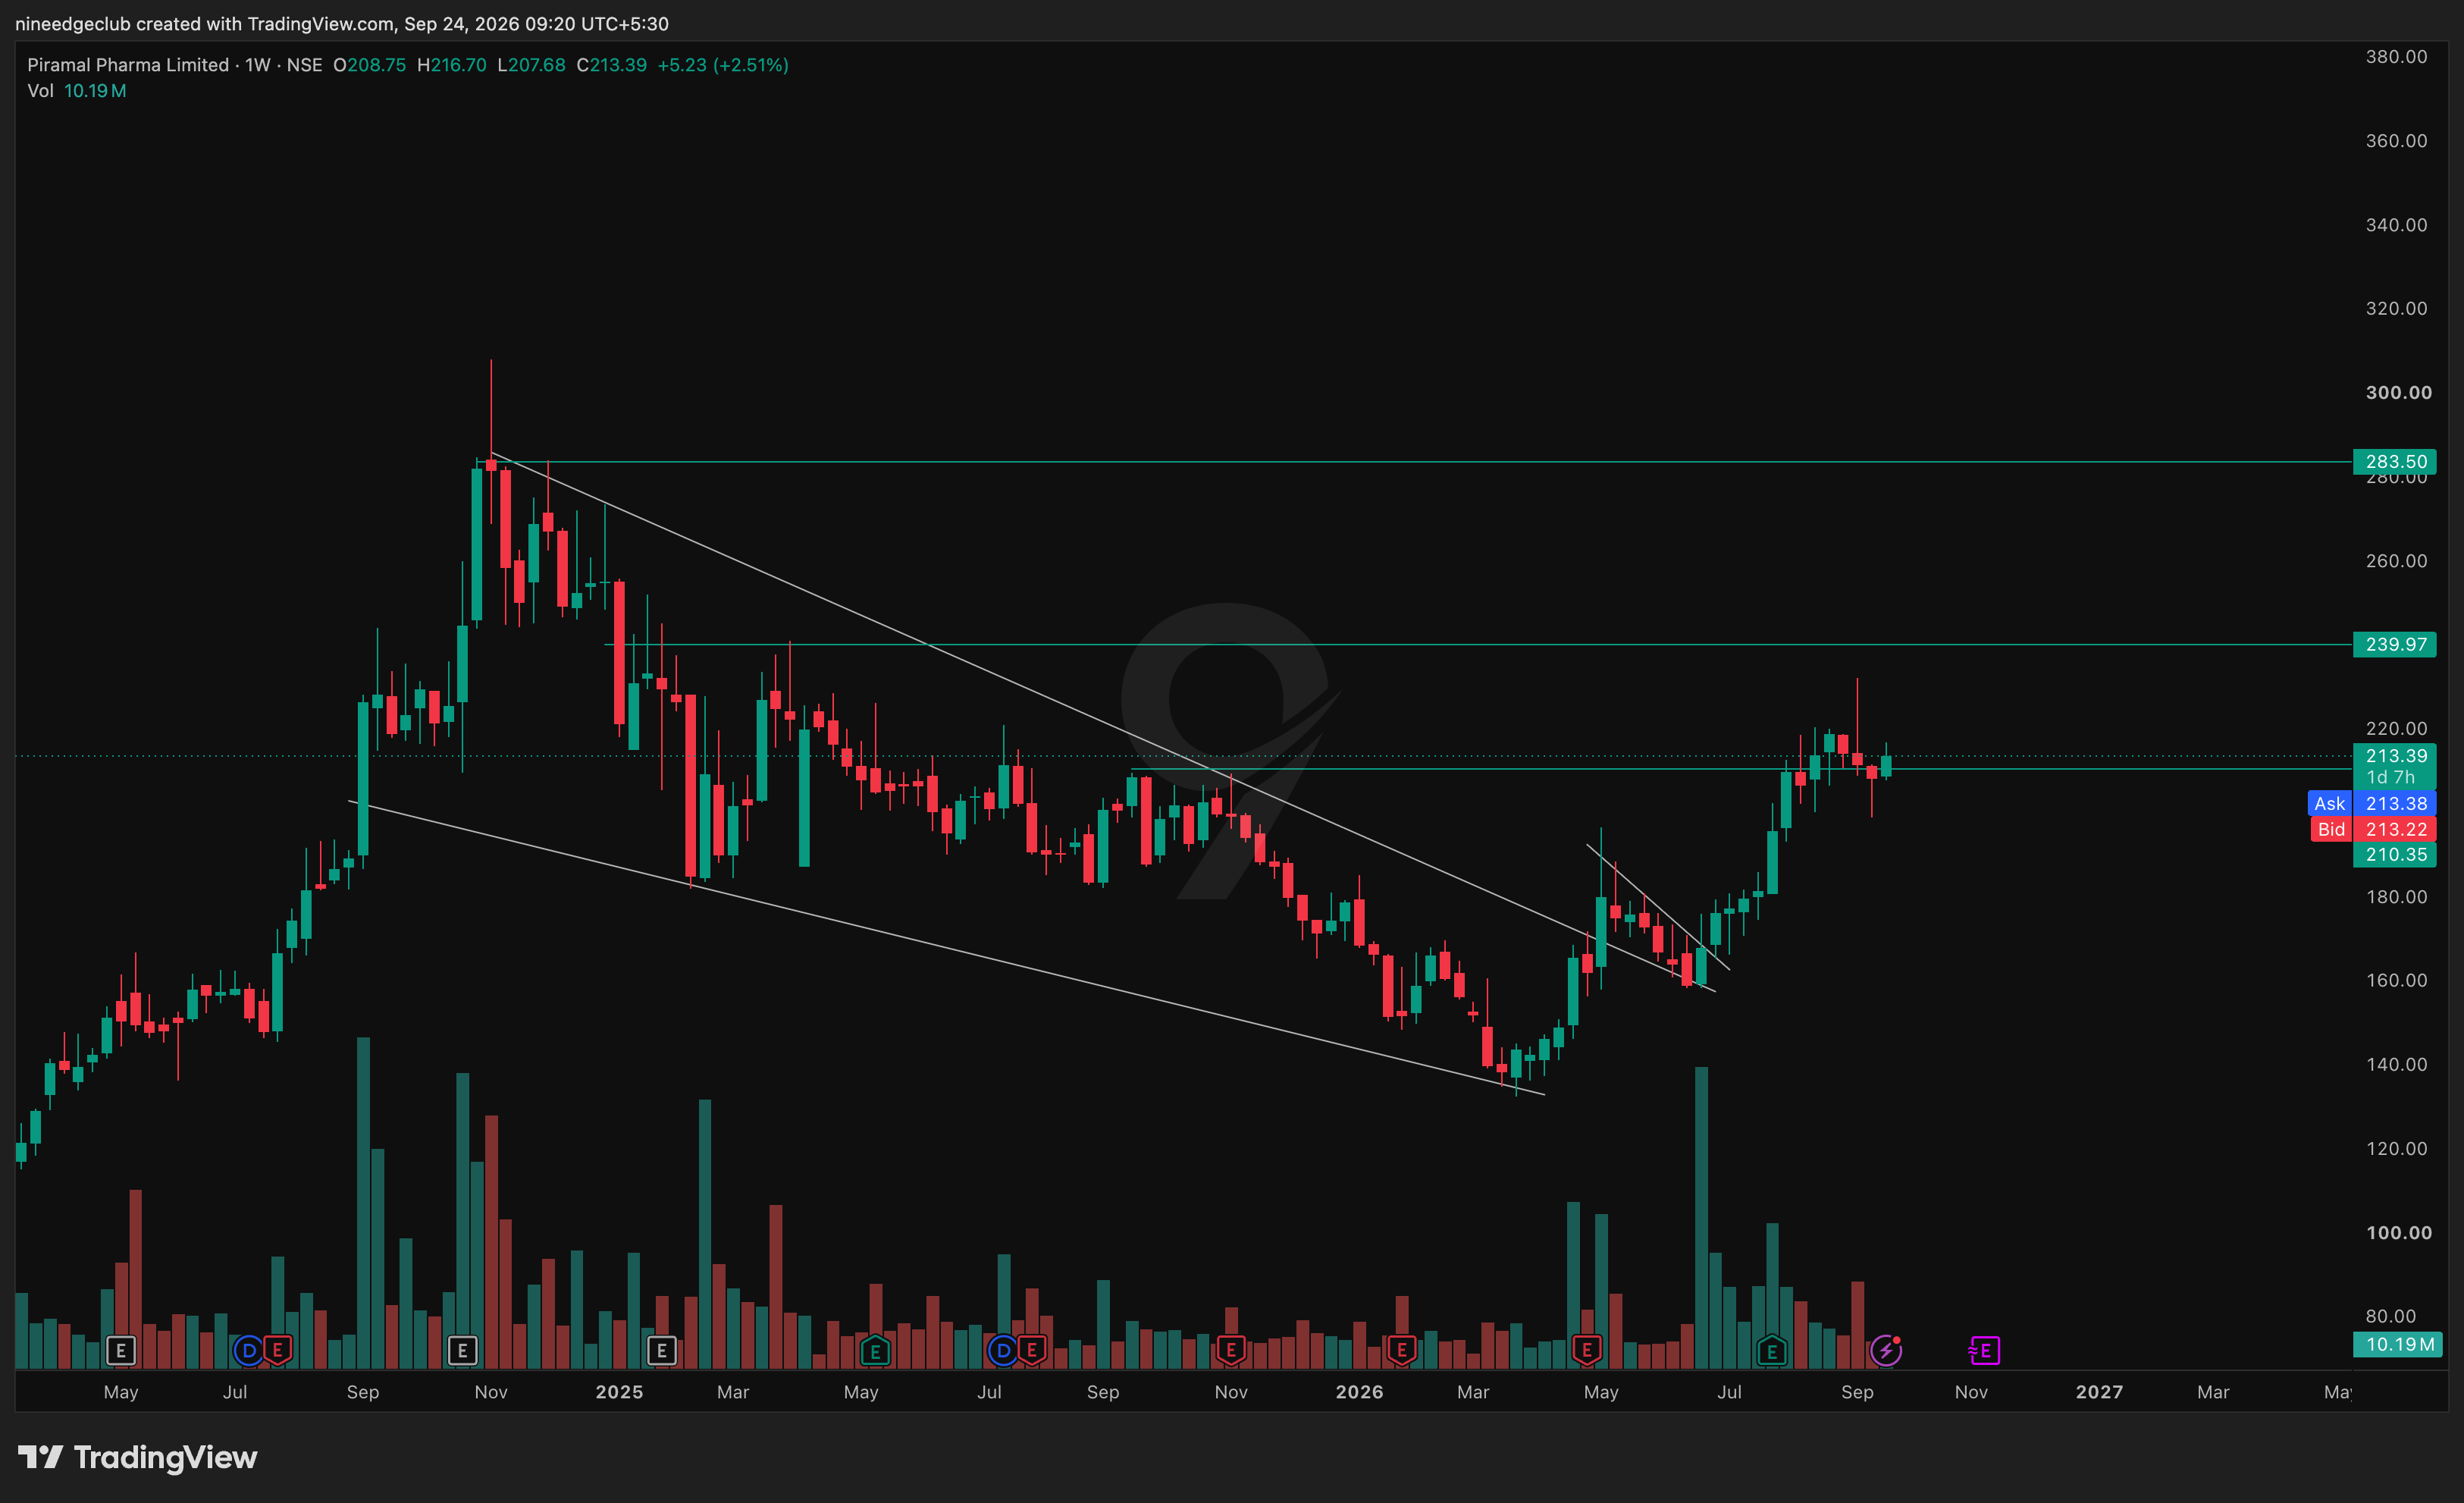
Technical Setup:
👉 Refer to the chart for my technical levels, support/resistance zones and price action view.
Disclaimer: Educational content only. Not investment advice. Please do your own research.