PIX TRANSMISSIONS LIMITED
(NSE: PIXTRANS)
Business:
PIX Transmissions manufactures power transmission belts and related products used across industrial, agricultural and automotive applications.
Its portfolio includes:
Industrial beltsAgricultural beltsAutomotive beltsLawn mower beltsPulleys and bushesCouplings and accessoriesThe company has a strong export presence, with products sold across 100+ countries. Exports contribute more than 50% of turnover, giving PIX meaningful global exposure.
Q1 FY27 Performance 📊
Consolidated revenue ₹149.25 Cr, up 22.8% YoYOperating profit ₹45.66 Cr, up 65.6% YoYPBT ₹66.64 Cr, up 89.3% YoYPAT ₹52.75 Cr, up 89.3% YoYOperating margin improved substantiallyOn a QoQ basis, revenue declined 12.6%, but profitability improved sharply, showing strong margin performance.
Balance Sheet Strength 💰
One of the interesting aspects of PIX is its financial position.
The latest credit assessment highlighted:
📌 Healthy profitability margins
📌 Comfortable capital structure
📌 Strong liquidity
📌 Negative net debt position
📌 Diversified geographical revenue
📌 Established position in rubber transmission belts
This gives the company financial flexibility to continue investing in capacity and technology.
FY26 Picture:
FY26 was relatively stable rather than a high growth year.
Consolidated total income ₹599.8 CrConsolidated PAT ₹106.9 CrPAT was slightly lower than FY25Management recommended ₹9 per share dividendThe important change is that Q1 FY27 has shown a significant acceleration in profitability.
Growth Triggers 🚀
📌 Industrial automation and capex
📌 Agricultural equipment demand
📌 Automotive applications
📌 Export market expansion
📌 Higher value added transmission products
📌 Capacity expansion
📌 Increasing penetration in global markets
The company’s global distribution network and established customer base provide a platform for further international growth.
What I’m Watching:
The biggest monitorable is whether the Q1 margin expansion is sustainable.
Revenue grew 22.8%, while operating profit grew more than 65%, which is a significant operating leverage effect.
I would track:
Export growthEBITDA marginCapacity utilisationRaw material costsWorking capital cycleCurrency movementDomestic industrial demandThe company also remains exposed to global trade conditions and foreign exchange movements because of its substantial export business.
Overall View:
PIXTRANS is an interesting industrial manufacturing + export + auto ancillary story.
The combination of a strong balance sheet, established global presence and Q1 FY27 margin expansion makes the earnings trajectory worth tracking.
The key confirmation going forward will be sustained revenue growth with high margins, rather than one strong quarter.
Technical Setup:
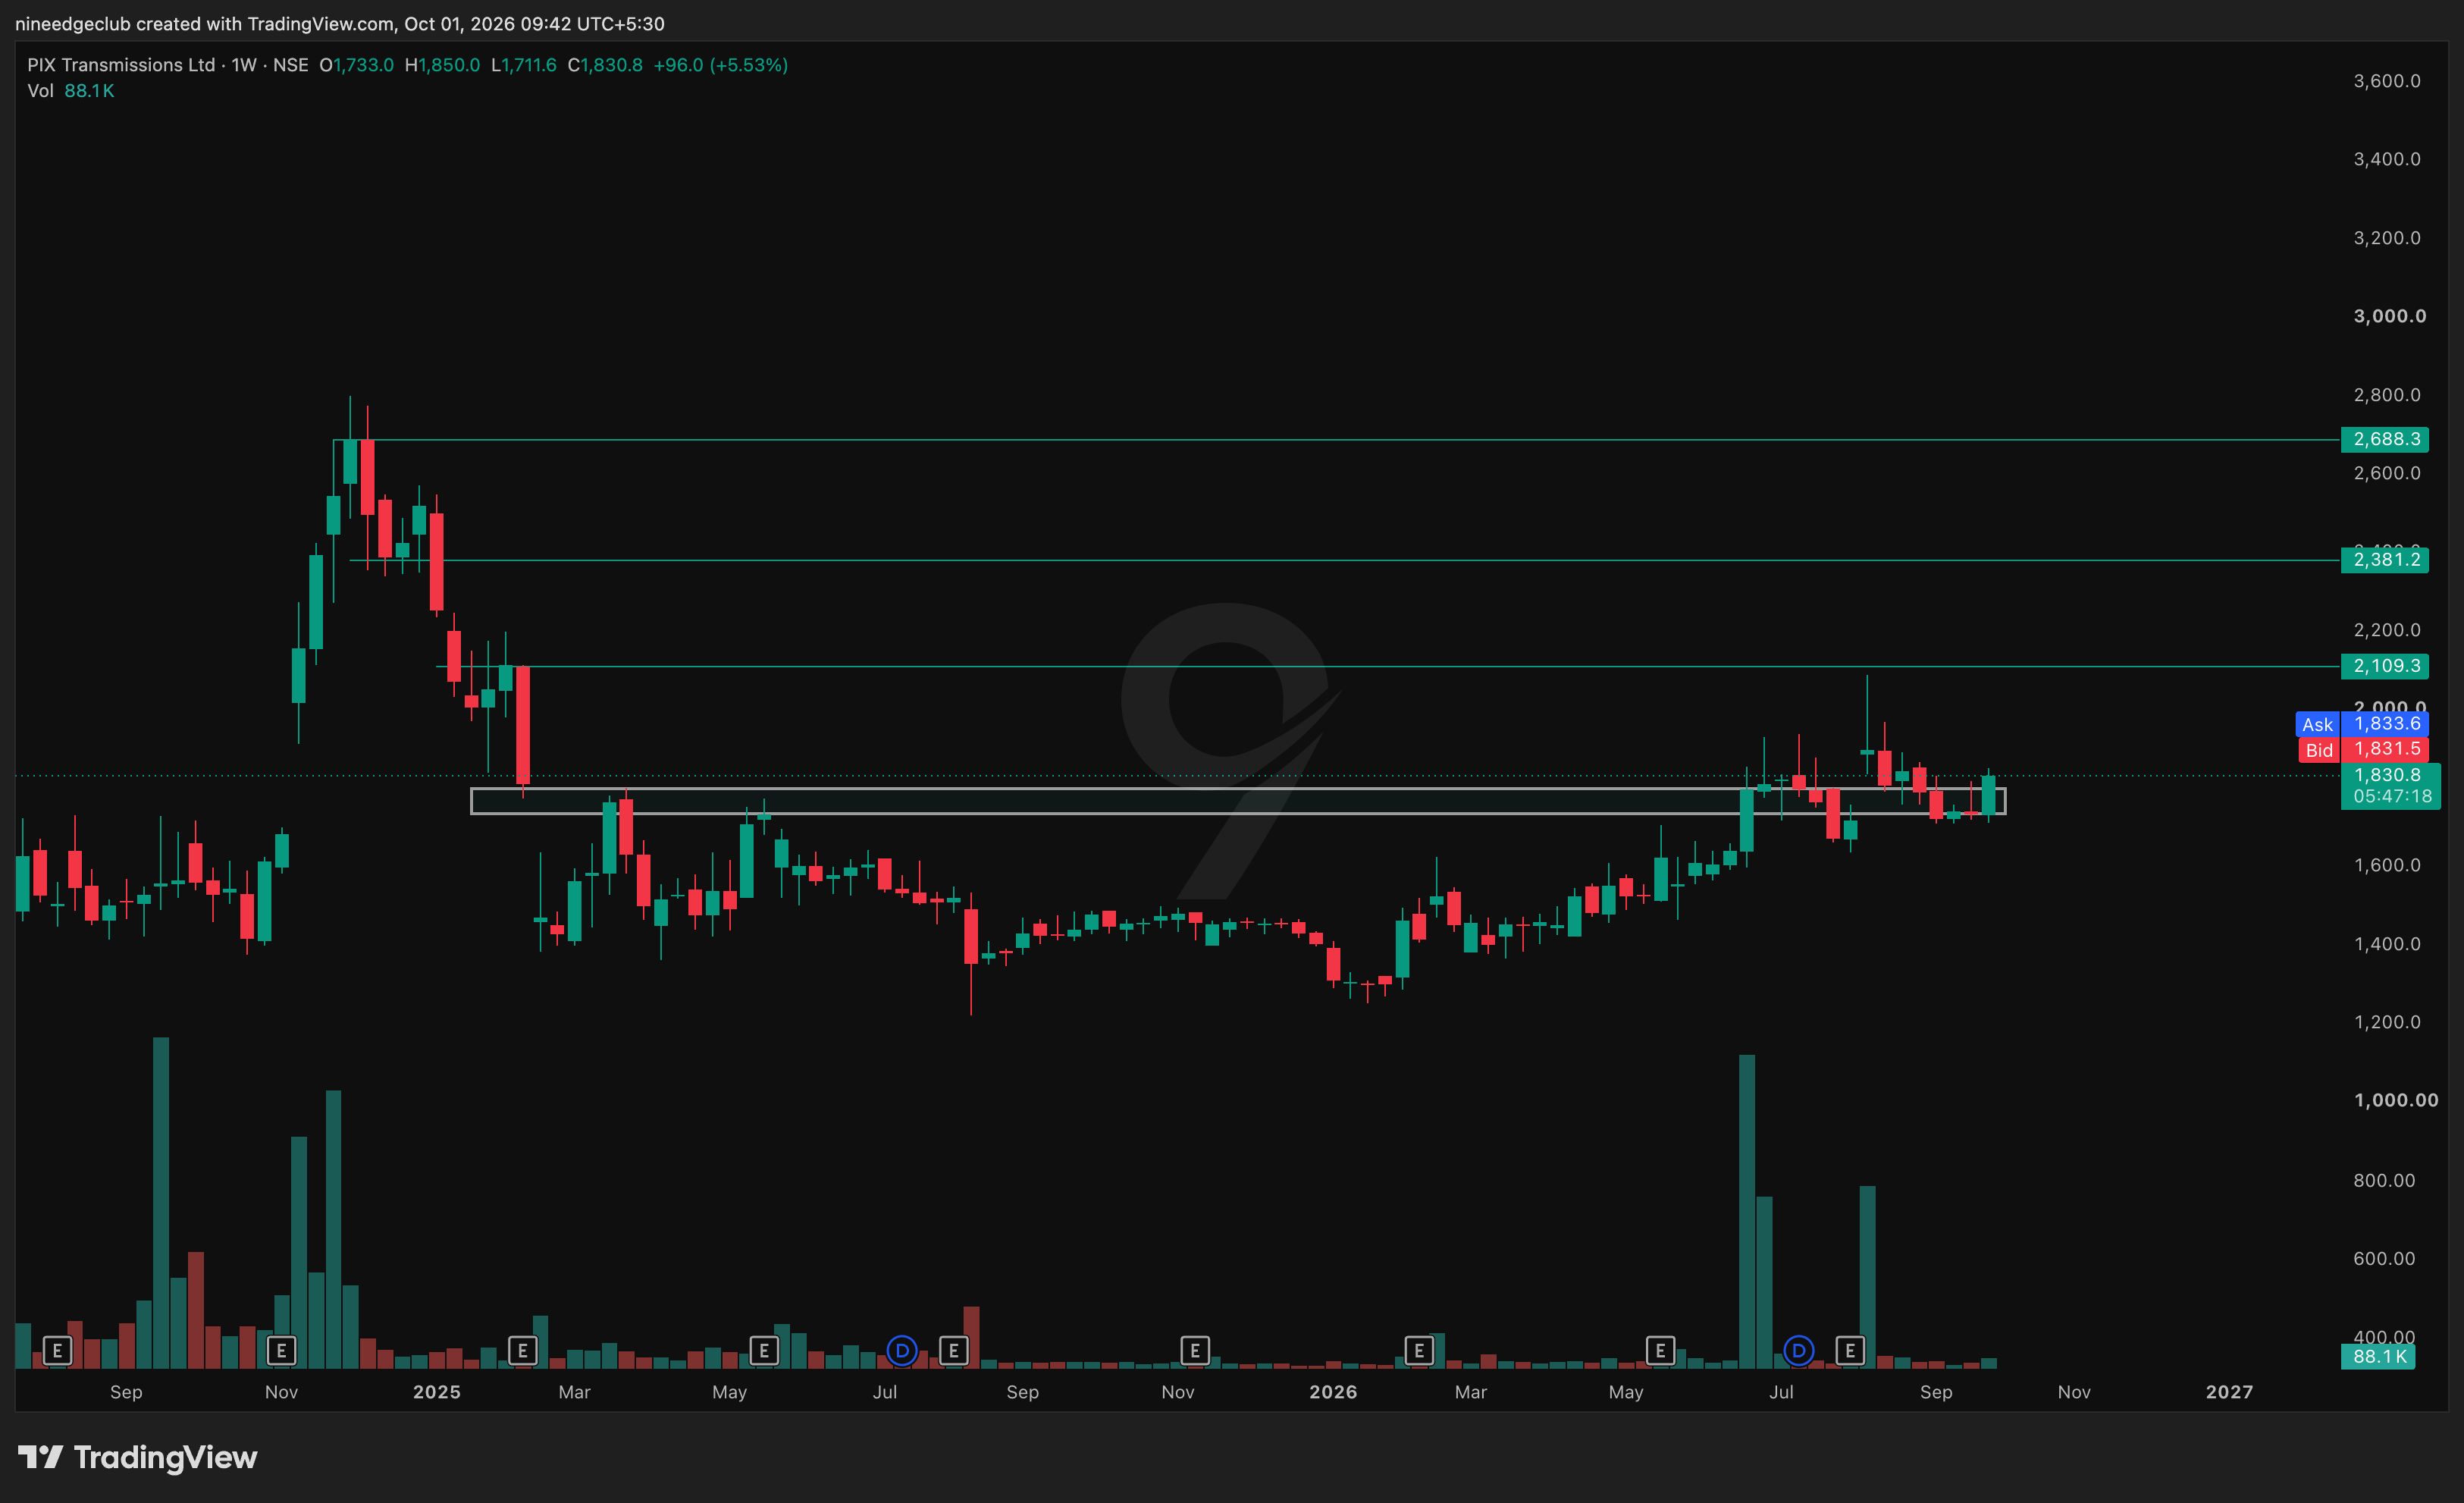
👉 Refer to the chart for my technical levels, support/resistance zones and price action view.
Disclaimer: Educational content only. Not investment advice. Please do your own research.