NEW INDIA ASSURANCE
(NSE: NIACL)
Business:
India’s largest general insurance company by net worth, with a diversified presence across motor, health, property, marine and other insurance segments.Strong balance sheet and a large investment portfolio provide a significant financial base.The key thesis is improvement in underwriting profitability + better claims experience + premium growth.Q1 FY27 Performance ⚠️
GWP: ₹13,720 Cr | +2.9% YoYNet Premium Written: ₹11,298 Cr | +3.6% YoYPAT: ₹-257 Cr vs ₹391 Cr profit YoYSolvency Ratio: 1.80x remains healthyInvestment assets: approximately ₹99,980 CrCombined Ratio: 121.44%Incurred Claim Ratio: 103.38%Why I’m Watching It 🟢
Strong balance sheet and substantial investment assetsSolvency remains comfortably above 1xFY26 was a strong year with ₹1,384 Cr net profit, versus ₹988 Cr in FY25.Large established franchise with significant scaleAny improvement in underwriting margins can have a meaningful impact on profitability.Key Concern ⚠️
Q1 FY27 was weak because of elevated claims, particularly in Motor Third Party.Combined ratio above 100% indicates underwriting losses.Premium growth was relatively muted at 2.9%.The key monitorable is whether the high claim ratio normalises over the next few quarters.Potential Triggers 🚀
Improvement in Motor TP pricingNormalisation of claims/loss ratiosBetter product mix towards retail & MSMEStronger premium growthImprovement in combined ratioContinued investment income supporting overall profitability.Overall View:
NIACL is an interesting balance sheet + turnaround play, rather than a straightforward high-growth story.
The biggest trigger from here would be underwriting improvement. If the combined ratio starts moving towards 100% and premium growth improves, earnings can recover meaningfully.
For me, the next few quarters are important for confirmation claims ratio, combined ratio and premium growth are the three numbers I’ll be watching most closely.
Personal Experience:
I also have my health insurance with NIACL and personally, I haven’t faced any issues with my medical claims so far.Of course, individual claim experiences can vary but this has been a positive experience for me as a policyholder.Technical Setup:
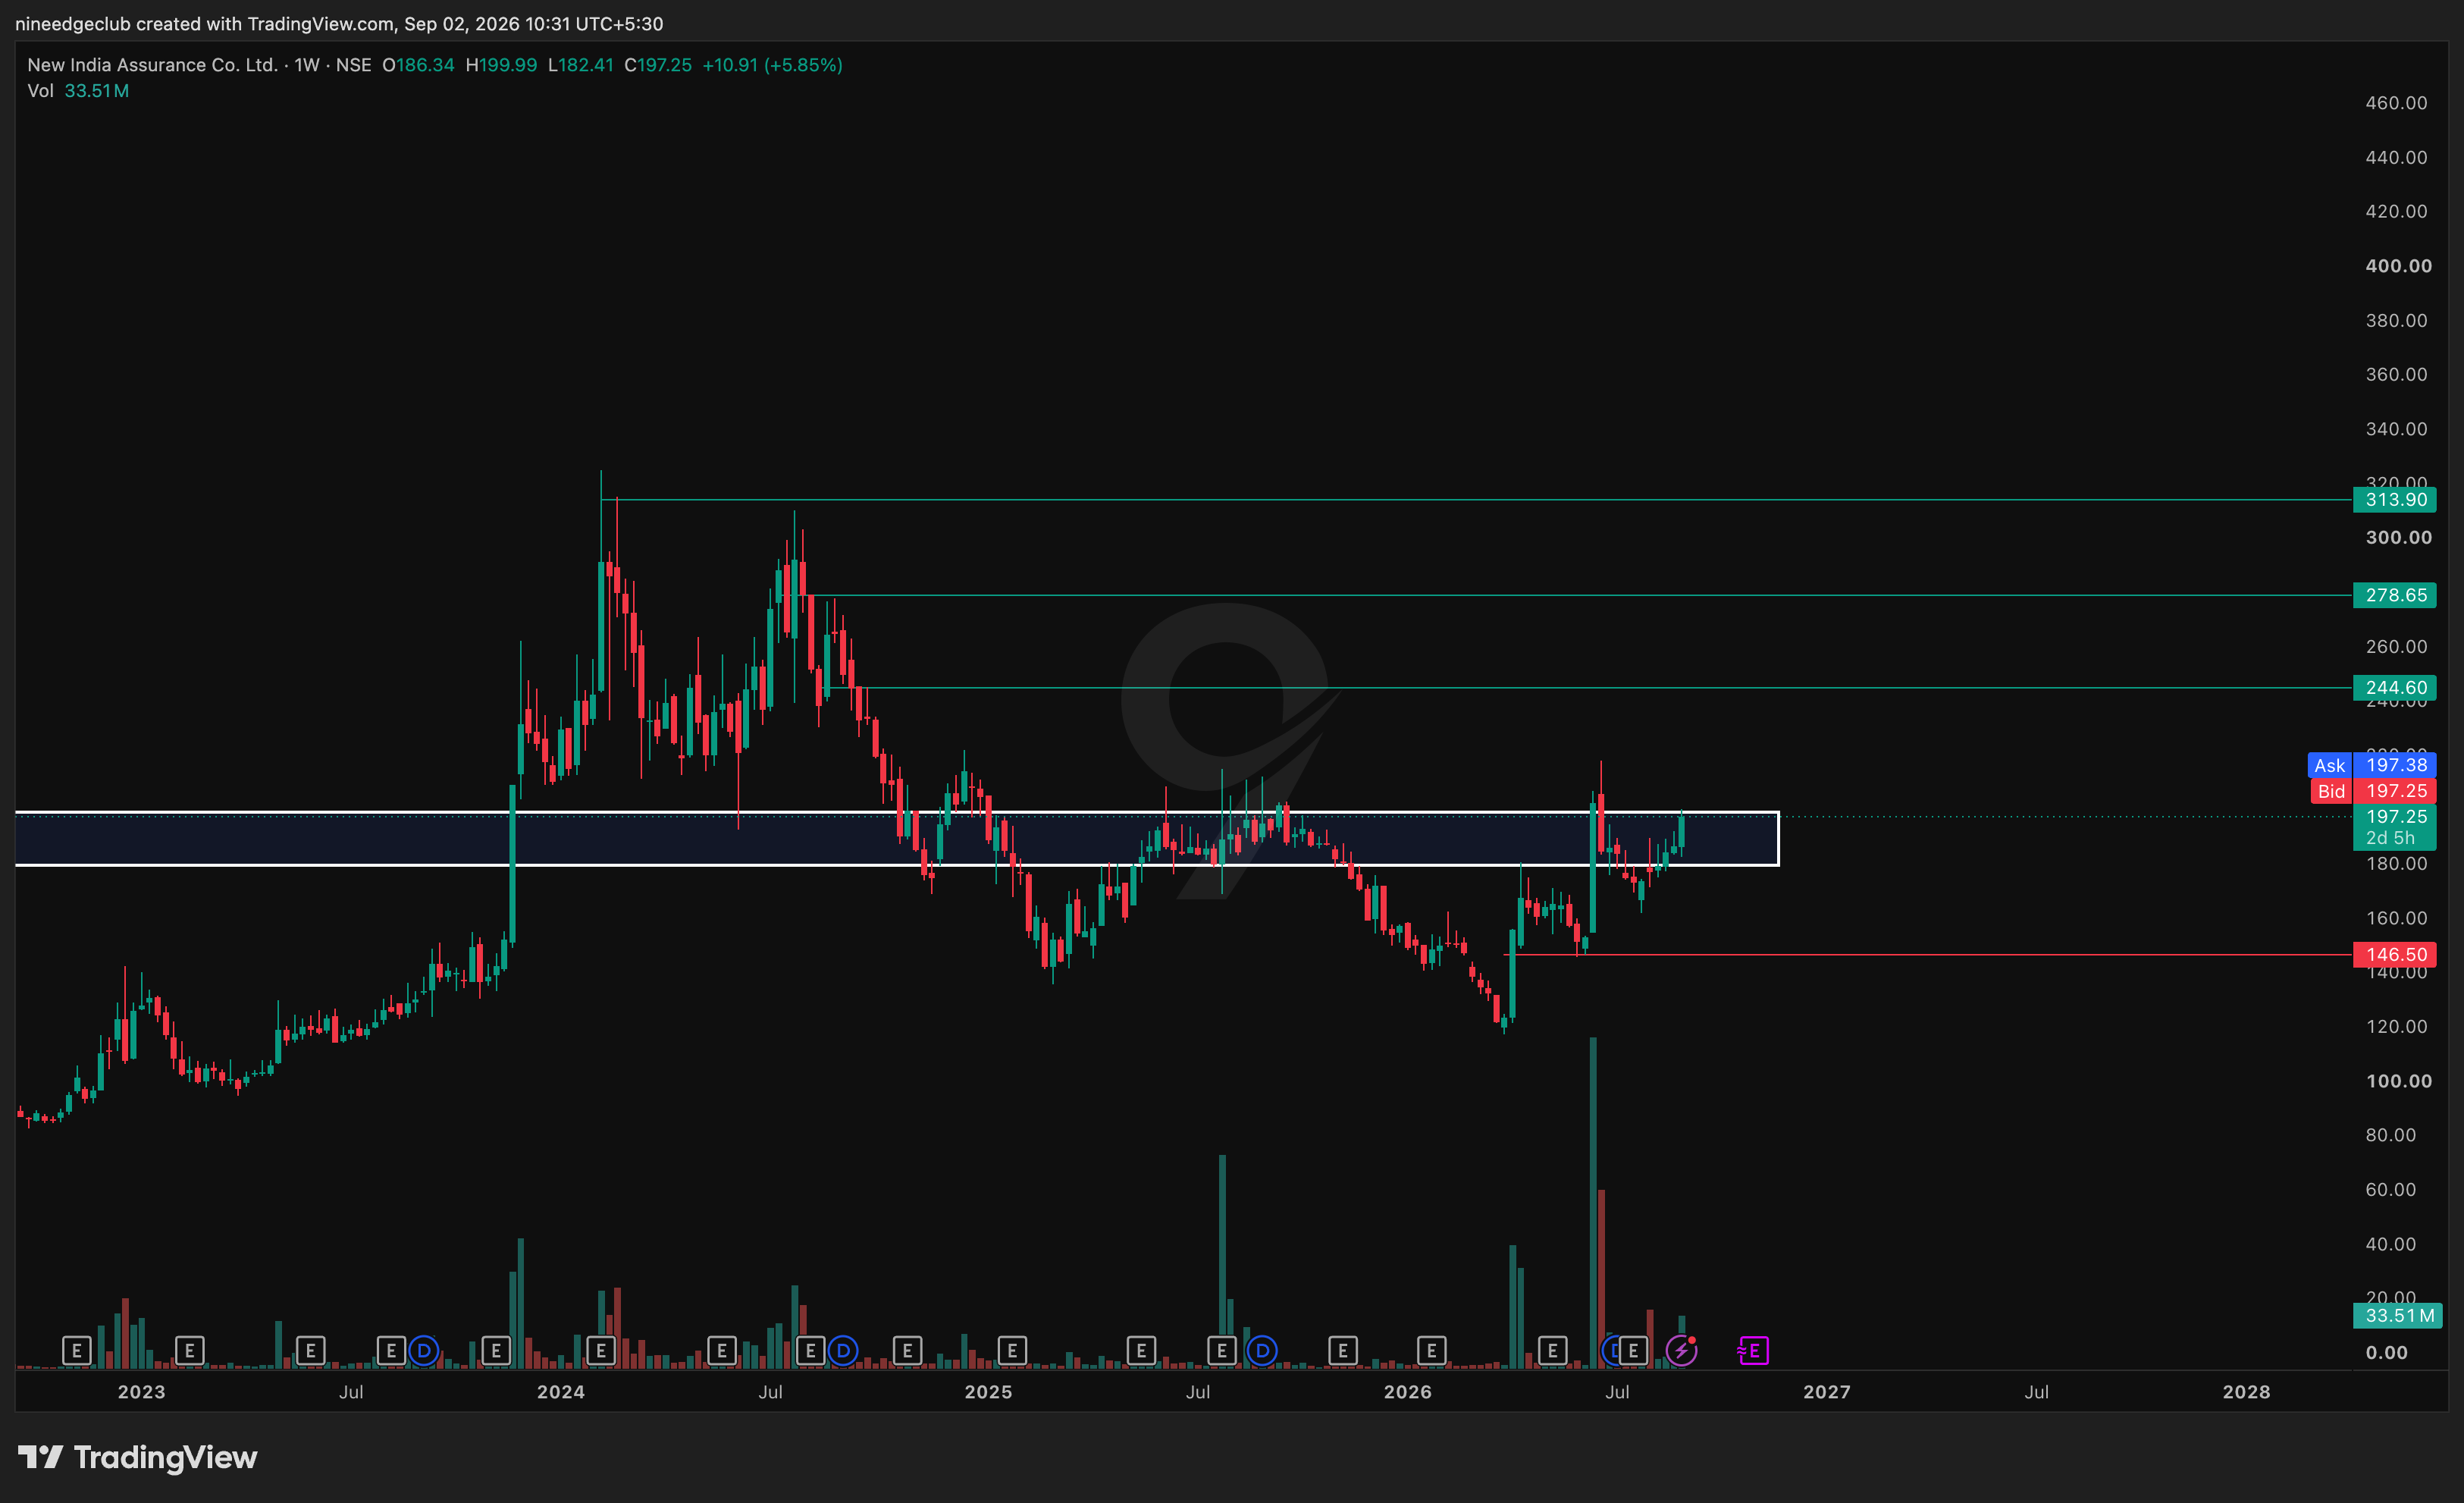
👉 Refer to the chart for my technical levels, support/resistance zones and price action view.
Disclaimer: Educational content only. Not investment advice. Please do your own research.