MUKAND LIMITED
(NSE: MUKANDLTD)
Business:
Mukand is a Bajaj Group company focused primarily on specialty and alloy steel, along with industrial machinery and engineering.
Its steel products include wire rods, bars, bright bars and wires used across automotive, engineering, oil & gas, infrastructure and defence applications.
The company has manufacturing facilities at Kalwe and Hospet and exports to more than 25 countries.
Q1 FY27 Performance 📊
Revenue from operations ₹1,362 Cr, up 20.7% YoYTotal income ₹1,467 Cr, up 25.7% YoYPBT ₹60.2 Cr, up 59.9% YoYPAT ₹57.4 Cr, up 97.6% YoYSpecialty Steel revenue ₹1,321 CrSpecialty Steel segment result ₹89 CrThe important point is that earnings improved significantly YoY, although operating profit itself was only ₹7.2 Cr. This means the reported PAT growth needs to be looked at alongside other income and non operating items.
FY26 Performance:
FY26 was a major improvement for Mukand.
Total income ₹5,336 CrEBITDA ₹720 CrPAT ₹635 CrEPS ₹43.92However, FY26 also benefited from non recurring factors, so I would not extrapolate the FY26 PAT directly into future earnings.
BIG TRIGGER: LAND VALUE UNLOCKING 🚀
Mukand has signed a term sheet to sell around 8.8 acres of land at Kalwa, Thane, for approximately ₹506 Cr.
The company has already received ₹59.29 Cr as the second tranche of consideration.
The stated objective is to unlock value from non core land without affecting its manufacturing operations.
This is important because the land monetisation can provide additional liquidity and potentially support balance sheet improvement.
Growth Triggers:
📌 Specialty steel demand from automotive and engineering
📌 Higher utilisation of downstream facilities
📌 Value added steel products
📌 Special steel grades for aerospace and defence
📌 Infrastructure and industrial capex
📌 Further monetisation of non core assets
Management has also been focusing on downstream value added products and improving capacity utilisation to generate operating leverage.
What I’m Watching:
The biggest monitorable is quality of earnings.
Q1 revenue growth was strong, but operating profit remained weak. Therefore, sustainable improvement in core steel margins will be more important than headline PAT growth.
I would track:
Steel realisations and spreadsCapacity utilisationEBITDA from the core steel businessDebt and interest costsProgress of the Kalwa land transactionHow the monetisation proceeds are utilisedOverall View:
Mukand is an interesting combination of specialty steel + engineering + asset monetisation.
The core business provides exposure to India’s manufacturing and infrastructure cycle, while the land transaction creates an additional value unlocking angle.
The key question going forward is whether core steel profitability improves sustainably, while the company uses asset monetisation to strengthen its financial position.
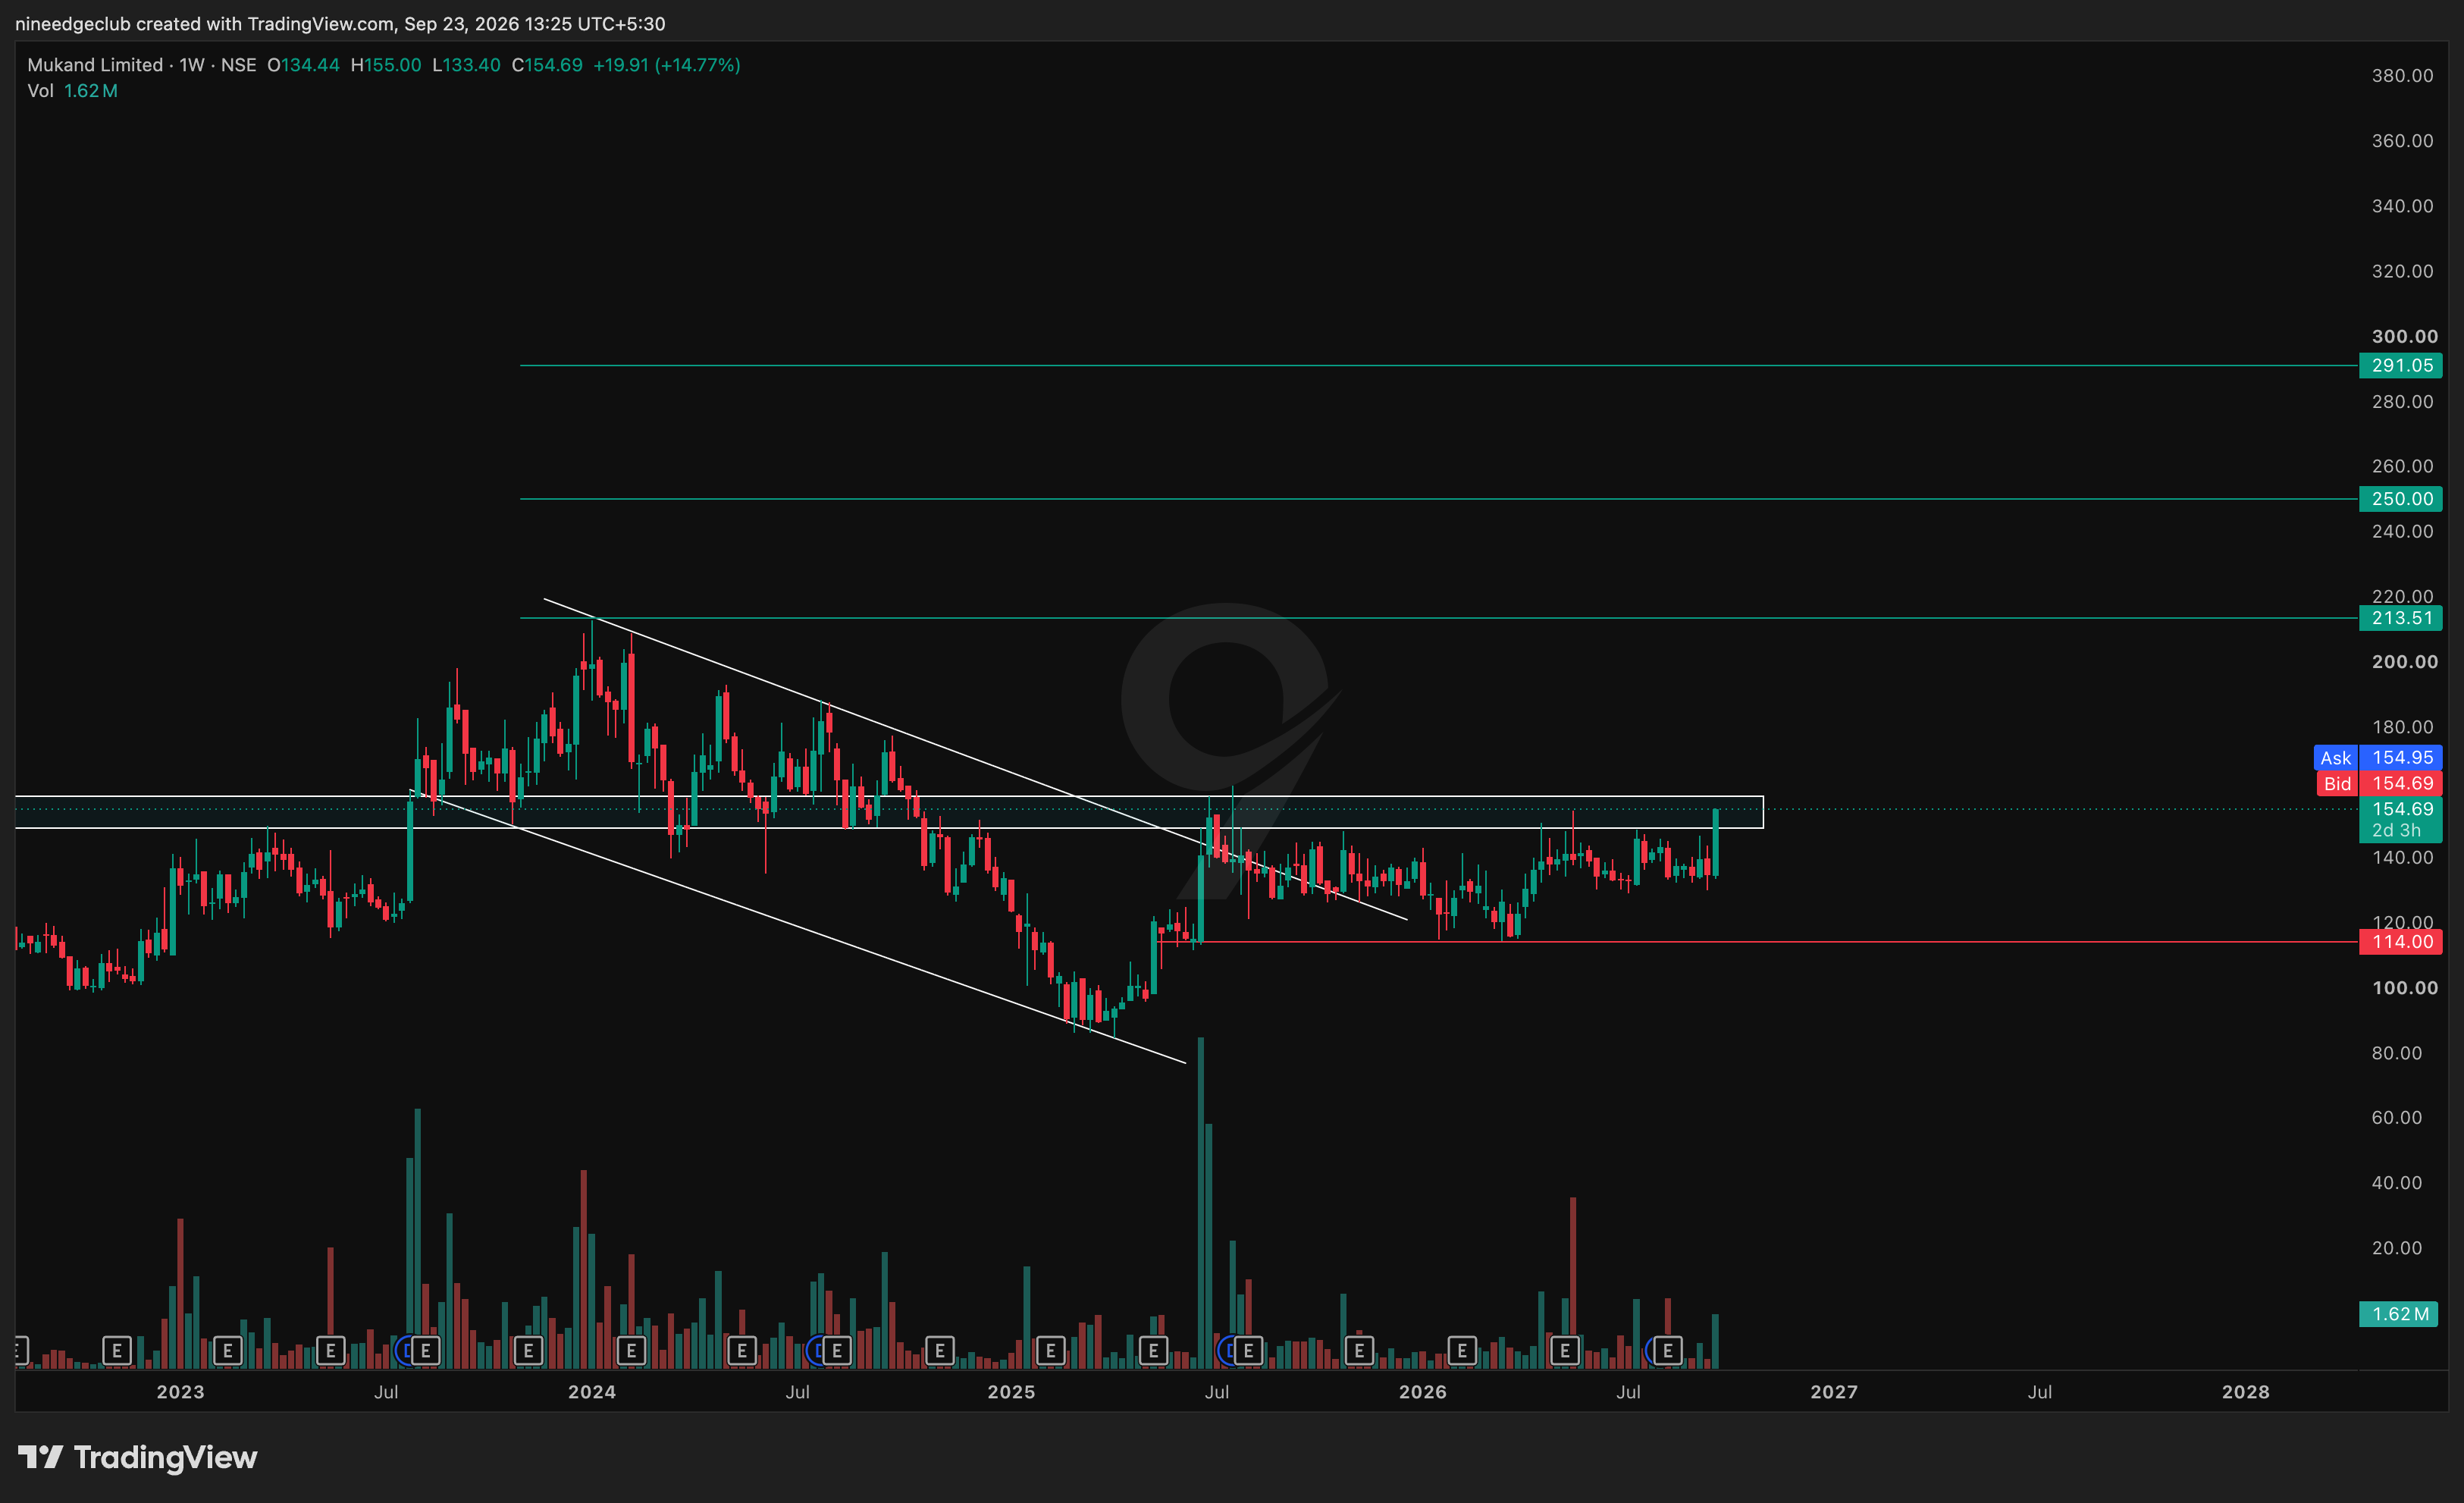
Technical Setup:
👉 Refer to the chart for my technical levels, support/resistance zones and price action view.
Disclaimer: Educational content only. Not investment advice. Please do your own research.