MANGALORE REFINERY & PETROCHEMICALS LIMITED
(NSE: MRPL)
Business:
MRPL is an ONGC group refinery with 15 MTPA refining capacity at Mangalore.
The company produces petrol, diesel, aviation turbine fuel, LPG, petrochemical feedstocks and other petroleum products, with both domestic and export markets.
Q1 FY27 Performance 📊
Revenue from operations ₹41,609 Cr, up 98% YoYPBT ₹1,246 Cr versus ₹402 Cr loss YoYPAT ₹946 Cr versus ₹271 Cr loss YoYOperating profit ₹1,318 Cr, up sharply YoYThroughput around 4.43 MMT versus 3.52 MMT YoYThe turnaround is significant, but there is an important adjustment: Q1 included around ₹472 Cr of exceptional income related to retrospective petroleum product price revisions.
FY26 Recovery:
FY26 was a major recovery year for MRPL.
Standalone PBT ₹4,022 Cr versus ₹113 Cr in FY25Standalone PAT ₹1,931 Cr versus ₹51 CrFY26 GRM around $9.22 per barrel₹4 per share dividend declaredThis shows how strongly MRPL’s profitability can respond when refining margins improve.
BIG POINT TO WATCH ⚠️
MRPL is not a conventional steady earnings compounder.
Its profitability is highly dependent on:
📌 Gross refining margins
📌 Crude oil prices
📌 Product cracks
📌 Refinery utilisation
📌 Inventory gains or losses
📌 Global refining capacity and demand
We saw this clearly in FY25, when weaker GRMs resulted in PAT of only around ₹51 Cr, compared with ₹1,931 Cr in FY26.
Growth / Earnings Triggers 🚀
Higher refinery utilisationStrong diesel and gasoline cracksBetter GRMsHigher export opportunitiesPetrochemical integrationStrong domestic fuel demandEfficient crude sourcing and product mixMRPL also achieved record domestic HSD and MS dispatches during FY26, while product exports reached a record 723.2 TMT in September 2025.
What I’m Watching:
The biggest question is whether refining margins remain supportive.
Q1 PAT looks very strong, but the exceptional income means I would not simply annualise ₹946 Cr and assume the same earnings every quarter.
I would track:
GRM per barrelThroughput and utilisationOperating profit excluding exceptional itemsInventory gains or lossesCrude differentialsDebt and interest costsPetrochemical contributionOverall View:
MRPL is an interesting refining cycle + petrochemicals + ONGC backed energy infrastructure story.
The FY26 recovery and Q1 FY27 turnaround show significant earnings leverage when refining conditions are favourable.
But the key distinction is that MRPL’s earnings are cyclical. Sustained GRMs and operating performance matter much more than one exceptionally strong quarter.
Technical Setup:
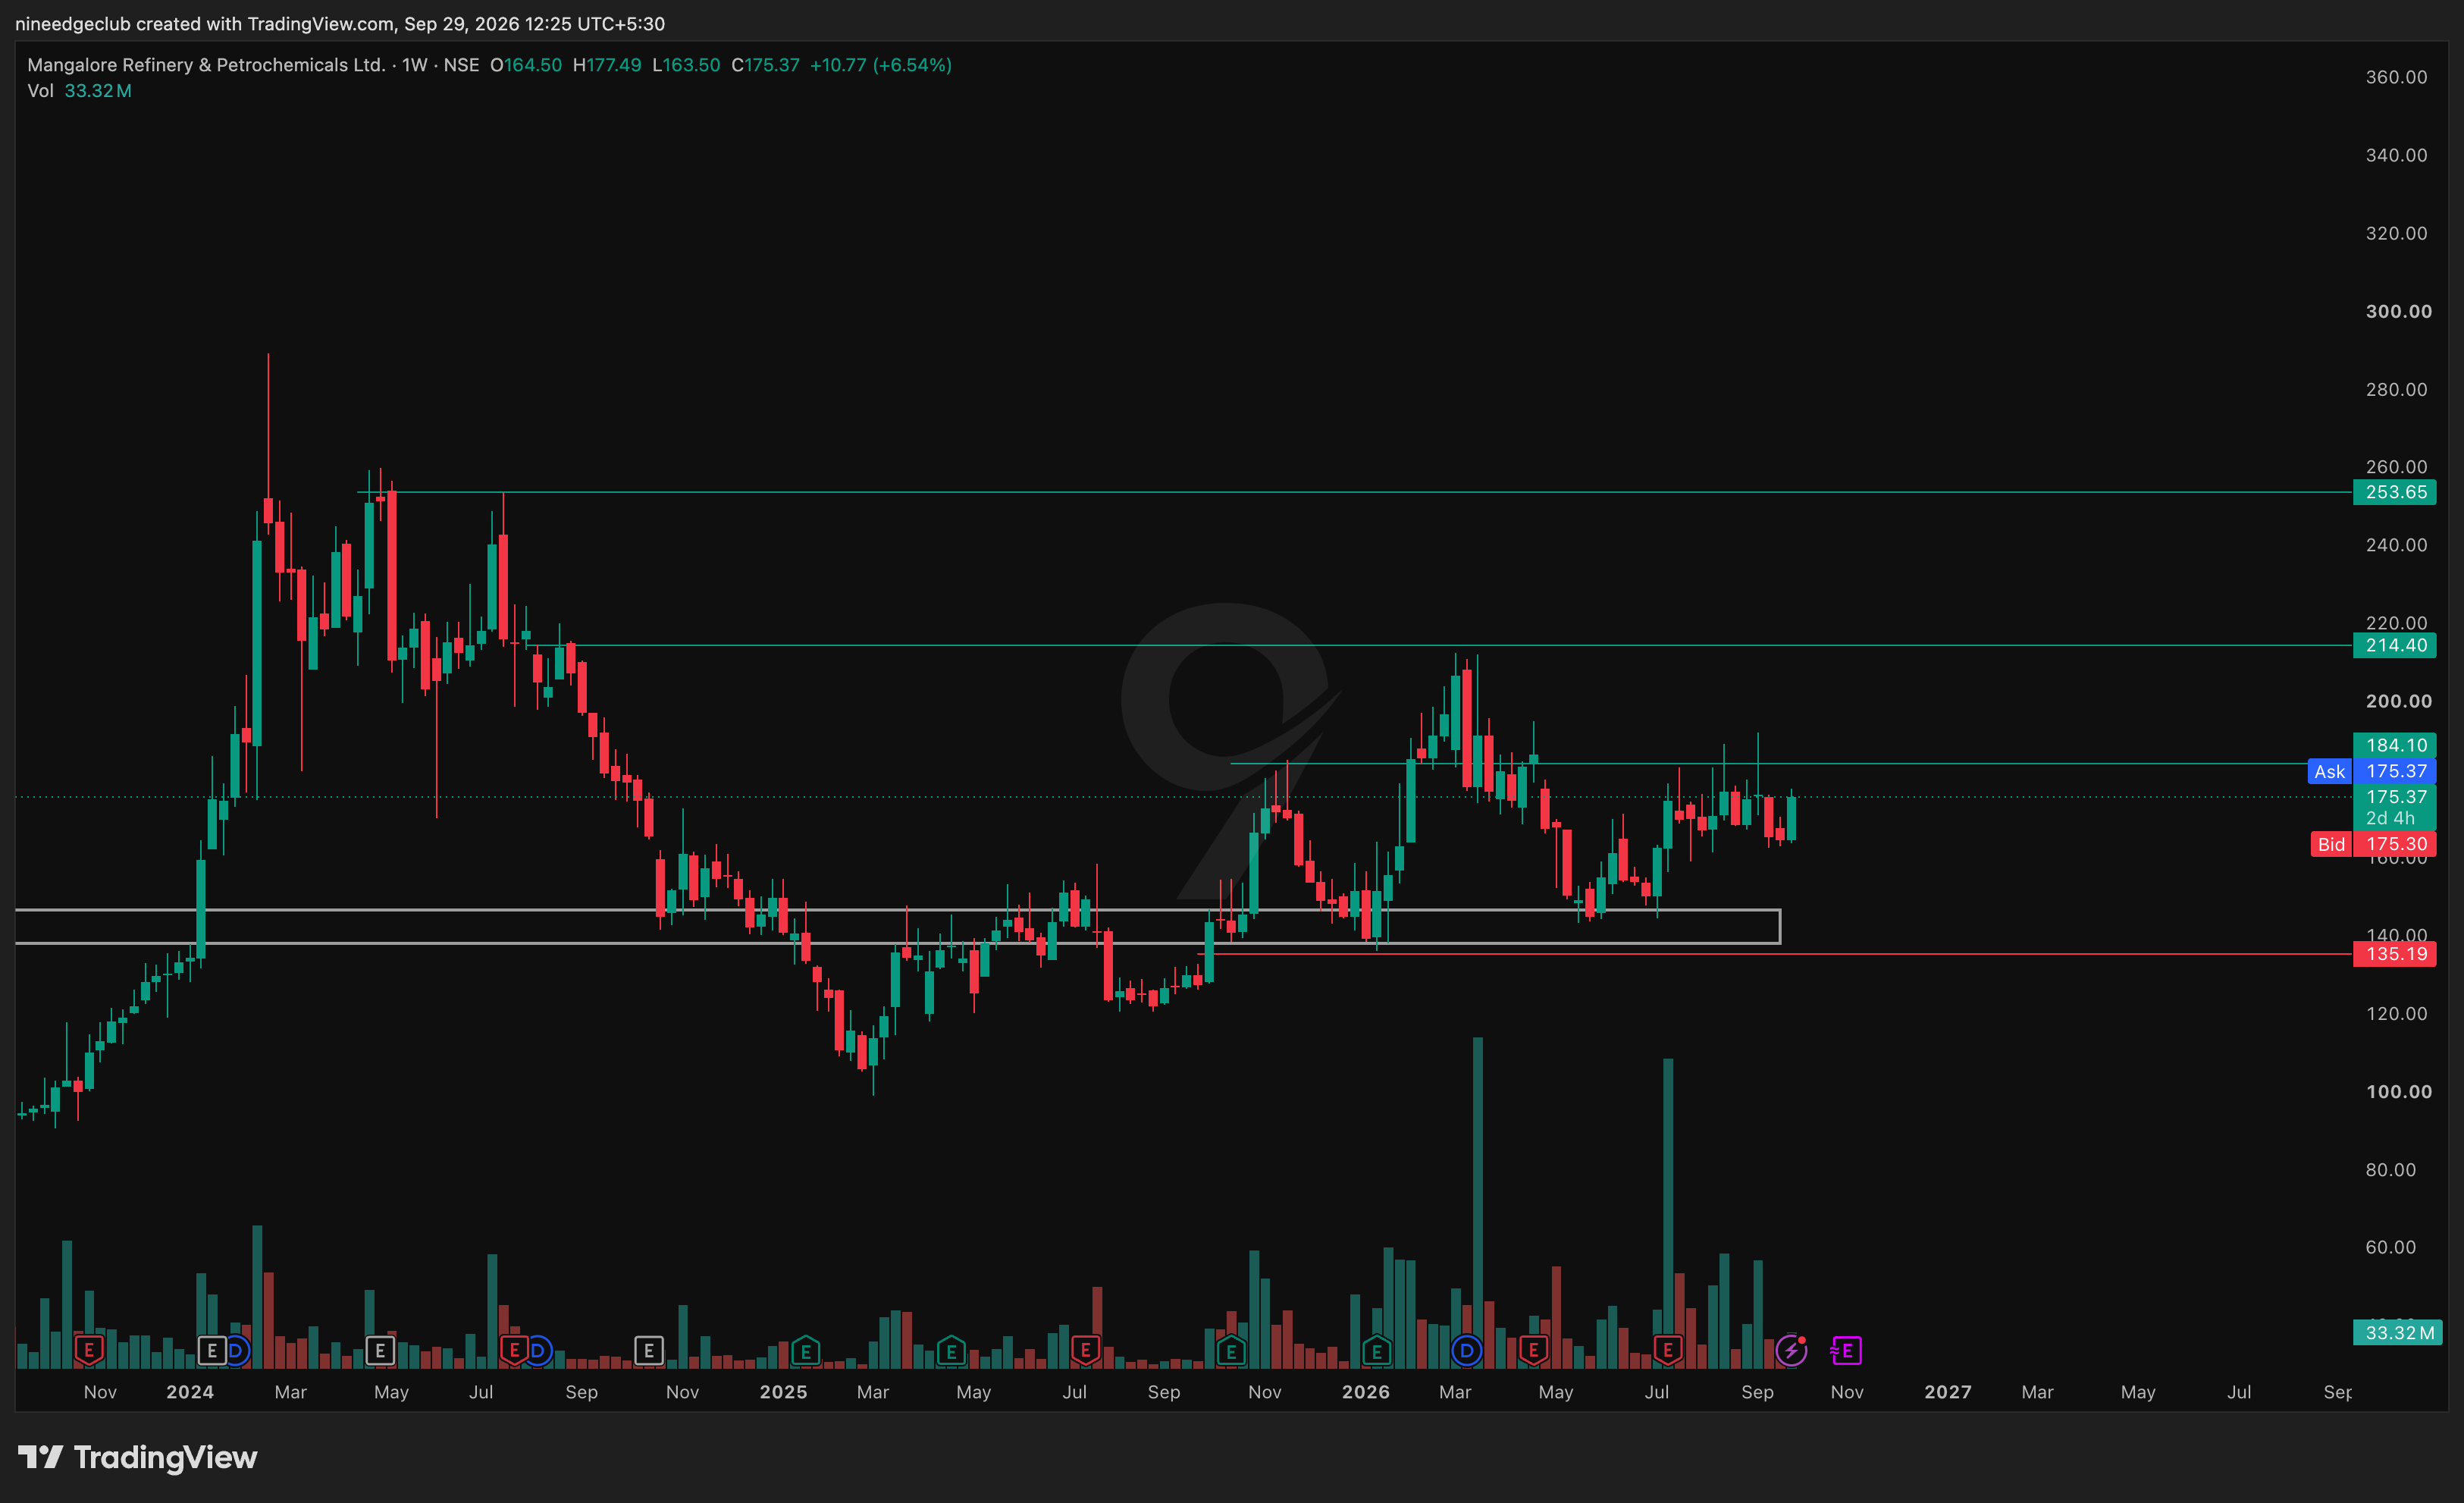
👉 Refer to the chart for my technical levels, support/resistance zones and price action view.
Disclaimer: Educational content only. Not investment advice. Please do your own research.