MAZAGON DOCK SHIPBUILDERS
(NSE: MAZDOCK)
Business:
One of India’s leading defence shipyards, focused primarily on warships & submarinesKey beneficiary of India’s long-term defence indigenisation + naval modernisationStrong execution capabilities in complex naval platforms.Q1 FY27 Performance:
Revenue: ₹2,943 Cr | +12.1% YoYEBITDA: ₹447 Cr | +48% YoYEBITDA Margin: 15.2% vs 11.5% YoYPAT: ₹550 Cr | +21.7% YoYEPS: ₹13.62 | +21.5% YoYThe key takeaway: profit growth significantly outpaced revenue growth, supported by better operating margins.
Order Book 📦
Order book stood at approximately ₹18,218 Cr as of June 2026Portfolio spans destroyers, submarines, Coast Guard vessels and other marine projectsExisting execution provides meaningful medium-term revenue visibility.Key Positives 🟢
Strong positioning in India’s strategic defence ecosystemHigh entry barriers & specialised shipbuilding capabilitiesQ1 margin expansion is a major positivePAT growing faster than revenueLong-term tailwinds from Make in India + defence indigenisationSubmarine & warship programs can provide sizeable future opportunitiesStrong execution track record.Growth Triggers 🚀
Fresh naval orders / submarine contractsNew destroyer & submarine programsIncreasing defence spendingHigher execution from existing order bookCapacity expansion and efficiency improvementsPotential international/export opportunities.What I’m Watching ⚠️
Order book declined to ₹18,218 Cr YoY, so fresh order inflows are importantShipbuilding revenues can be lumpy due to milestone-based executionMargin sustainability after the sharp Q1 expansionWorking-capital / cash-flow movementValuation - strong fundamentals are already reflected to some extent in the stock price.Overall View:
MAZDOCK remains a strong structural defence play with high entry barriers, specialised capabilities and strong profitability.
The biggest variables from here are new order wins + execution + sustainability of margins.
Technical Setup:
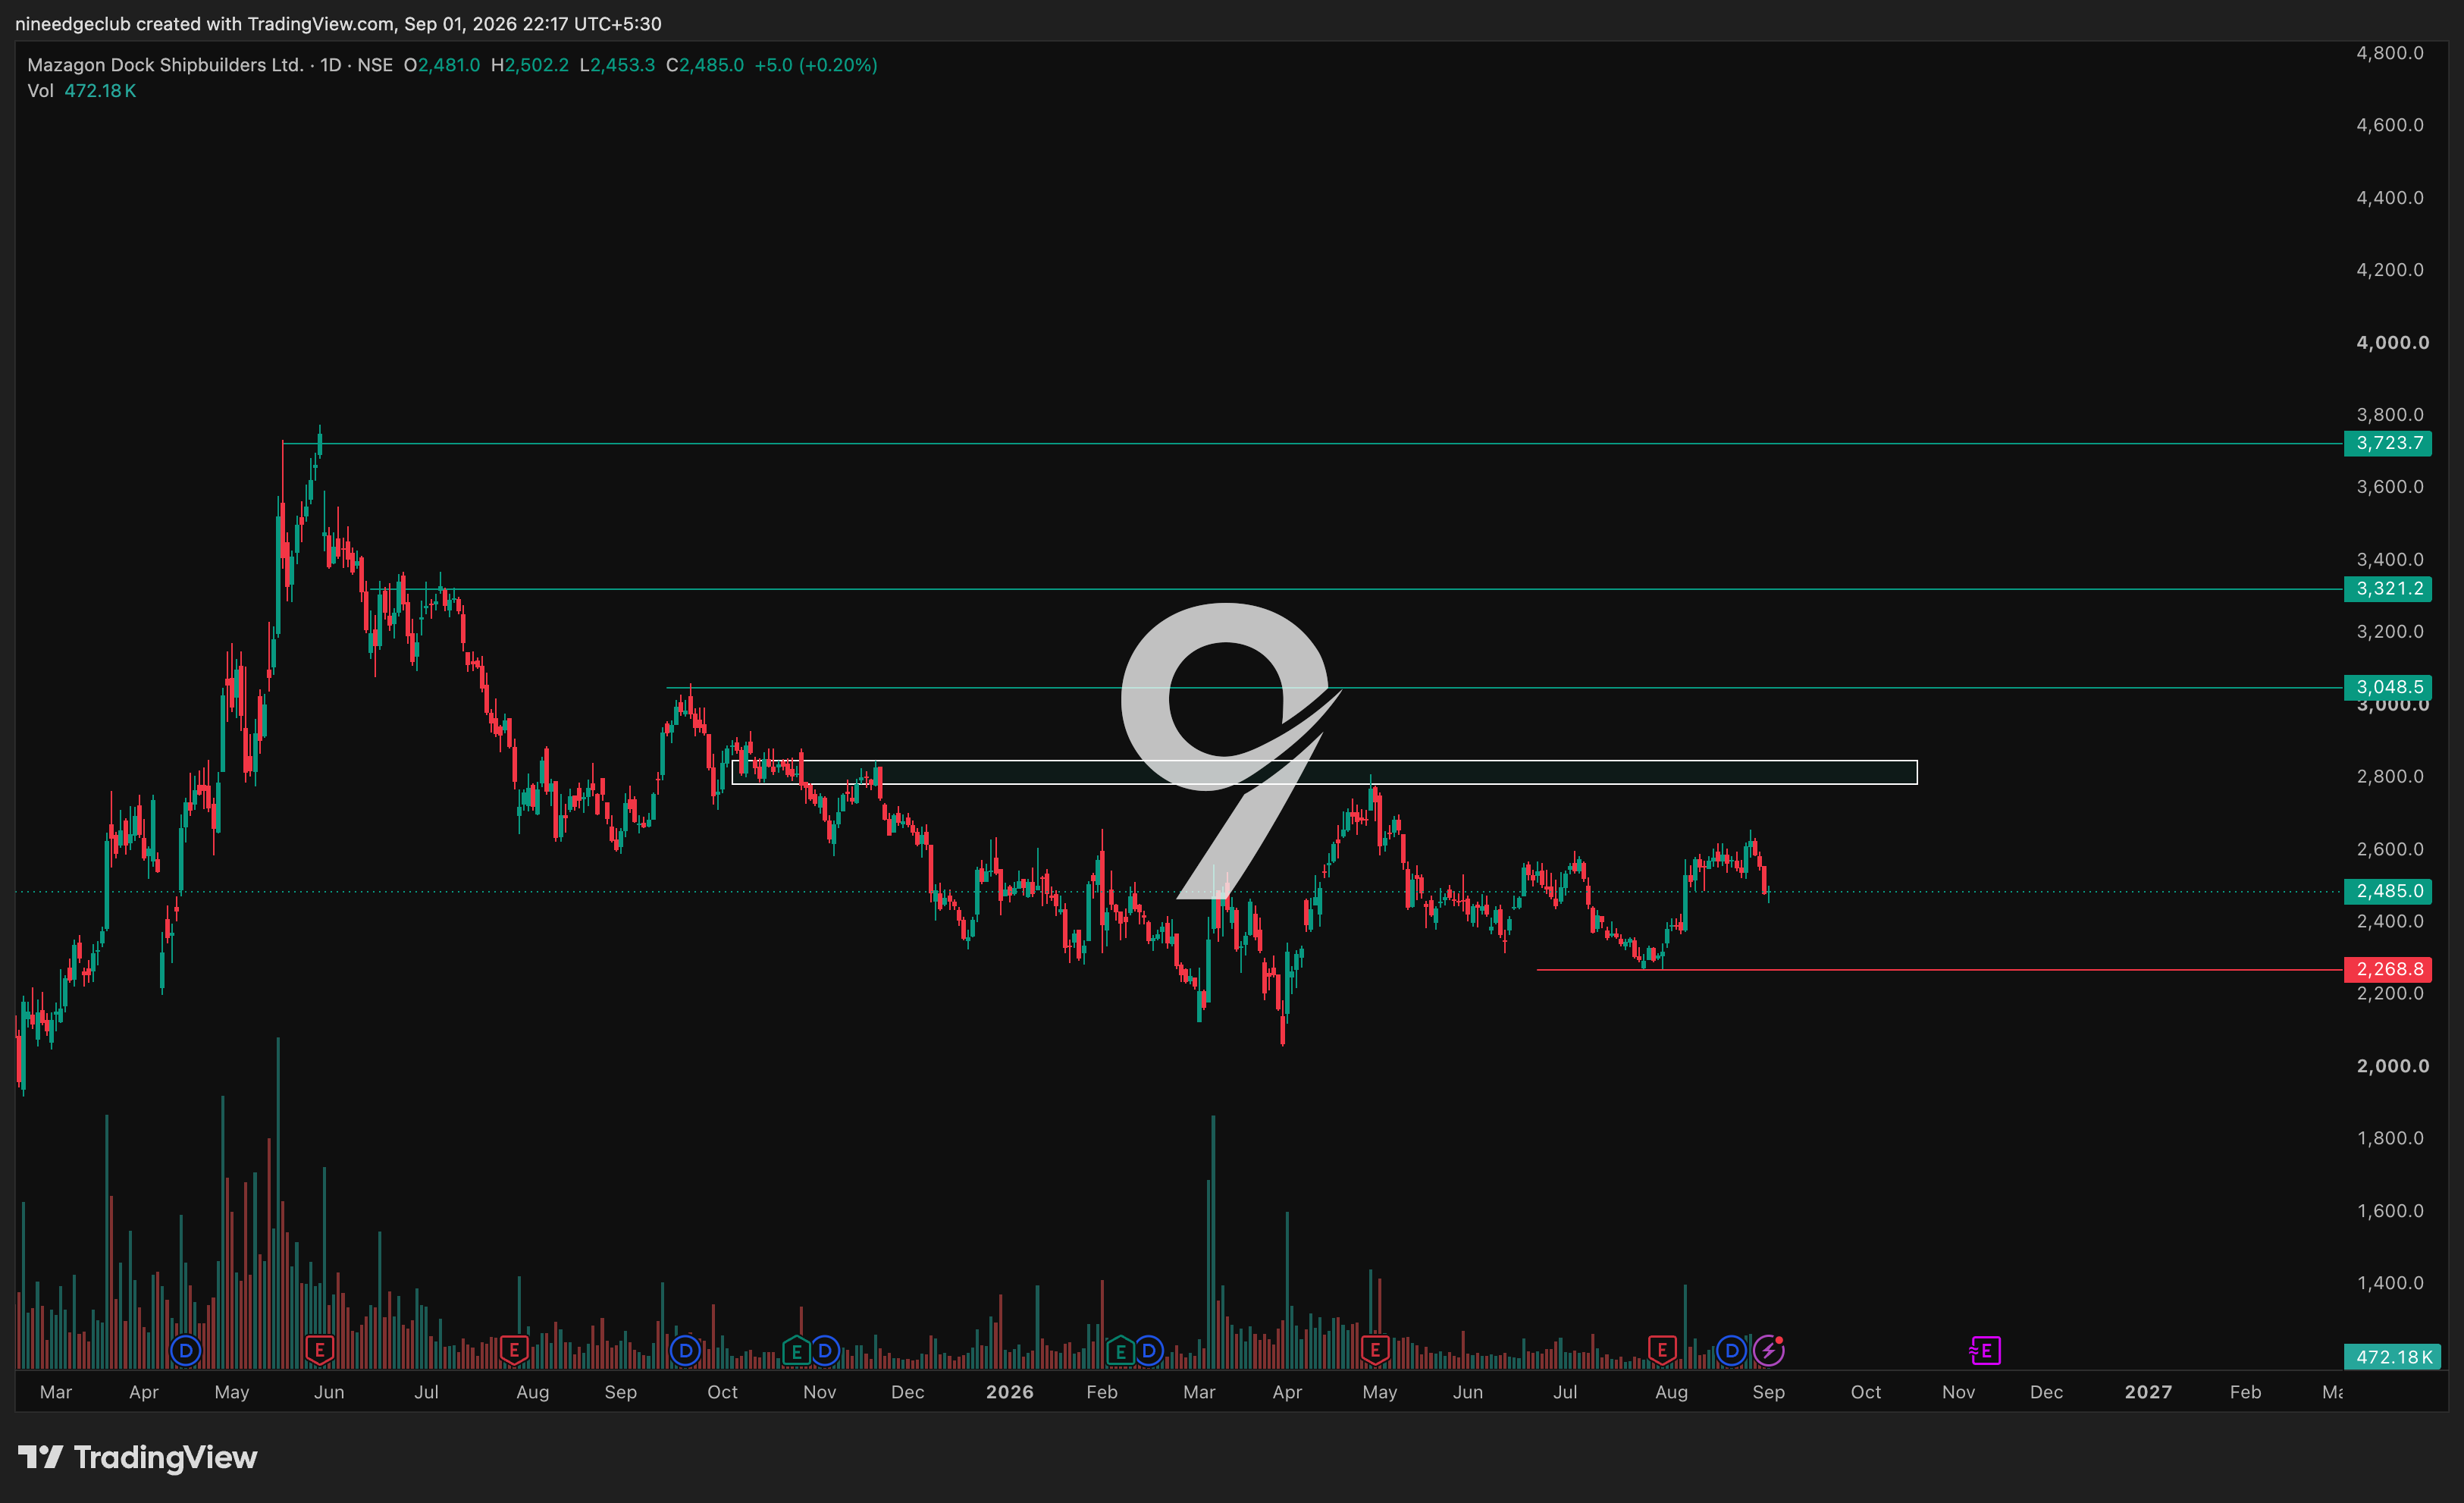
👉 Refer to the chart below for my technical levels, breakout/support zones and price-action view.
Disclaimer: Educational content only. Not investment advice. Please do your own research.