MANALI PETROCHEMICALS
(NSE: MANALIPETC)
Business:
Manali Petrochemicals manufactures Propylene Glycol, Polyols, Propylene Oxide and related chemicalsIts products are used across pharmaceuticals, food, personal care, automotive, refrigeration, construction and furniture applications.Q1 FY27 Performance 📊
Revenue: ₹274.7 Cr | +17.1% YoYOperating Profit: ₹82.8 Cr | +262.7% YoYPBT: ₹84.5 Cr | +323.5% YoYPAT: ₹64.4 Cr, versus ₹29.0 Cr in Q4 FY26The major positive is the sharp improvement in operating profitability despite only moderate revenue growth.Key Positives 🟢
Expanded Propylene Glycol facility was commissioned in July 2025, increasing production capacityNew manufacturing facility planned in western India can improve geographic reach and supply efficiencyPG demand remains supported by pharma, food and personal care applicationsThe company has been working on cost optimisation and operational efficiency after a difficult FY25.Growth Triggers 🚀
Better utilisation of the expanded PG capacityRecovery in Polyol demandImprovement in product realisations and spreadsLower impact from cheaper importsNew western India facilityContinued improvement in operating marginsWhat I’m Watching ⚠️
FY25 was challenging because of cheaper imports and pricing pressurePolyol volumes and realisations need to recoverPetrochemical margins can remain cyclicalQ1 profitability was exceptionally strong, so sustainability over the next few quarters is importantOverall View:
Manali Petrochemicals is showing a sharp earnings recovery after a difficult period.
The biggest positive for me is the combination of capacity expansion + improving margins + recovery in operating performance.
The next few quarters will be important to confirm whether the Q1 improvement can translate into a sustainable earnings cycle.
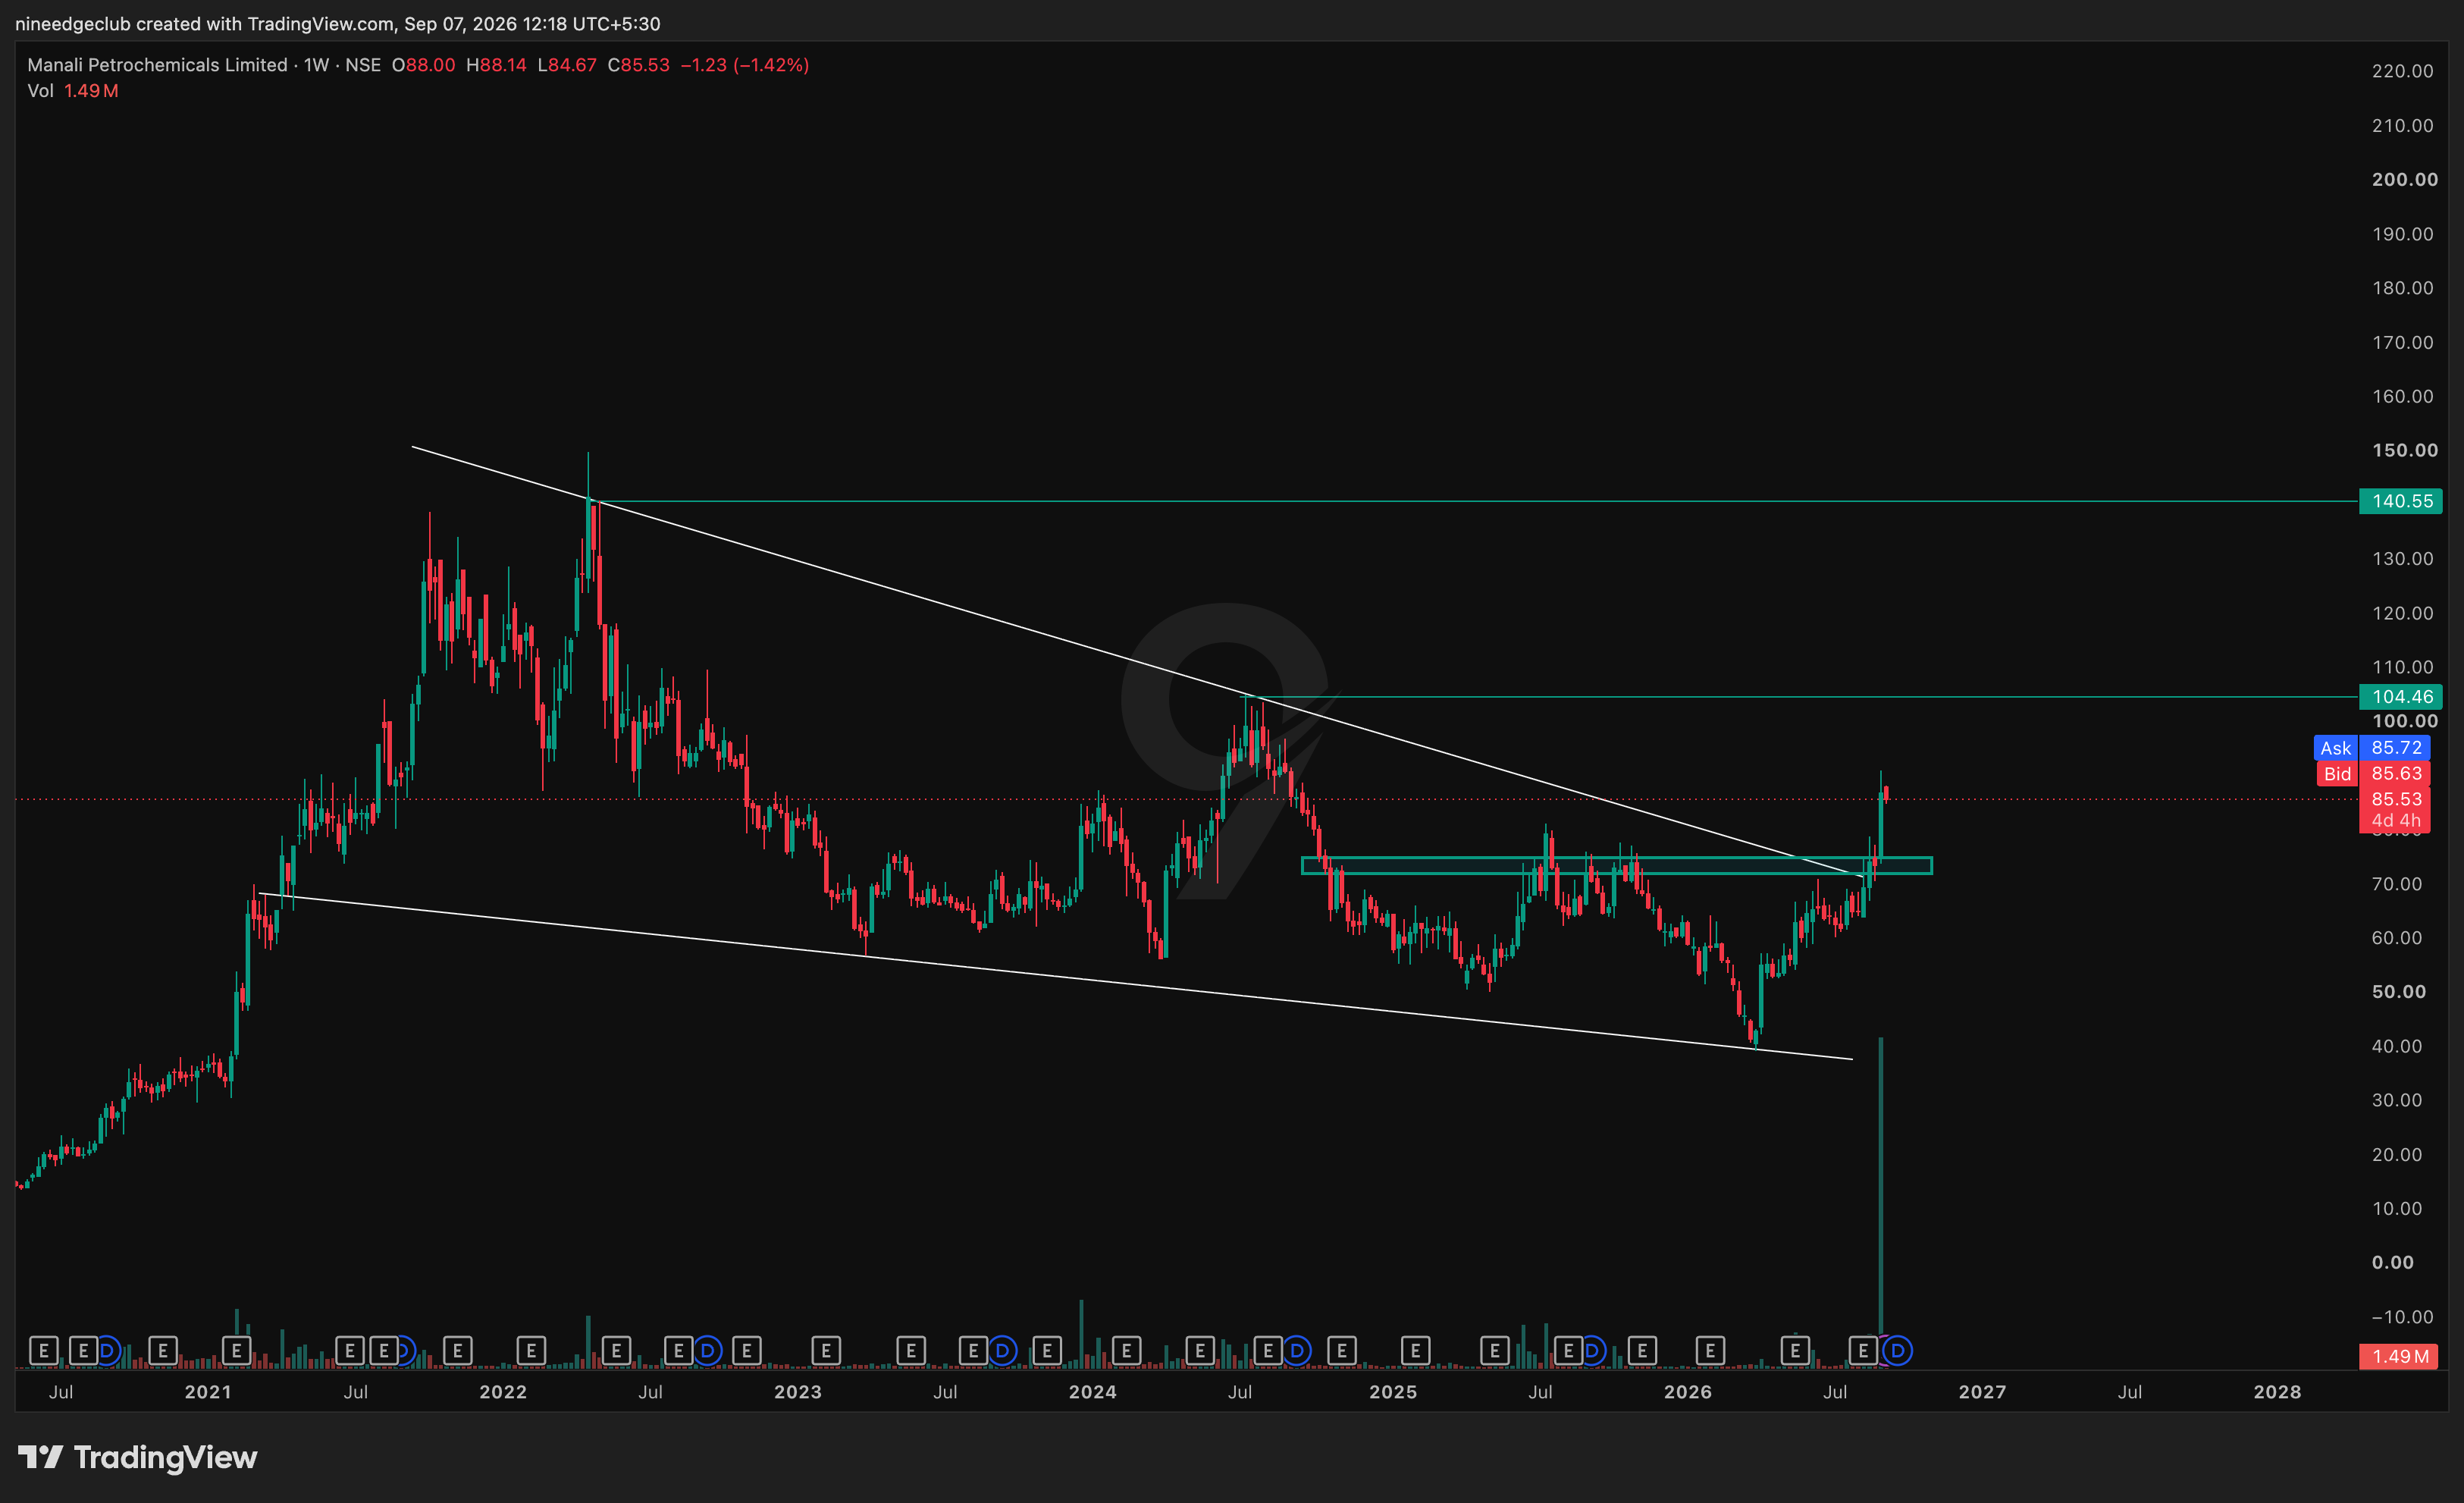
Technical Setup:
👉 Refer to the chart for my technical levels, support/resistance zones and price action view.
Disclaimer: Educational content only. Not investment advice. Please do your own research.