Lemon Tree Hotels Limited
(NSE: LEMONTREE)
Business:
Lemon Tree Hotels operates across multiple segments and brands including Lemon Tree, Lemon Tree Premier, Aurika, Red Fox and Keys.
The company is increasingly using an asset light model, expanding through management contracts and franchise agreements rather than owning every hotel.
Q1 FY27 Performance 🚀
Revenue ₹346.8 Cr, up 9% YoYNet EBITDA ₹151.9 Cr, up 7% YoYPAT ₹57.3 Cr, up 19% YoYOccupancy 75.7%, up 314 bps YoYGross ARR ₹6,361, up 2% YoYAdjusted EBITDA margin improved significantlyThe most important operating metric for me is occupancy. A 314 bps improvement shows stronger demand and better utilisation of the existing portfolio.
EXPANSION STORY
The company opened 6 hotels with 334 rooms during Q1 FY27 and signed another 13 hotels with 1,020 rooms.
Its total operational plus pipeline inventory has reached approximately 23,381 rooms across 279 hotels.
That is where the longer term operating leverage can come from.
More rooms under management and franchise contracts can allow Lemon Tree to grow its fee income without requiring the same level of capital investment as an owned hotel model.
KEY POSITIVES:
📌 Occupancy improving strongly
📌 Large room pipeline
📌 Asset light expansion
📌 Strong brand presence in the mid market segment
📌 Keys portfolio showing strong RevPAR growth
📌 Debt reduction underway
📌 Lower cost of debt
Gross debt declined around 11% YoY to ₹1,475 Cr, while cost of debt reduced to around 7.48%.
BIG CATALYST 🚀
The Indian hospitality cycle remains favourable with rising domestic travel, business travel, weddings, events and tourism.
Lemon Tree is also expanding its presence aggressively.
Recent developments include expansion into Bandra East near BKC, new properties in Nashik and Jabalpur, and multiple Keys properties across smaller cities.
IMPORTANT MONITORABLE ⚠️
The biggest thing I would watch is RevPAR growth versus expansion.
Opening more hotels is positive, but ultimately the value comes from:
Higher occupancyHigher room ratesBetter RevPARStrong cash generationControlled debtThe company is also progressing with its scheme of arrangement and proposed Fleur Hotels listing, which could create an additional value discovery event.
Overall View:
LEMONTREE is becoming an interesting hospitality growth + asset light expansion + deleveraging story.
The combination of improving occupancy, a large pipeline and lower debt creates a good operating setup.
For me, the next confirmation is sustained RevPAR growth combined with disciplined expansion and further debt reduction.
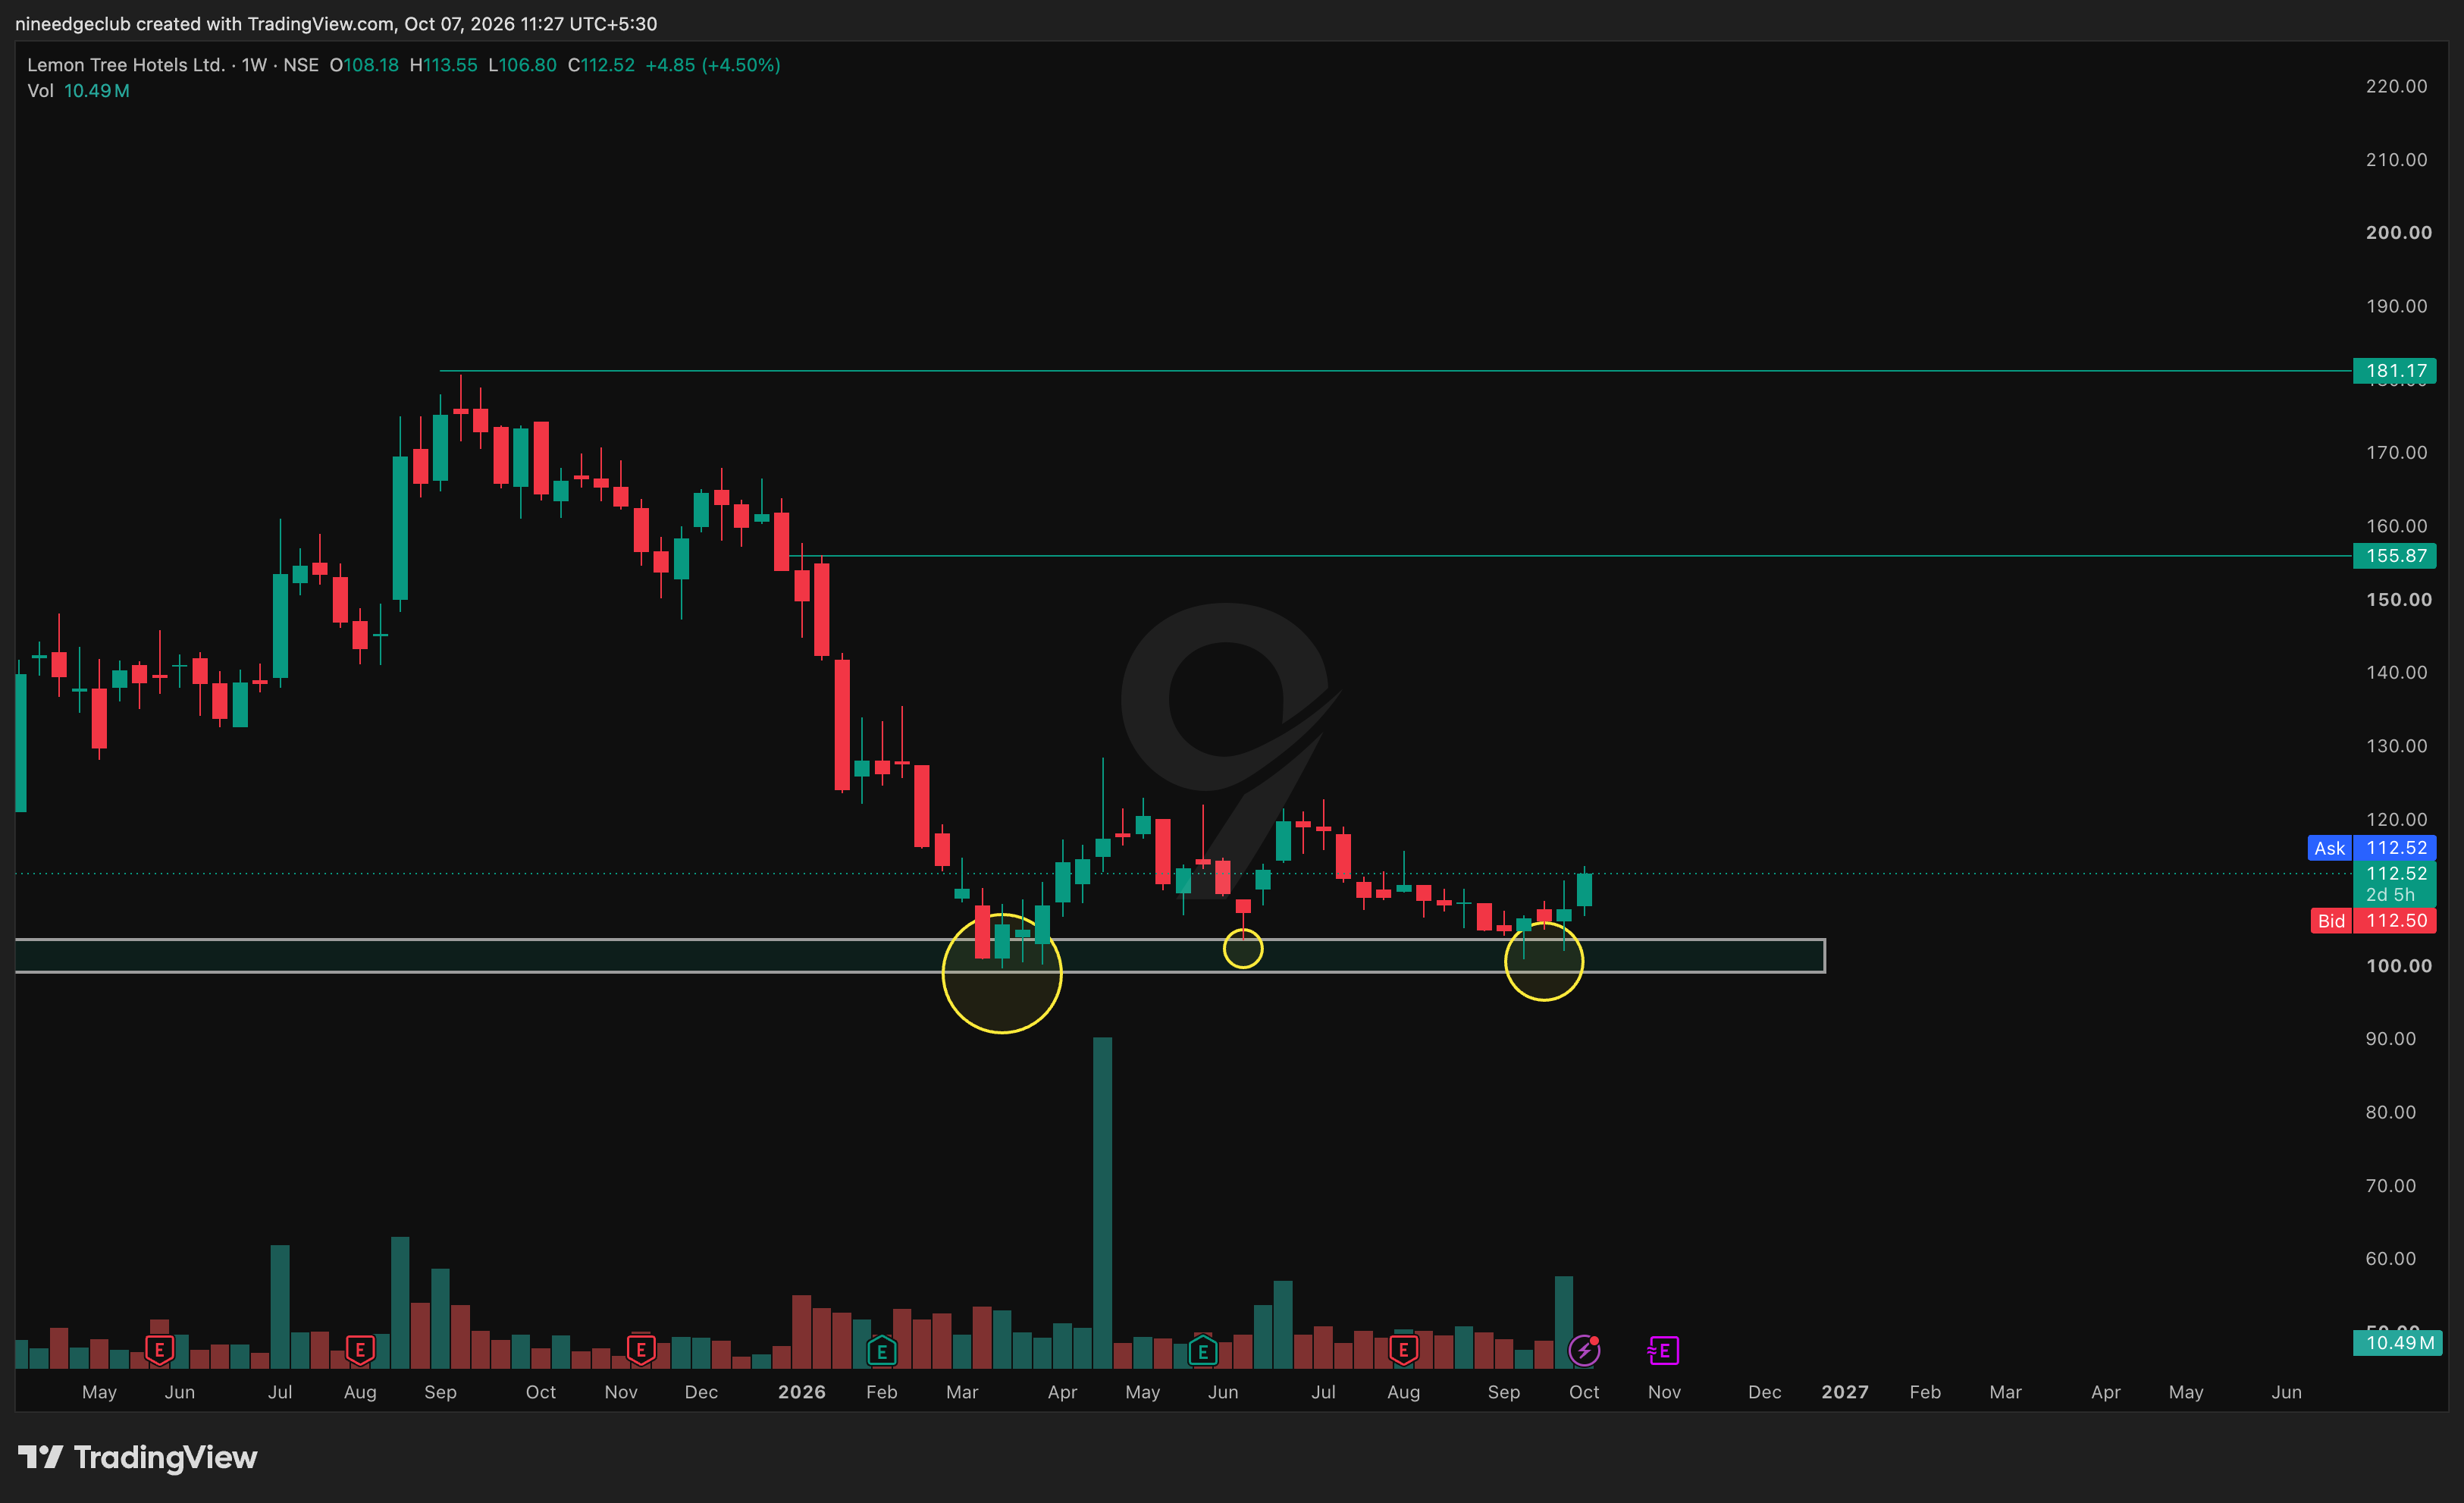
Technical Setup:
👉 Refer to the chart for my technical levels, support/resistance zones and price action view.
Disclaimer: Educational content only. Not investment advice. Please do your own research.