INDO COUNT INDUSTRIES
(NSE: ICIL)
Business:
One of India’s leading home textile manufacturers and exportersProducts include bed linen, sheets, quilts and other home textile productsStrong exposure to the US and international marketsQ1 FY27 Performance 📊
Revenue: ₹1,207 Cr | +25.9% YoYOperating Profit: ₹98 Cr | +34.2% YoYPAT: ₹63.2 Cr | +62% YoYOperating Margin improved to 8.1% from 6.6%EPS increased to ₹3.19 from ₹1.97 (mint)Key Positives 🟢
Revenue growth has accelerated stronglyPAT growth significantly ahead of revenue growthMargin expansion indicates improving operating efficiencyInternational presence provides access to large developed marketsAcquisition of Fluvitex USA has strengthened the company’s US distribution and customer reachHome textile demand recovery can provide further operating leverageGrowth Triggers 🚀
Stronger US home textile demandHigher export volumesBetter product mix and realisationsSynergies from overseas acquisitionsCapacity utilisation improvementSustained margin expansionWhat I’m Watching ⚠️
Raw material prices, particularly cottonUS demand and consumer spendingCurrency movements affecting exportsFreight and logistics costsSustainability of the recent margin improvementWorking capital as the business scalesOverall View:
Indo Count is showing a clear earnings recovery, with Q1 FY27 particularly encouraging because profit growth substantially outpaced revenue growth.
The key from here is whether the company can sustain double digit revenue growth and improving margins over the next few quarters.
For me, the combination of export exposure + improving profitability + US market opportunity makes ICIL an interesting textile recovery story.
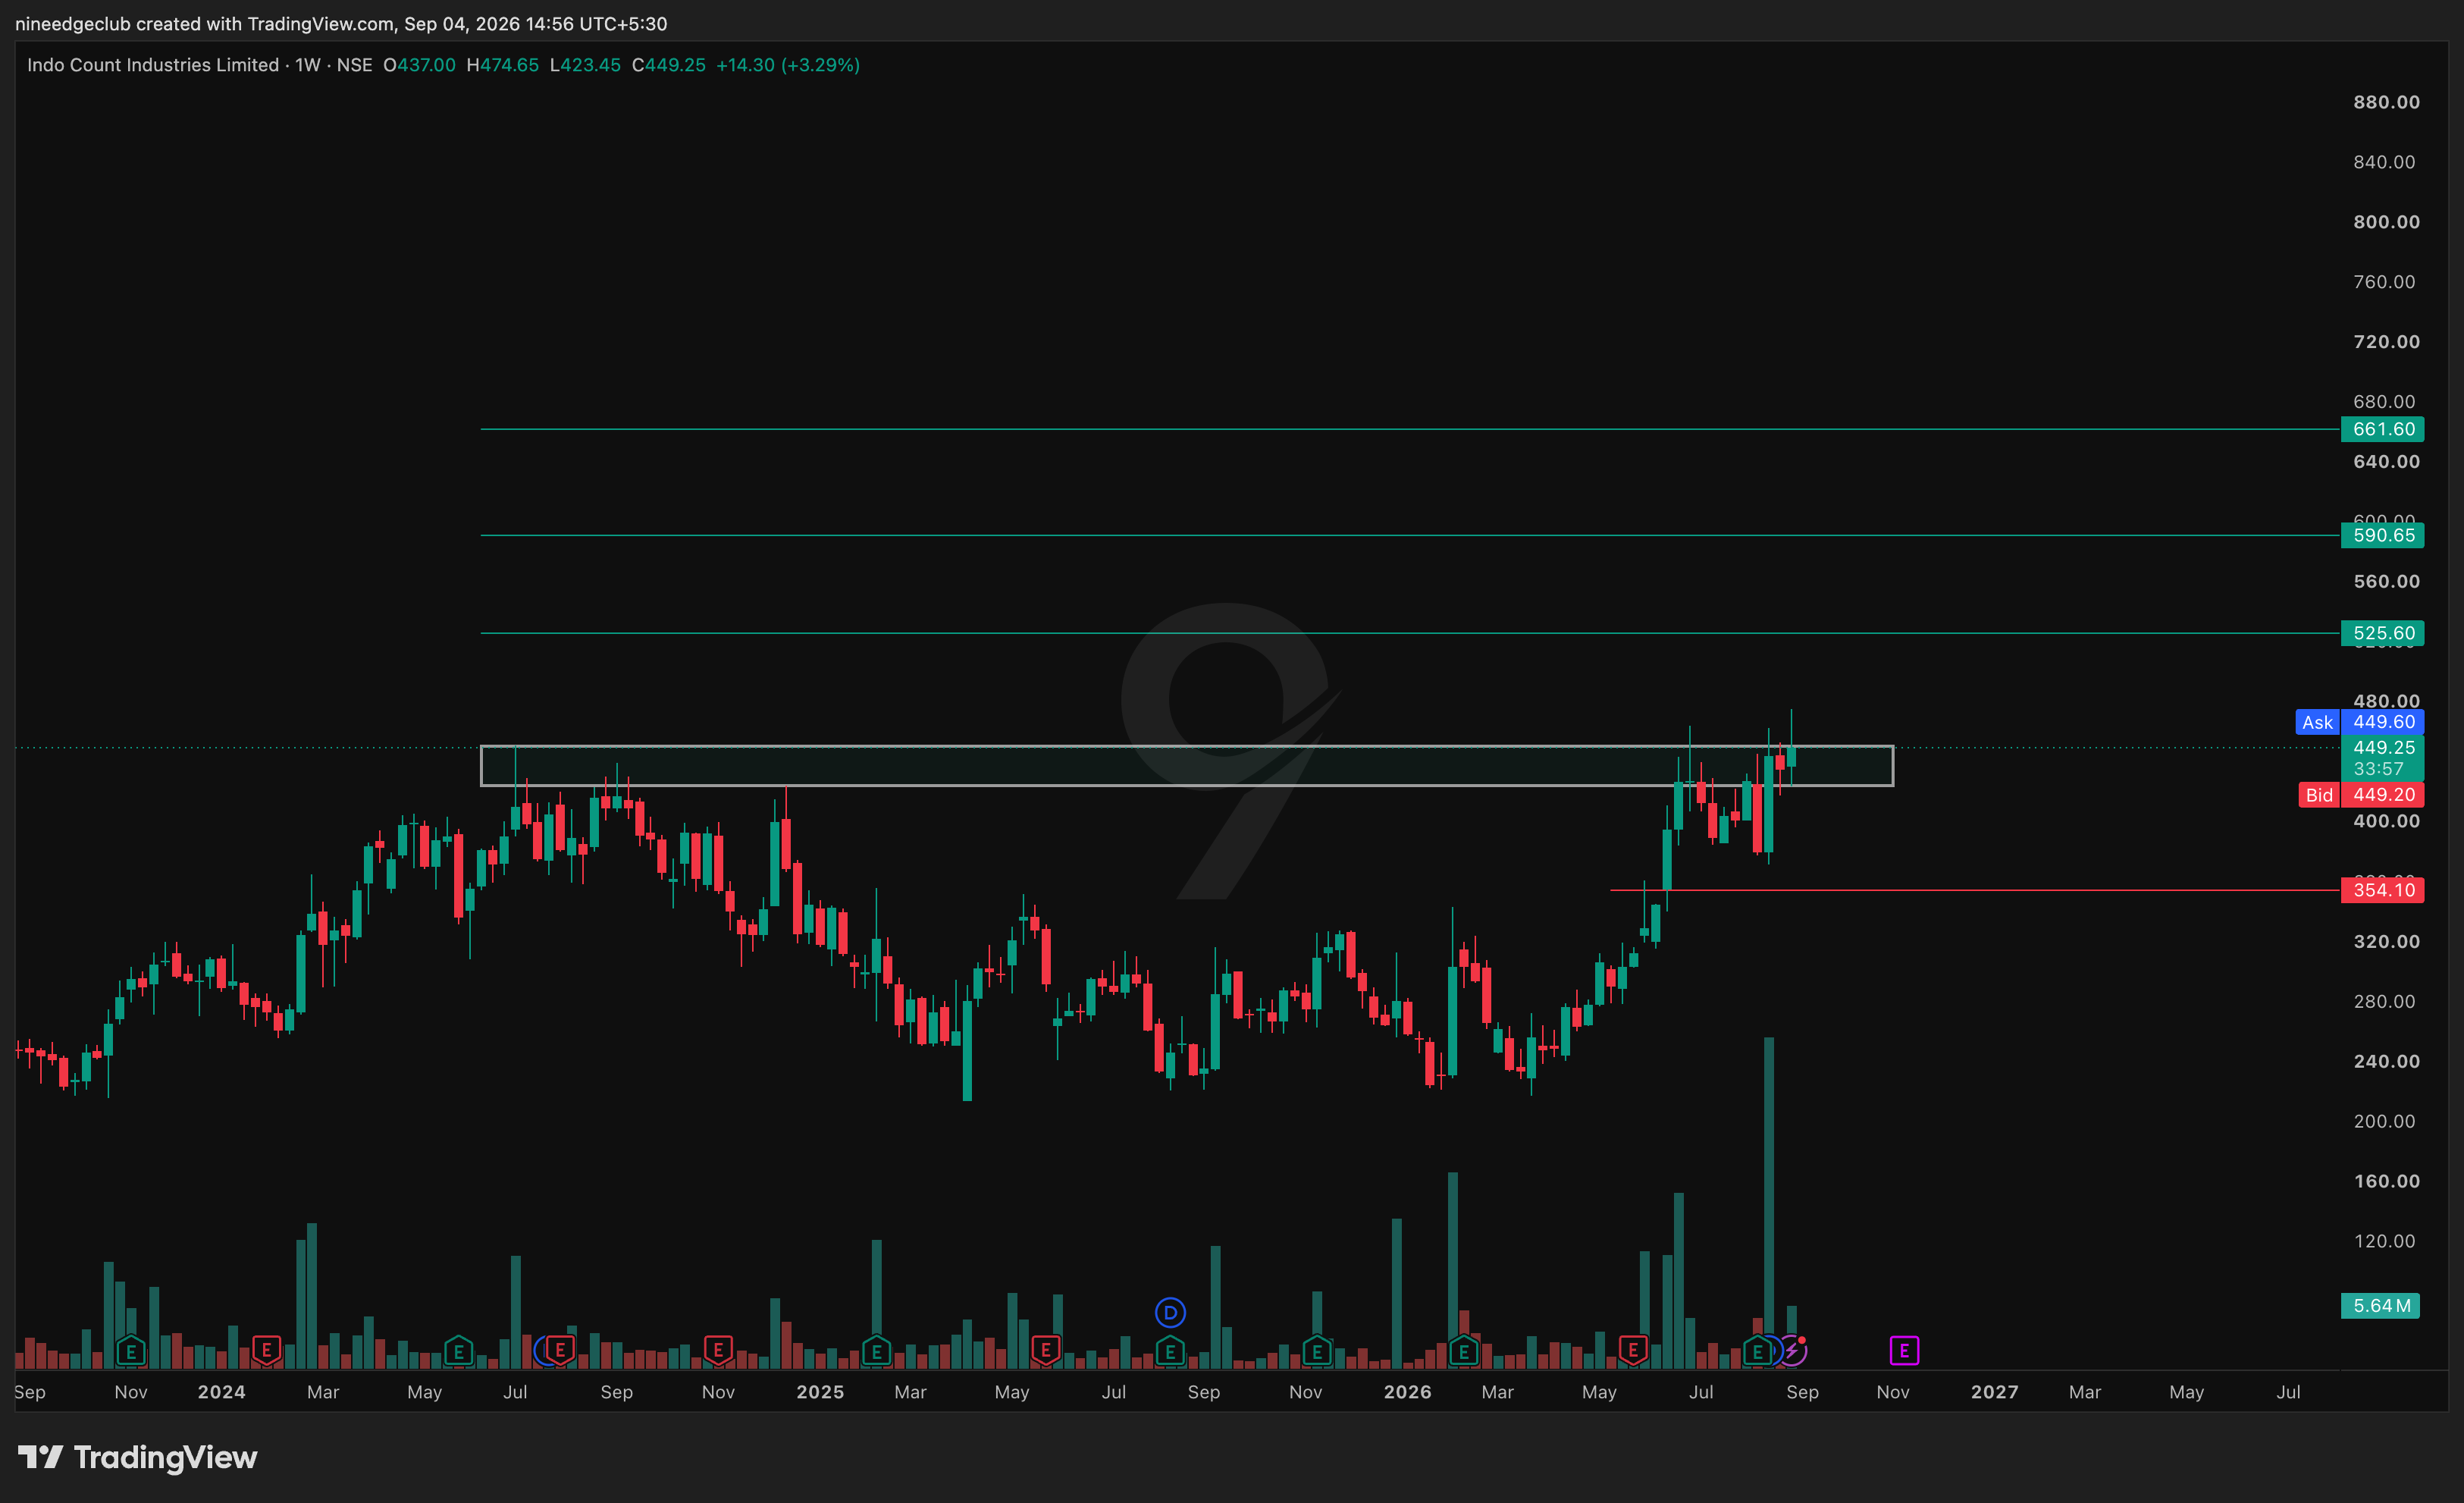
Technical Setup:
👉 Refer to the chart for my technical levels, support/resistance zones and price action view.
Disclaimer: Educational content only. Not investment advice. Please do your own research.