HIKAL LTD
(NSE: HIKAL)
Business:
Hikal is a global life sciences company operating across Pharmaceuticals and Crop ProtectionThe company works across APIs, intermediates, CDMO and specialised chemistryIncreasing focus on higher value APIs, complex chemistry and CDMO provides the longer term growth opportunityQ1 FY27 Performance 📊
Revenue: ₹403 Cr | +6.2% YoYEBITDA: ₹37 Cr | +47.4% YoYEBITDA Margin: 9.2% vs 6.6% YoYPAT: ₹7 Cr loss, compared with ₹22 Cr loss in Q1 FY26Pharmaceutical revenue: ₹233 Cr | +15.2% YoYPharma now contributes 58% of revenueKey Positives 🟢
Pharmaceutical business is showing a clear recovery in customer demand and utilisationProduct mix is shifting towards higher value final APIsDMF filings are increasing to 5 to 6 annually from 2 to 3 historicallyHPAPI laboratory and new cGMP pilot plant strengthen CDMO capabilitiesMore than 100 customer audits were successfully passed at the Bengaluru facilityGrowth Triggers 🚀
Recovery in Pharmaceutical CDMO demandChina Plus One outsourcing opportunityGrowth in complex APIs, HPAPI and ADC related chemistryCrop Protection volume recoveryCommercialisation of Personal Care productsFurther improvement in capacity utilisation and operating marginsWhat I’m Watching ⚠️
Crop Protection CDMO demand remains affected by customer inventory adjustmentsPricing pressure continues in the global Crop Protection businessUS FDA remediation at Bengaluru needs successful completionPAT is still negative, so the turnaround needs further confirmationDebt and cash flow need monitoring as the company continues investing in capacityOverall View:
Hikal is showing early signs of a turnaround, with improving pharmaceutical demand, stronger EBITDA and better capacity utilisation.
The bigger opportunity is the transition towards higher value APIs and CDMO, supported by new capabilities in complex chemistry.
For me, the key confirmation will be sustained revenue growth, margin expansion and a return to positive PAT over the coming quarters.
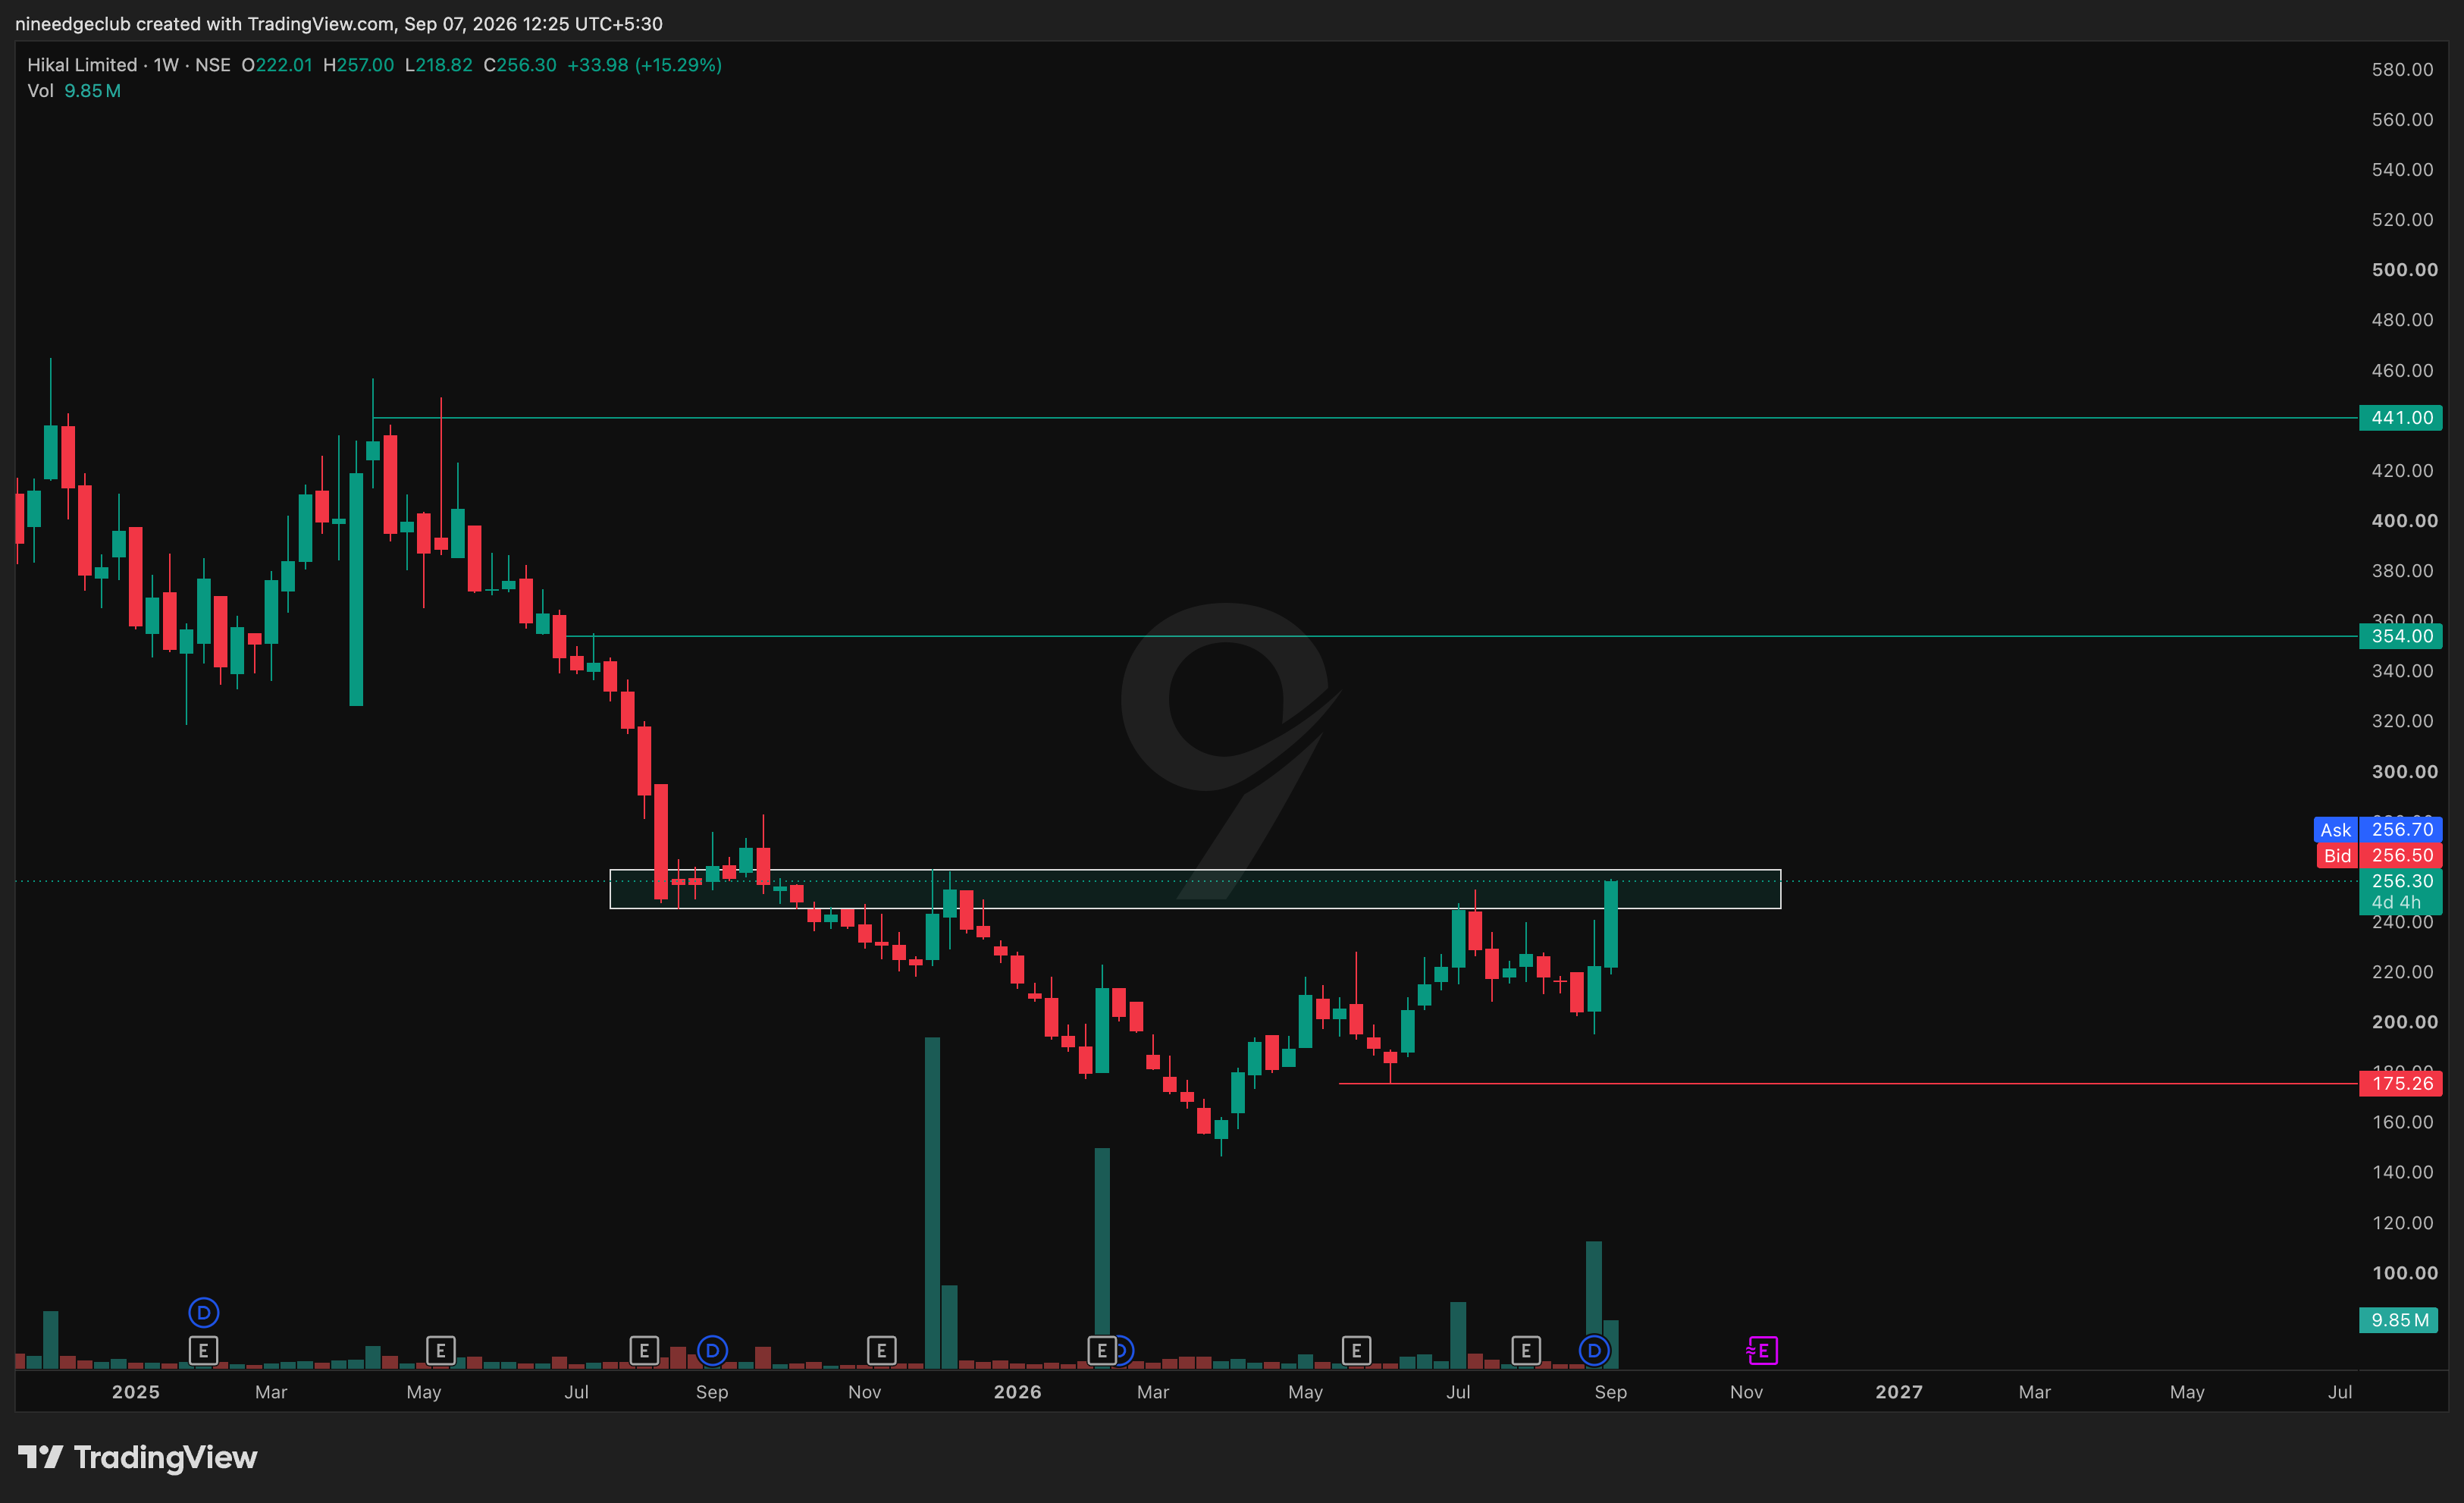
Technical Setup:
👉 Refer to the chart for my technical levels, support/resistance zones and price action view.
Disclaimer: Educational content only. Not investment advice. Please do your own research.