ENGINEERS INDIA LTD
(NSE: ENGINERSIN)
Business:
EIL is a leading engineering consultancy and project management company with strong exposure to energy, hydrocarbons and infrastructure.The company is gradually shifting towards higher margin consultancy services, while continuing to execute turnkey projects.Q1 FY27 Performance 📊
Revenue: ₹801 Cr | down 6.6% YoYPAT: ₹109 Cr | +55% YoYEBITDA: ₹155 Cr | +48.6% YoYEBITDA Margin: 18.55% vs 11.72% YoYConsultancy revenue increased to ₹499 Cr | +22% YoYTurnkey revenue declined to ₹302 CrOrder Book 🚀
Total order book stood at ₹14,424 Cr as of June 2026Consultancy accounts for ₹10,498 Cr, around 73% of the order bookTurnkey accounts for ₹3,926 CrThe higher consultancy mix is important because this segment carries significantly better margins than turnkey execution.Key Positives 🟢
Consultancy business is becoming a much larger part of the companyHigher margin mix is supporting strong profit growth despite lower revenueAlmost debt free balance sheetStrong presence across energy and infrastructureGrowing opportunities in nuclear energy, energy transition, critical minerals and data centres could provide additional avenues for diversification.Growth Triggers 🚀
Fresh consultancy order winsHigher execution from the existing order bookExpansion into new infrastructure and energy segmentsInternational consultancy opportunitiesManagement is targeting ₹8,000 Cr of new orders in FY27 and around ₹2,300 to ₹2,400 Cr consultancy revenue.What I’m Watching ⚠️
Revenue growth needs to recover after the Q1 declineConsultancy order inflow needs to remain strongMargin sustainability after the sharp Q1 improvementMiddle East exposure and geopolitical developmentsValuation after the strong rerating in the stock. (The Financial Express)Overall View:
Engineers India is undergoing an interesting business mix transformation.
The key attraction is the growing contribution from higher margin consultancy, which is allowing profits to grow much faster than revenue.
With a ₹14,424 Cr order book, strong balance sheet and opportunities beyond traditional oil and gas, EIL has multiple potential growth drivers.
The key confirmation from here is order inflow + consultancy growth + sustainability of margins.
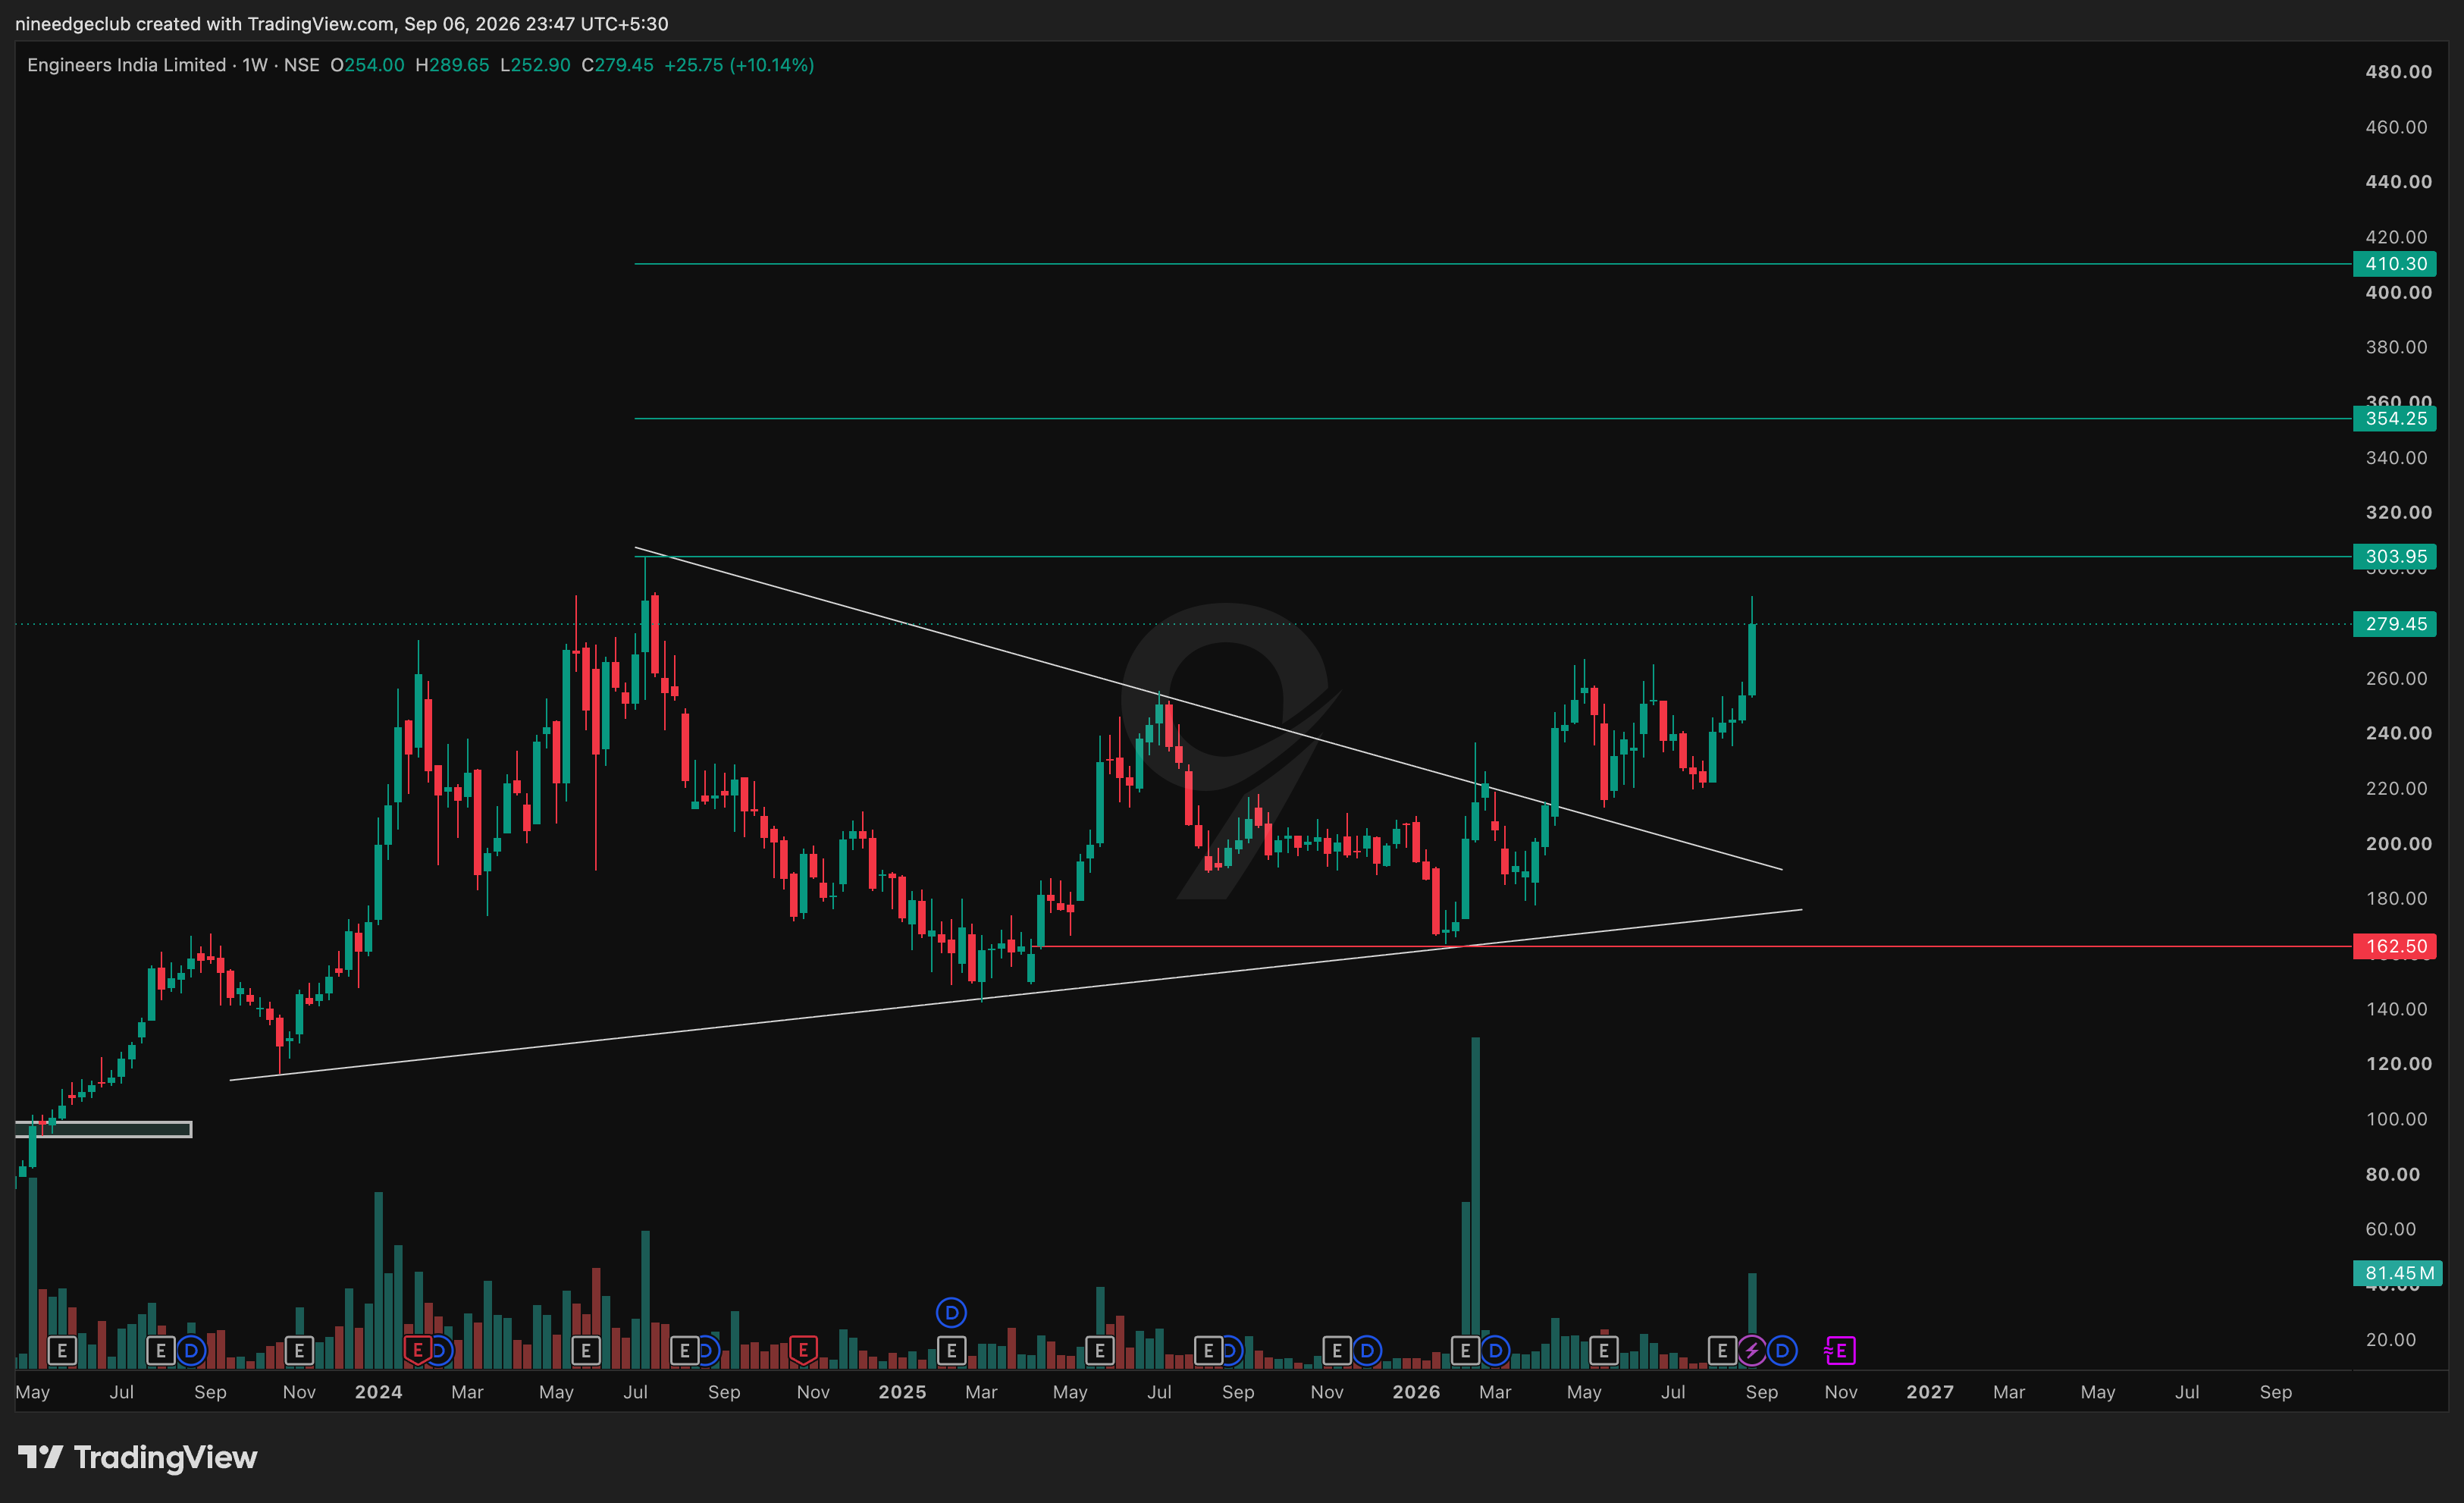
Technical Setup:
👉 Refer to the chart for my technical levels, support/resistance zones and price action view.
Disclaimer: Educational content only. Not investment advice. Please do your own research.