DREDGING CORPORATION OF INDIA
(NSE: DREDGECORP)
Business:
Dredging Corporation of India is India’s specialised dredging company, involved in maintenance and capital dredging for ports, waterways and other marine infrastructure.
The company also provides project management consultancy for ports, inland waterways, reservoirs, dams and flood control projects.
DCI is currently owned by four major port authorities, Visakhapatnam, Paradip, Jawaharlal Nehru and Deendayal. (Scribd)
Q1 FY27 Performance 📊
Revenue from operations ₹355.4 Cr, up 46.7% YoYOperating profit ₹20.3 Cr versus an operating loss of ₹24.8 Cr YoYPAT ₹11.2 Cr versus a loss of ₹31.4 Cr YoYOperating margin improved to 5.72%EPS ₹4.01 versus negative ₹8.33 YoYThe key takeaway is that the company moved back into profitability at both operating and net levels. (mint)
The Bigger Story 🚢
DCI is entering a major fleet modernisation phase.
The company is working on procuring 11 new dredgers under the Atmanirbhar Bharat initiative, while the new 12,000 cubic metre capacity dredger Godavari has been developed at Cochin Shipyard.
A larger and more modern fleet can improve capacity, efficiency and the company’s ability to participate in larger dredging projects. (Scribd)
Growth Triggers:
📌 India’s port capacity expansion
📌 Development of inland waterways
📌 Maintenance dredging at major ports
📌 New dredger fleet and higher capacity
📌 Capital dredging opportunities
📌 Offshore wind and marine infrastructure
📌 Potential entry into subsea cable related works
DCI has also identified subsea data cable works as a potential new business opportunity, alongside inland waterways, offshore wind and reservoir desilting. (The Times of India)
Capital Requirement ⚠️
Fleet expansion is capital intensive.
DCI has outlined a broader modernisation programme of around ₹4,000 Cr and plans to raise around ₹1,000 Cr through a rights issue, with the proposed equity participation remaining within government entities.
The objective is to strengthen the balance sheet, modernise the fleet and reduce financing pressure. (The Times of India)
What I’m Watching:
The biggest monitorable is whether fleet modernisation translates into sustained revenue and margin expansion.
Q1 showed a strong recovery, but operating margin was still only around 5.7%.
So the next phase needs to demonstrate:
Higher utilisation of the upgraded fleetBetter project executionSustainable operating marginsStrong order inflowImprovement in return on capitalOverall View:
DREDGECORP is a specialised play on India’s maritime infrastructure and port development cycle.
The combination of improving profitability, fleet modernisation and potential expansion into adjacent marine businesses creates a longer term growth opportunity.
The key question is no longer just revenue growth. It is whether the company can convert its fleet expansion and increasing infrastructure demand into consistently higher margins and returns.
Technical Setup:
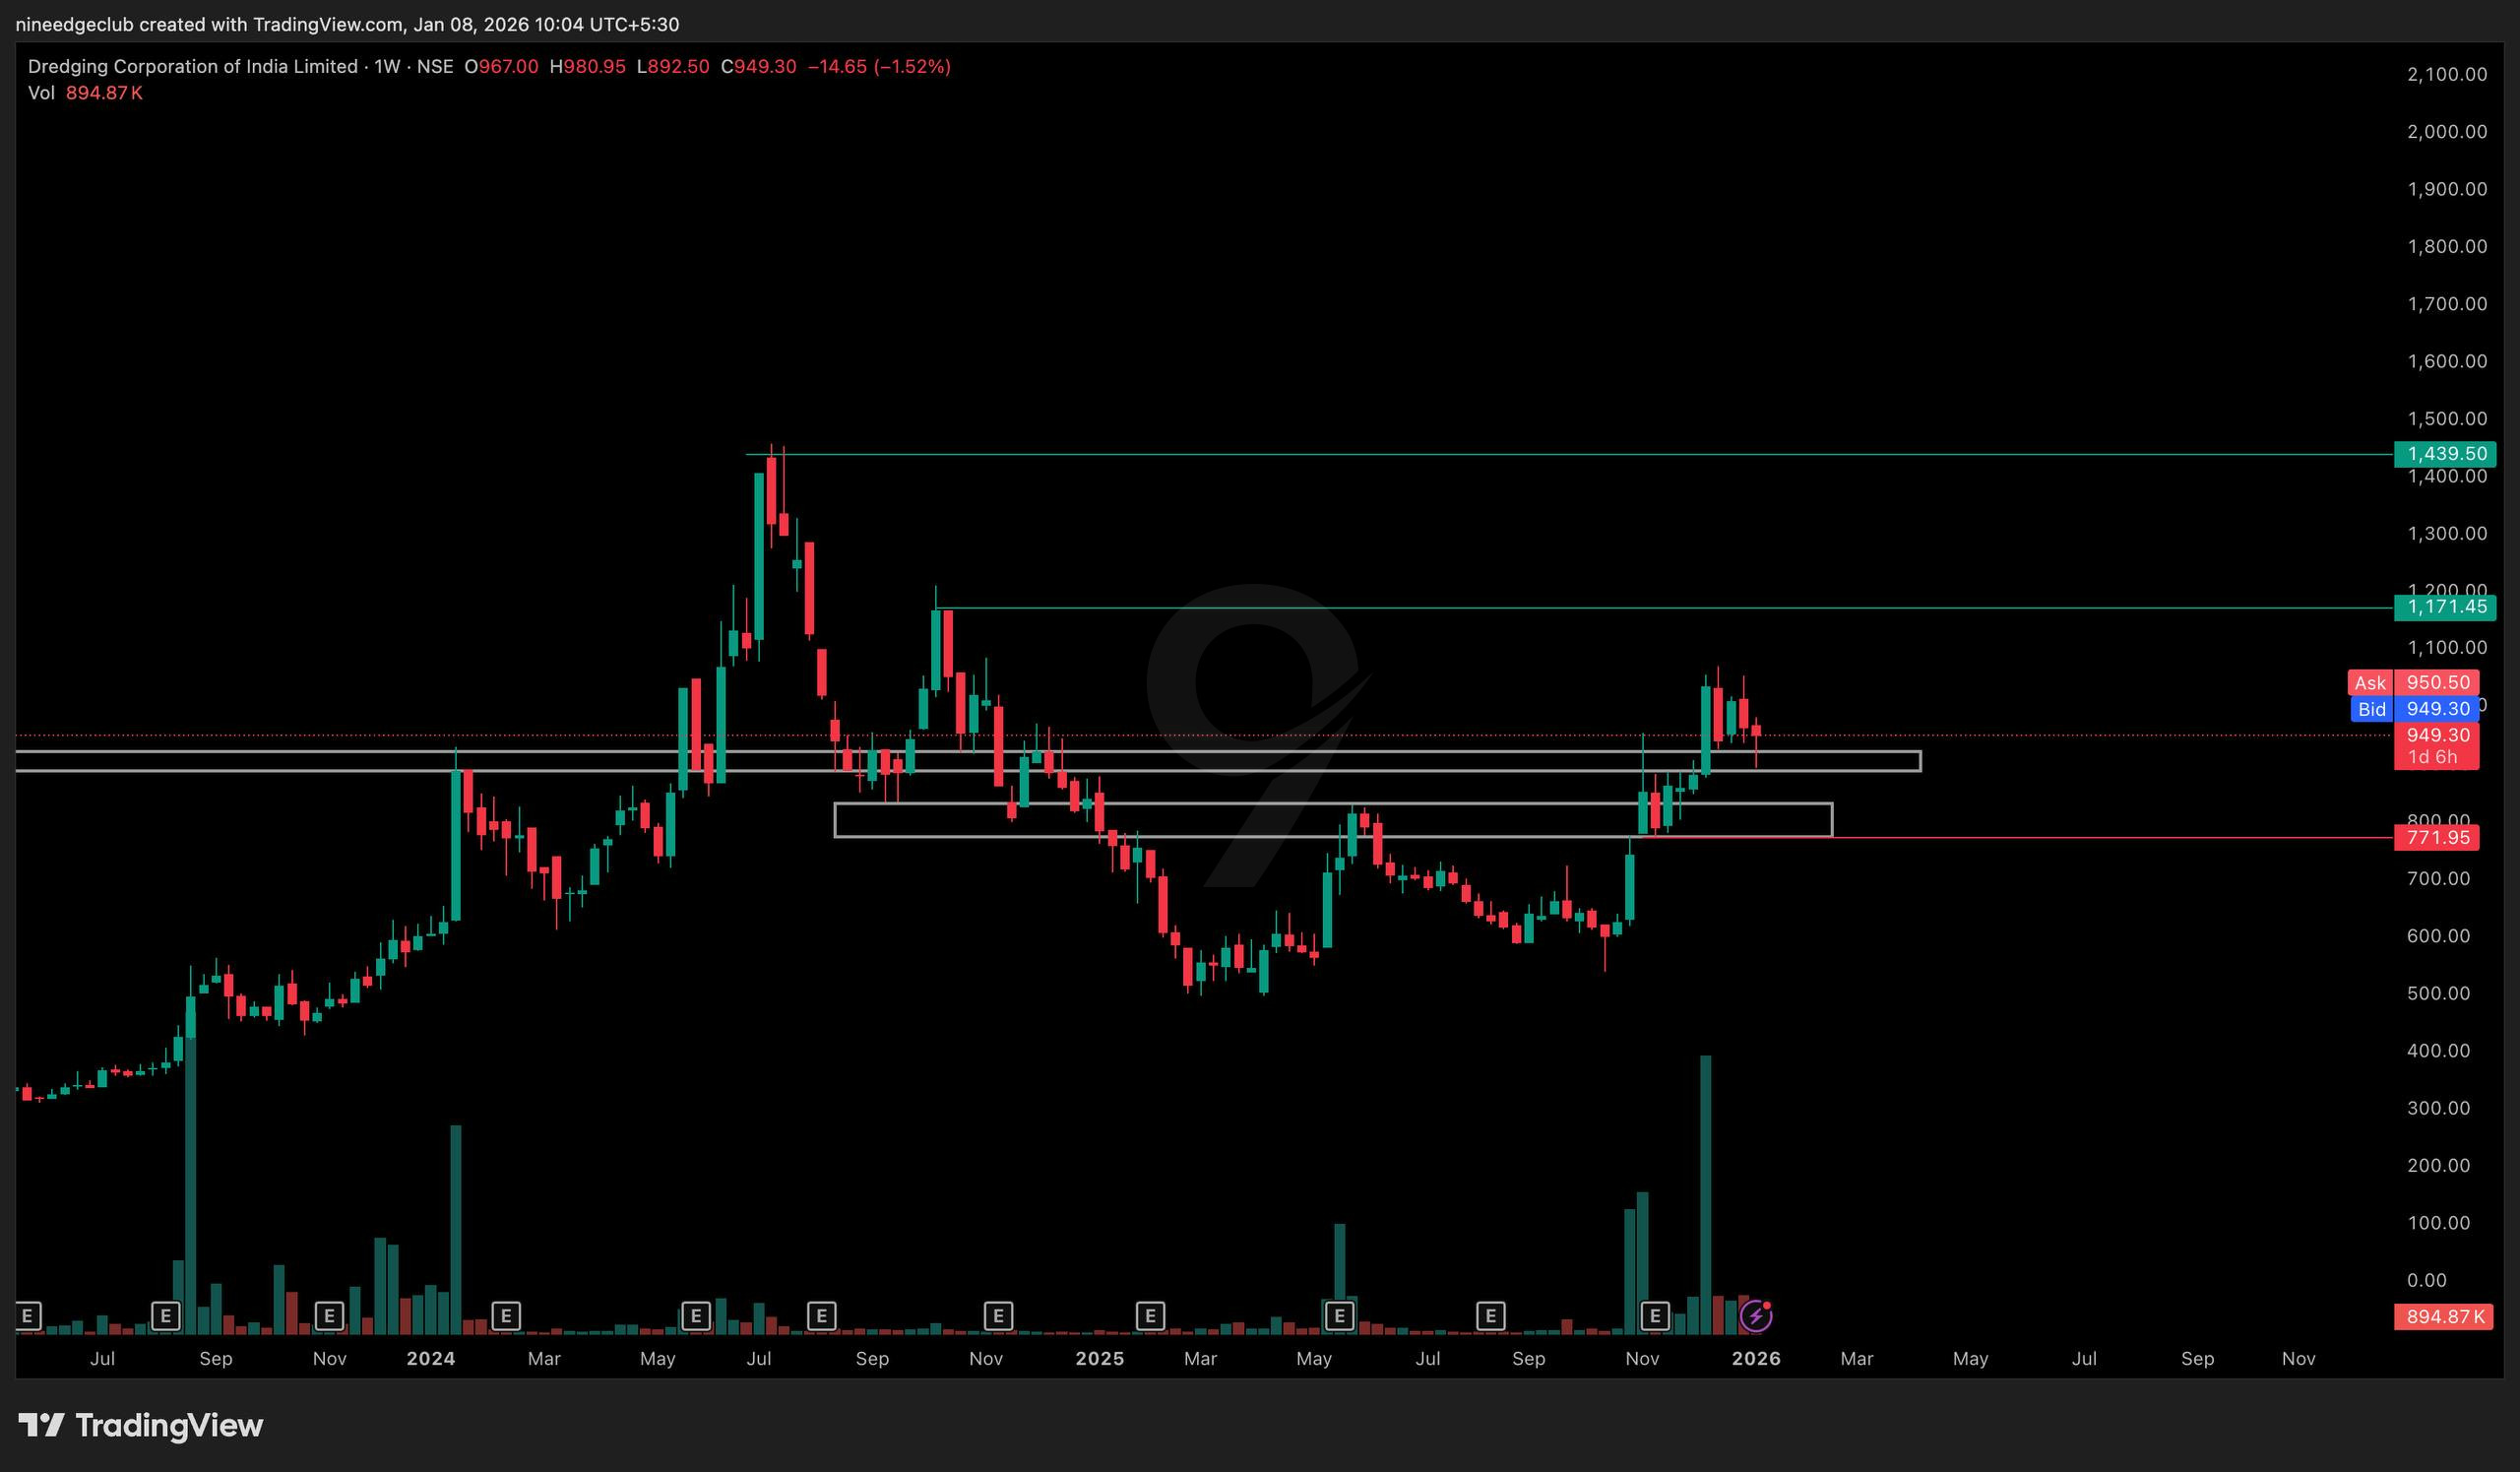
👉 Refer to the chart for my technical levels, support/resistance zones and price action view.
Disclaimer: Educational content only. Not investment advice. Please do your own research.