CONCORD BIOTECH
(NSE: CONCORDBIO)
Business:
R&D driven biopharmaceutical company focused on fermentation based APIs and finished formulationsStrong expertise in immunosuppressants, oncology, anti infectives and antifungalsSupplies products across 70+ countries and 250+ customersThe company has an integrated platform covering KSMs, APIs and formulations.Q1 FY27 Performance 📊
Revenue: ₹257.5 Cr | +26.2% YoYEBITDA: ₹82 Cr | +34% YoYEBITDA Margin: 32%PAT: ₹58.5 Cr | +32.8% YoYAPI revenue: ₹219 Cr | +42% YoYExport revenue grew 46% YoYGross margin improved to 78.9%.Key Positives 🟢
Strong recovery after a challenging FY26API growth is currently the biggest earnings driverHigh gross margins and strong operating profitabilityDebt free balance sheet with more than ₹442 Cr cash and equivalents as of June 2026Limited competitive intensity in key product categoriesNew injectable capacity provides another potential growth engine.Growth Triggers 🚀
Continued growth in fermentation based APIsExpansion of injectable formulationsHigher exports and global customer additionsNew product launches and regulatory approvalsIncreasing utilisation of new manufacturing capacityPotential expansion into additional complex biotechnology productsWhat I’m Watching ⚠️
Q1 was strong, but sustainability across the full year needs confirmationFormulation revenue declined 23% YoY in Q1New injectable facilities need to ramp up efficientlyFY26 had a meaningful revenue decline, so the current recovery needs to continue.Overall View:
Concord Biotech has started FY27 on a strong note, with revenue, EBITDA and PAT all growing at double digit rates.
The most encouraging part is the 42% growth in API revenue and 46% growth in exports, supported by strong margins and a debt free balance sheet.
For me, the key confirmation from here is sustained API growth + injectable ramp up + continued margin strength.
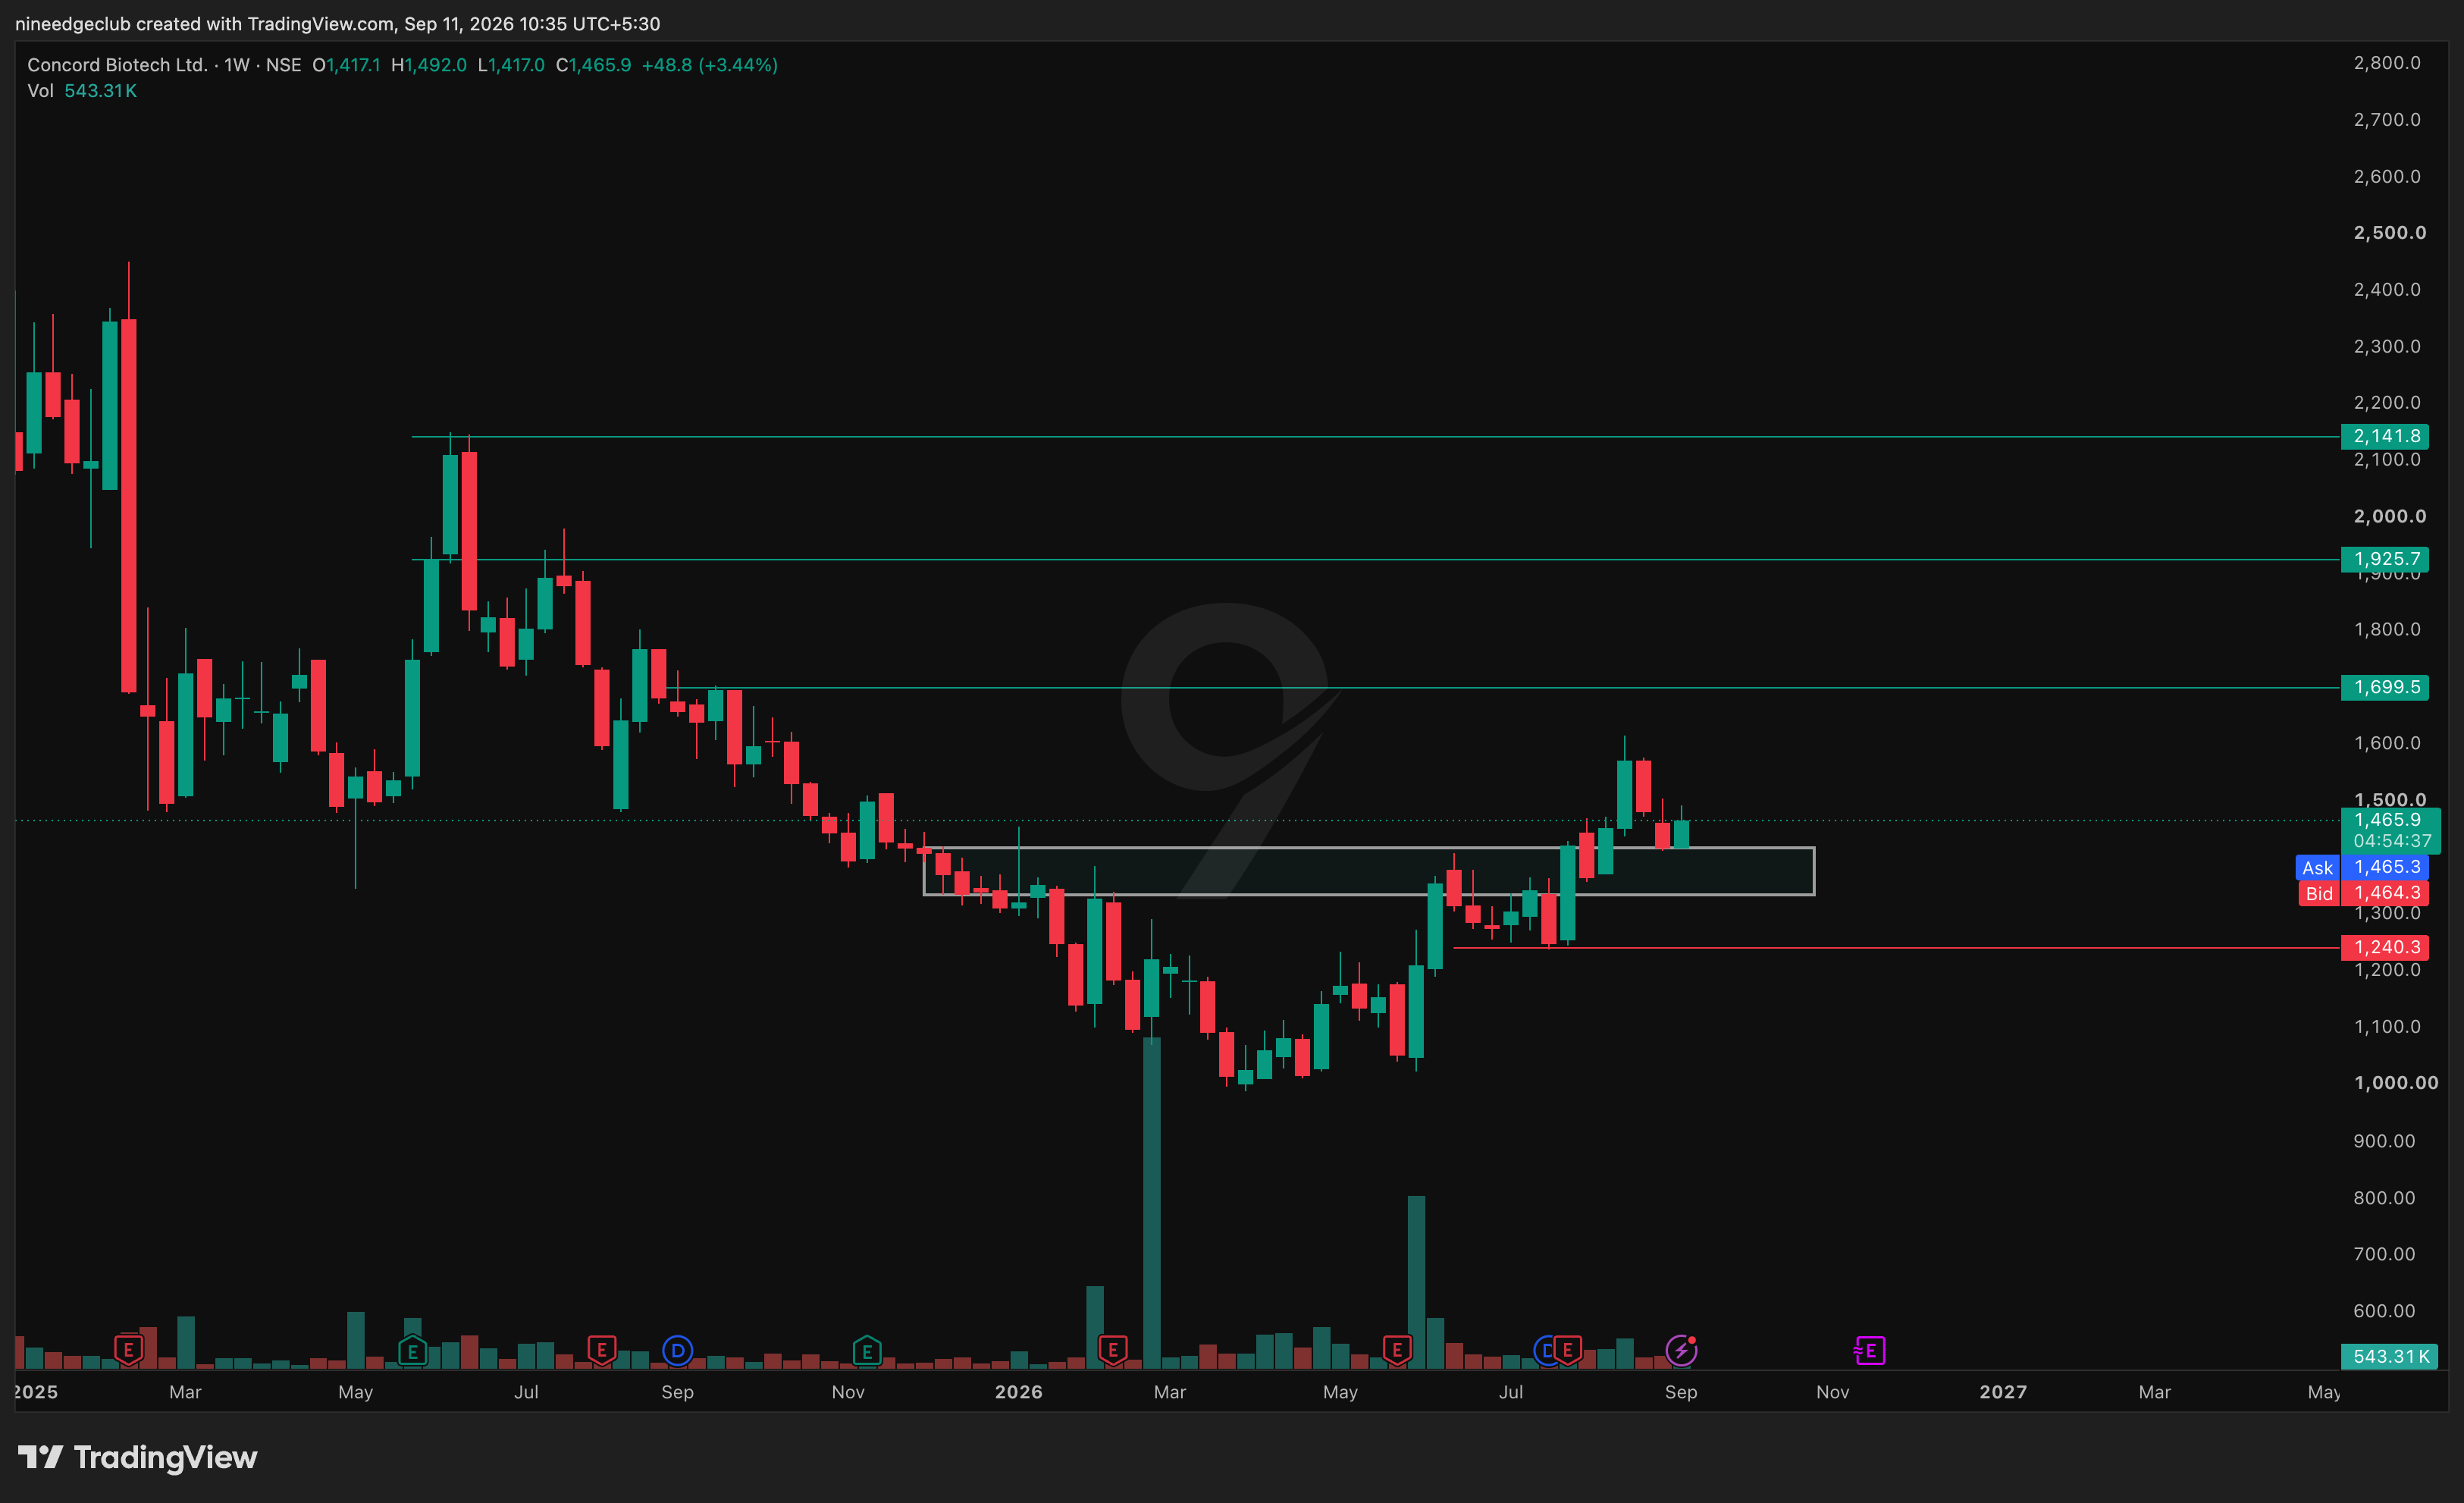
Technical Setup:
👉 Refer to the chart for my technical levels, support/resistance zones and price action view.
Disclaimer: Educational content only. Not investment advice. Please do your own research.