BODAL CHEMICALS LIMITED
( NSE : BODALCHEM )
Business:
Bodal Chemicals is an integrated chemical manufacturer operating across dye intermediates, dyestuffs, basic chemicals and chlor alkali products. Its performance depends on demand from textile and industrial customers, raw material prices, export markets and the company’s ability to protect margins.
Q1 FY27 Performance 📊
Consolidated Revenue: ₹709 Cr, up 56.1% YoYEBITDA: ₹75.1 Cr, up approximately 45% YoYEBITDA Margin: 10.5%, compared with 11.3% in Q1 FY26PAT: ₹30.4 Cr, versus ₹9.5 Cr in Q1 FY26Basic Chemicals: Revenue increased 89% YoY, supported by higher realisations for key products.Chlor Alkali: Revenue grew approximately 3% YoY.Key Positives 🚀
Strong Revenue Growth: Revenue increased sharply, supported by improved business activity and higher realisations.Profit Recovery: PAT more than tripled compared with the year ago quarter.Integrated Operations: Its presence across multiple stages of the chemical value chain provides opportunities to manage sourcing and production costs.Basic Chemicals: Strong growth in this segment supported overall performance.International Business: The Turkish subsidiary, Sener Boya, reported 41% revenue growth, while its Chinese and Indonesian subsidiaries remained comparatively subdued.Growth Triggers 💡
Recovery in global textile and dye intermediate demand.Higher volumes across basic chemicals and other product divisions.Improved capacity utilisation and product mix.Passing higher raw material costs through to customers without sacrificing margins.Recovery in overseas subsidiaries and export markets.Risks / What I’m Watching ⚠️
EBITDA margin declined year on year despite strong revenue growth.Raw materials such as sulphur and other commodity linked inputs can be volatile.Chinese competition and weak global demand can pressure selling prices.Revenue growth needs to translate into stronger operating cash flow and sustainable profits.Performance across overseas subsidiaries remains uneven.📌 Overall View
Bodal Chemicals delivered strong Q1 FY27 revenue growth and a significant recovery in profitability. However, the decline in EBITDA margin shows that higher sales alone are not enough to establish a sustained earnings recovery.
The key monitorables are margin improvement, demand recovery in dyes and intermediates, performance of overseas subsidiaries and cash flow generation in upcoming quarters.
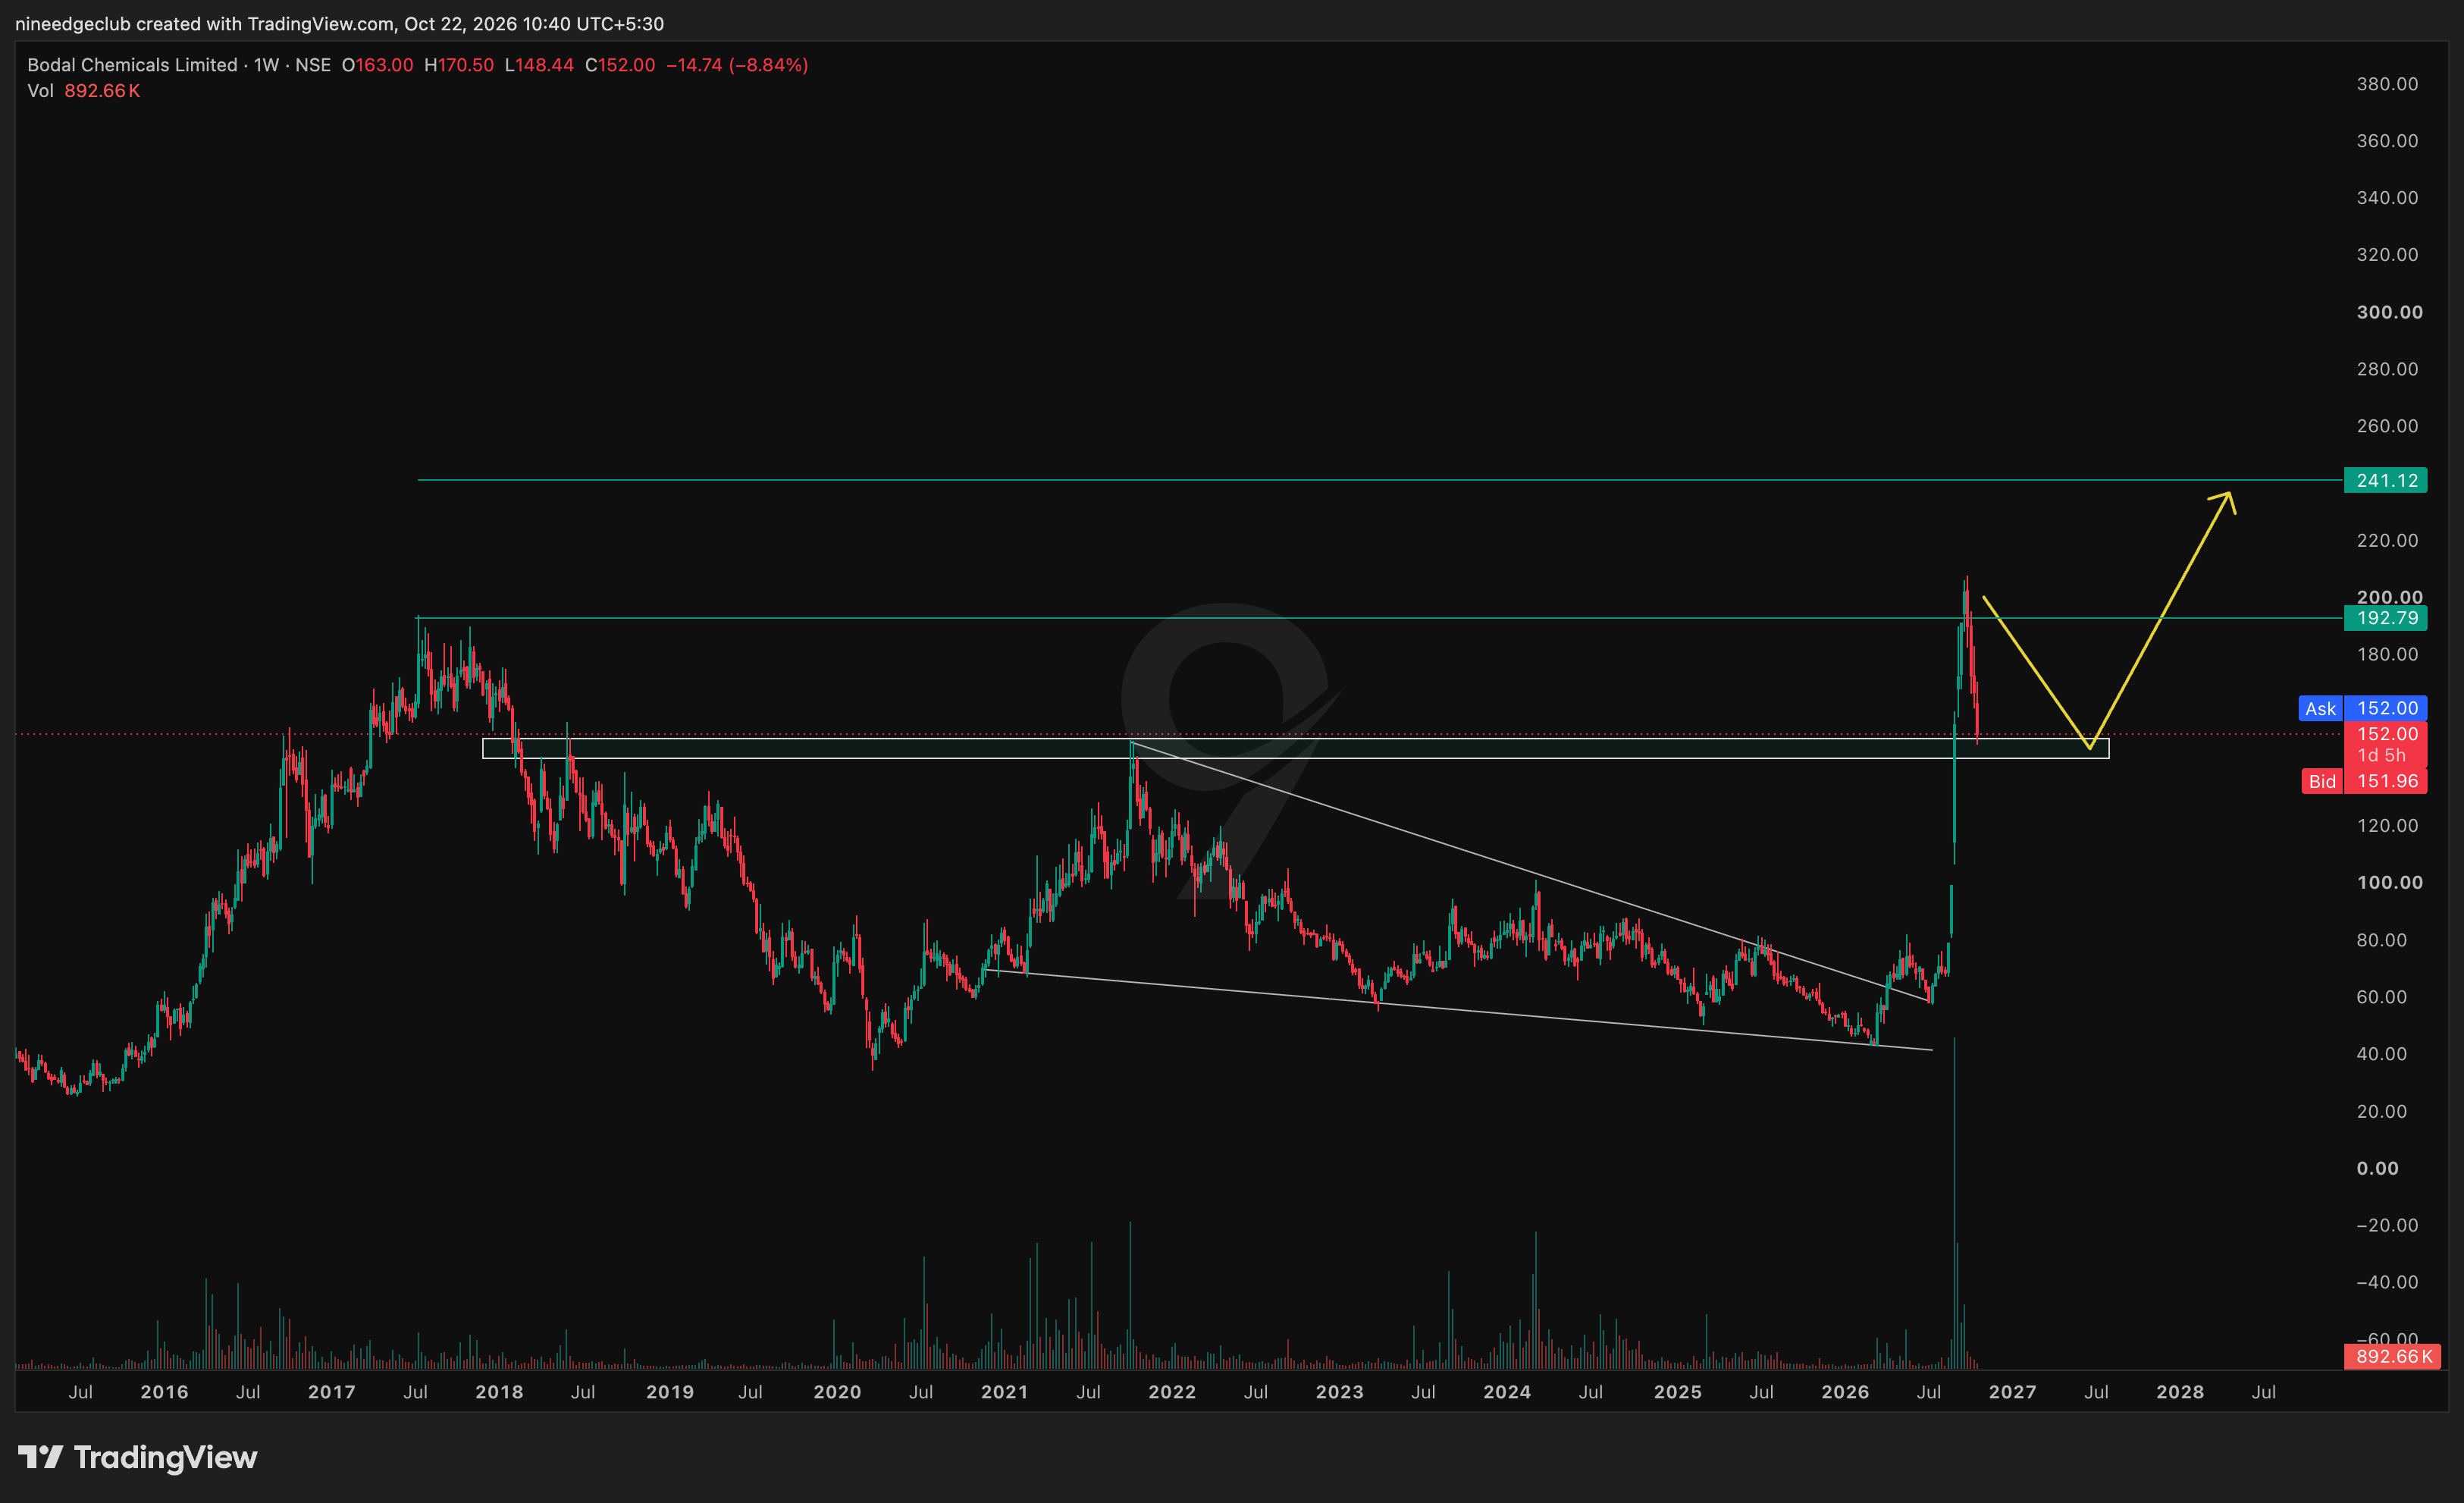
Holding BODALCHEM from ₹77. Took Re-Entry
Technical Setup:
👉 Refer to the chart for my technical levels, support/resistance zones and price action view.
Disclaimer: Educational content only. Not investment advice. Please do your own research.