BF UTILITIES LIMITED
(NSE: BFUTILITIE)
Business:
Part of the Kalyani GroupMain exposure is through Wind Energy and InfrastructureInfrastructure assets include the Nandi infrastructure businessesThe company has undergone restructuring, with its investment business transferred to BF Investment, leaving the infrastructure business with BF Utilities.Q1 FY27 Performance 📊
Standalone revenue from operations: ₹5.88 Cr | +2% YoYThe quarter reported a ₹5.03 Cr net loss compared with a ₹9.29 Cr profit in Q1 FY26Wind Mills remained profitable, while the Infrastructure segment reported a loss of approximately ₹5.81 CrThe quarter was therefore weak from an earnings perspective.The Bigger Story 🚀
The interesting part of BF Utilities is its infrastructure asset base.
Infrastructure segment has substantial assets and capital employedNandi Infrastructure Corridor Enterprise and related entities remain important subsidiariesWind energy provides an operating cash generation componentInfrastructure assets could become more valuable if operations and monetisation improve.Key Positives 🟢
Strong promoter backing through the Kalyani GroupExisting infrastructure asset base provides long term optionalityWind business continues to generate operating profitsPotential improvement in infrastructure performance can have a meaningful impact on earningsFY26 standalone PBT before exceptional items was approximately ₹66 Cr, showing that the business can generate meaningful profitability when infrastructure performance is supportive.What I’m Watching ⚠️
Q1 FY27 earnings were weakInfrastructure segment currently remains the major dragWind generation is seasonal, so individual quarters can be misleadingConsolidated reporting has been delayed because certain subsidiaries had not submitted their financial resultsThe key question is whether infrastructure profitability can recover sustainably.Growth Triggers 🚀
Recovery in infrastructure profitabilityBetter performance from Nandi group assetsHigher wind generationMonetisation or improved utilisation of infrastructure assetsAny restructuring or value unlocking within the groupOverall View:
BF Utilities is more of an asset backed infrastructure and turnaround story than a conventional earnings growth company.
The infrastructure assets provide the optionality, while the wind business provides an existing operating base.
The key confirmation I would watch is a sustained recovery in infrastructure profitability and better consolidated earnings.
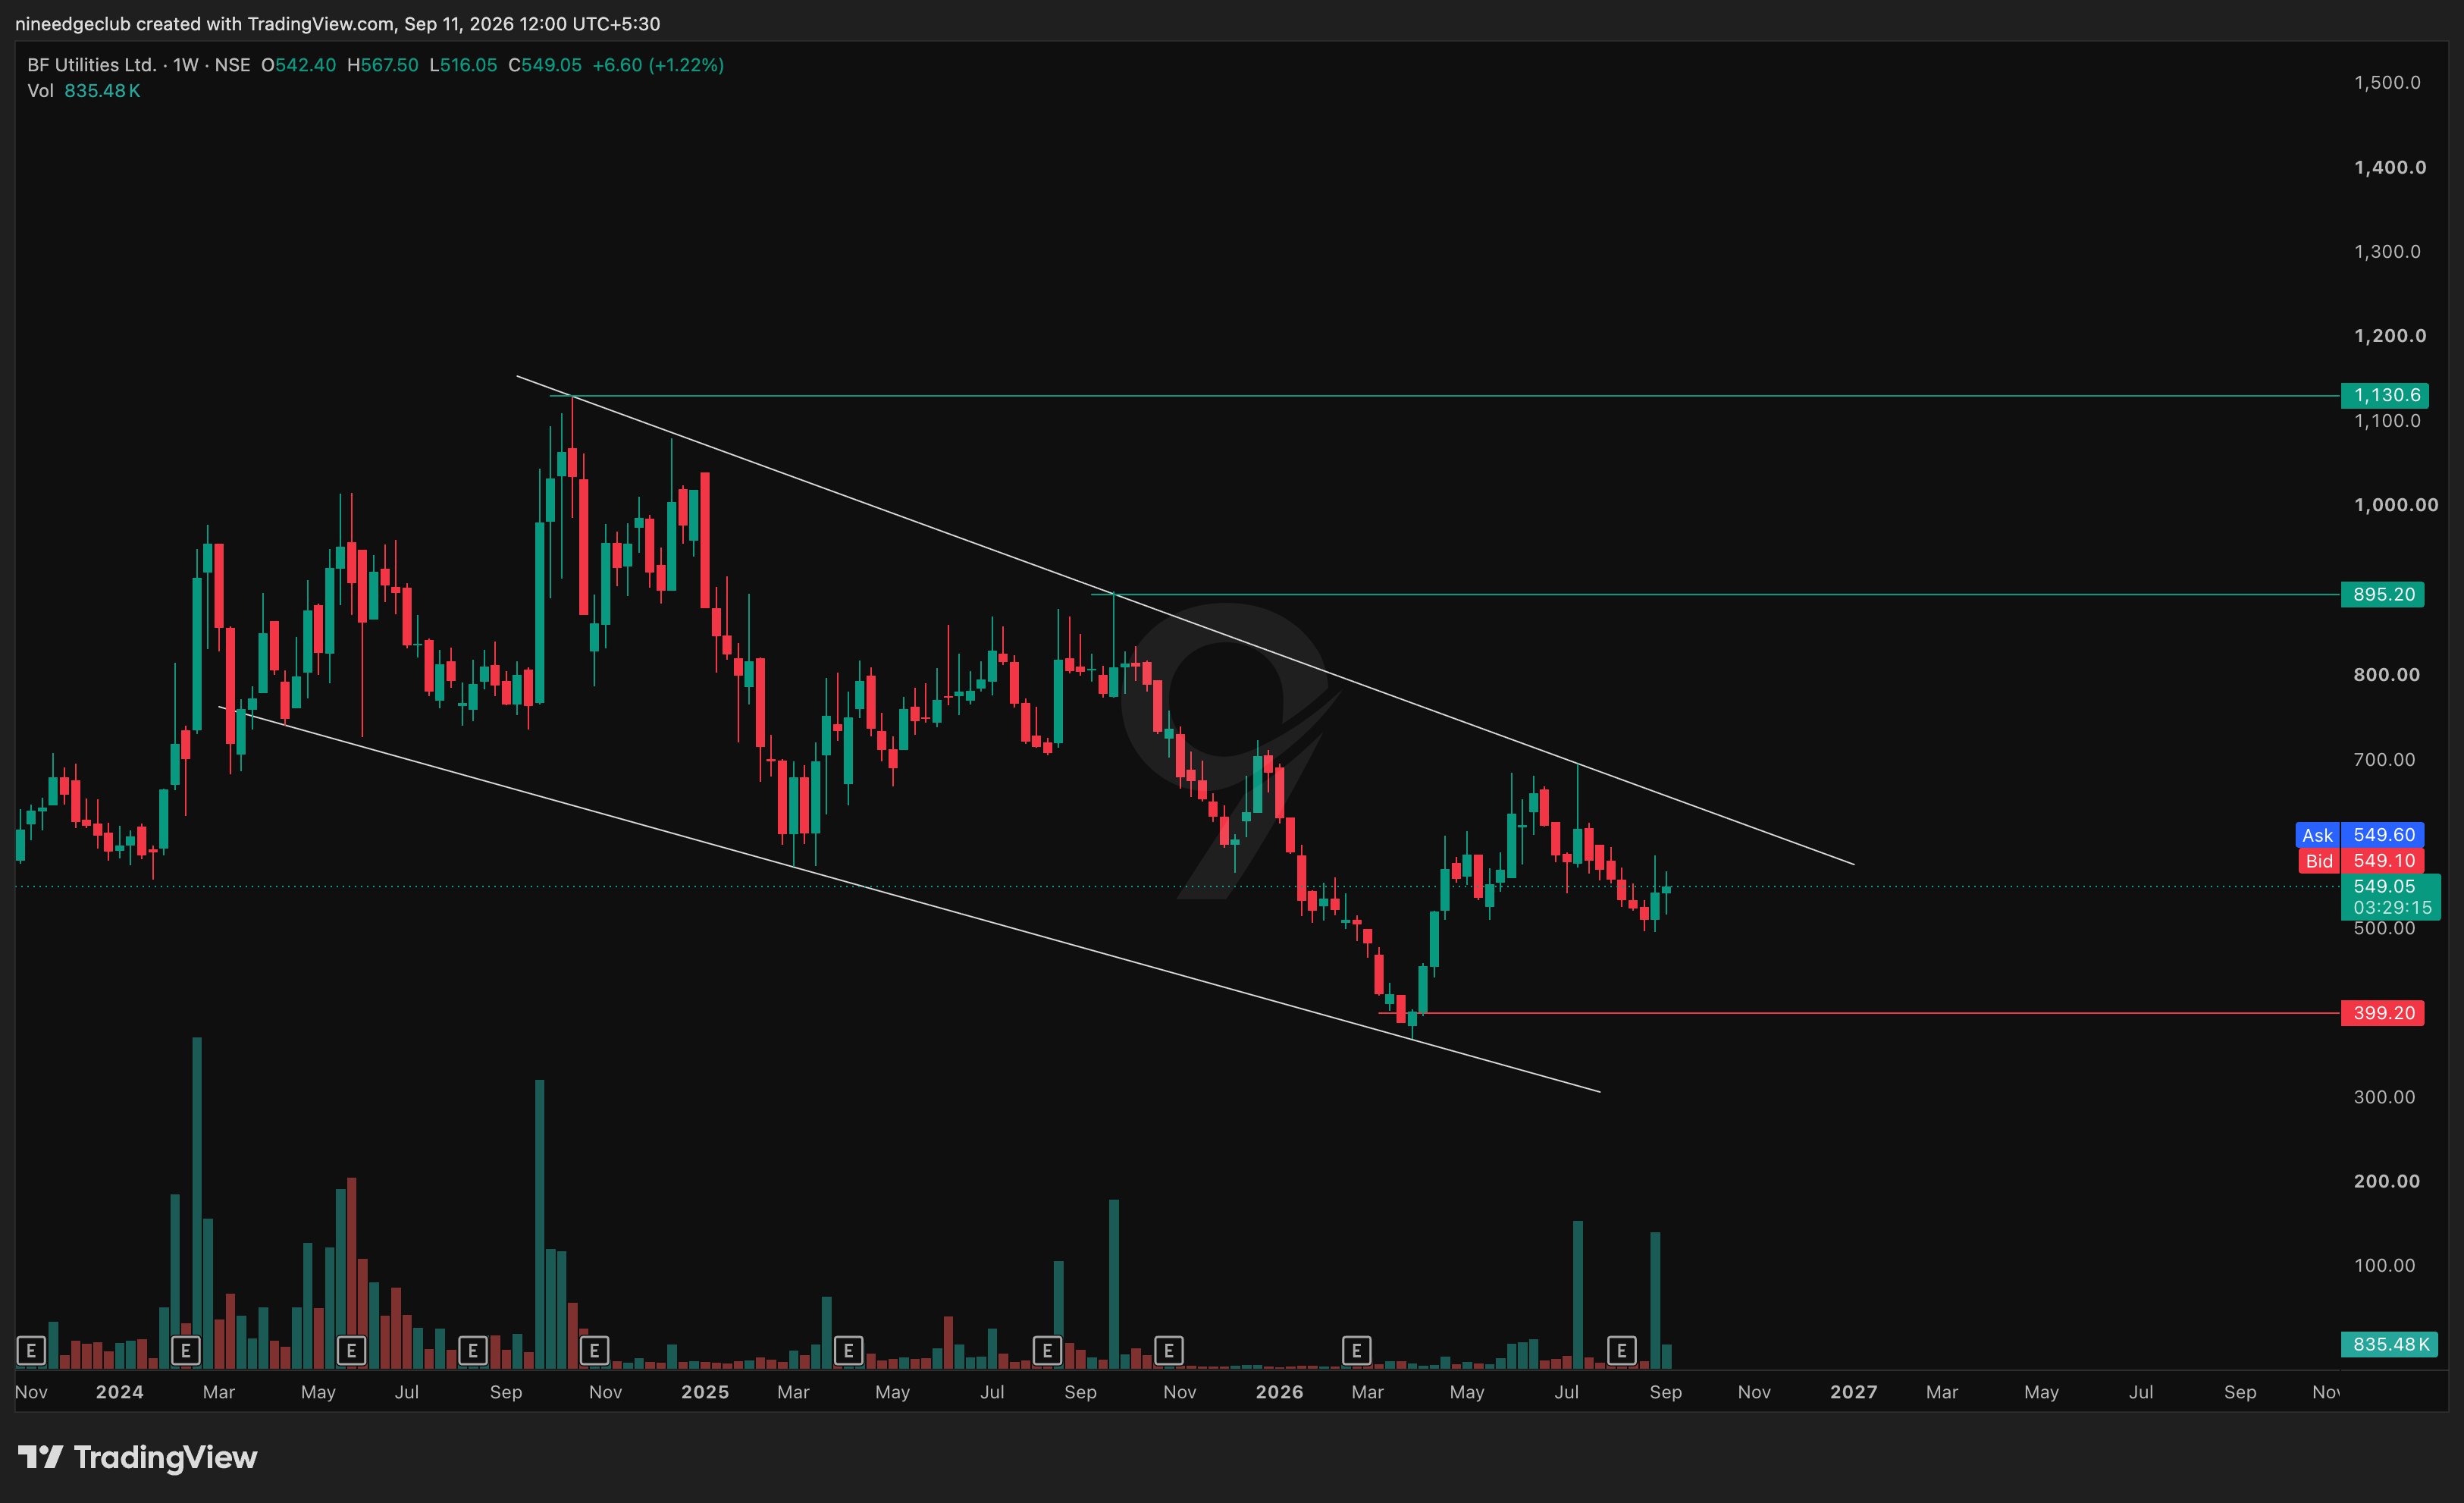
Technical Setup:
👉 Refer to the chart for my technical levels, support/resistance zones and price action view.
Disclaimer: Educational content only. Not investment advice. Please do your own research.