Bharat Earth Movers Limited
(NSE: BEML)
Business:
BEML operates across three major verticals:
Defence & AerospaceRail & MetroMining & ConstructionThe company supplies defence vehicles and systems, metro cars, railway equipment, excavators, dump trucks and other heavy equipment.
Q1 FY27 Performance📊
Revenue from operations ₹820 Cr, up 29.2% YoYTotal income ₹821 Cr, up 27.7% YoYNet loss reduced to ₹27 Cr from ₹64 Cr YoYQ1 order inflow ₹1,181 Cr versus ₹435 Cr YoYOrder book stood at around ₹16,284 Cr as of June 2026The important point is that revenue growth has returned, while the quarterly loss has narrowed substantially.
Order Book 🚀
The ₹16,000 Cr plus order book provides strong revenue visibility.
Rail & Metro currently form the largest part of the order book, while Defence is also becoming increasingly important.
Management has indicated an opportunity pipeline of around ₹35,000 Cr to ₹40,000 Cr, mainly led by Rail and Metro, with Defence and Mining providing additional opportunities.
Growth Triggers🟢
Vande Bharat trainset ordersMetro rolling stock opportunitiesDefence equipment and aerospace ordersMining equipment demandIndigenous high speed rail initiativesGrowing export opportunitiesIncreasing contribution from Defence and Rail & MetroBEML recently received additional orders for Vande Bharat sleeper trainsets and LCH fuselage aerostructures, showing the diversification of its order pipeline.
What I’m Watching⚠️
The biggest monitorable is execution.
BEML has a large order book, but converting that order book into revenue and then into sustainable margins will be critical.
Q1 profitability was still weak despite strong revenue growth, so margin recovery needs to be tracked closely.
Working capital, order finalisation and execution across Rail, Defence and Mining will also remain important.
Overall View:
BEML is increasingly becoming a play on India’s Rail, Metro, Defence and infrastructure capex cycle.
The large order book and expanding opportunity pipeline provide strong visibility, but the next phase of the story depends on execution, margin improvement and conversion of the pipeline into actual orders.
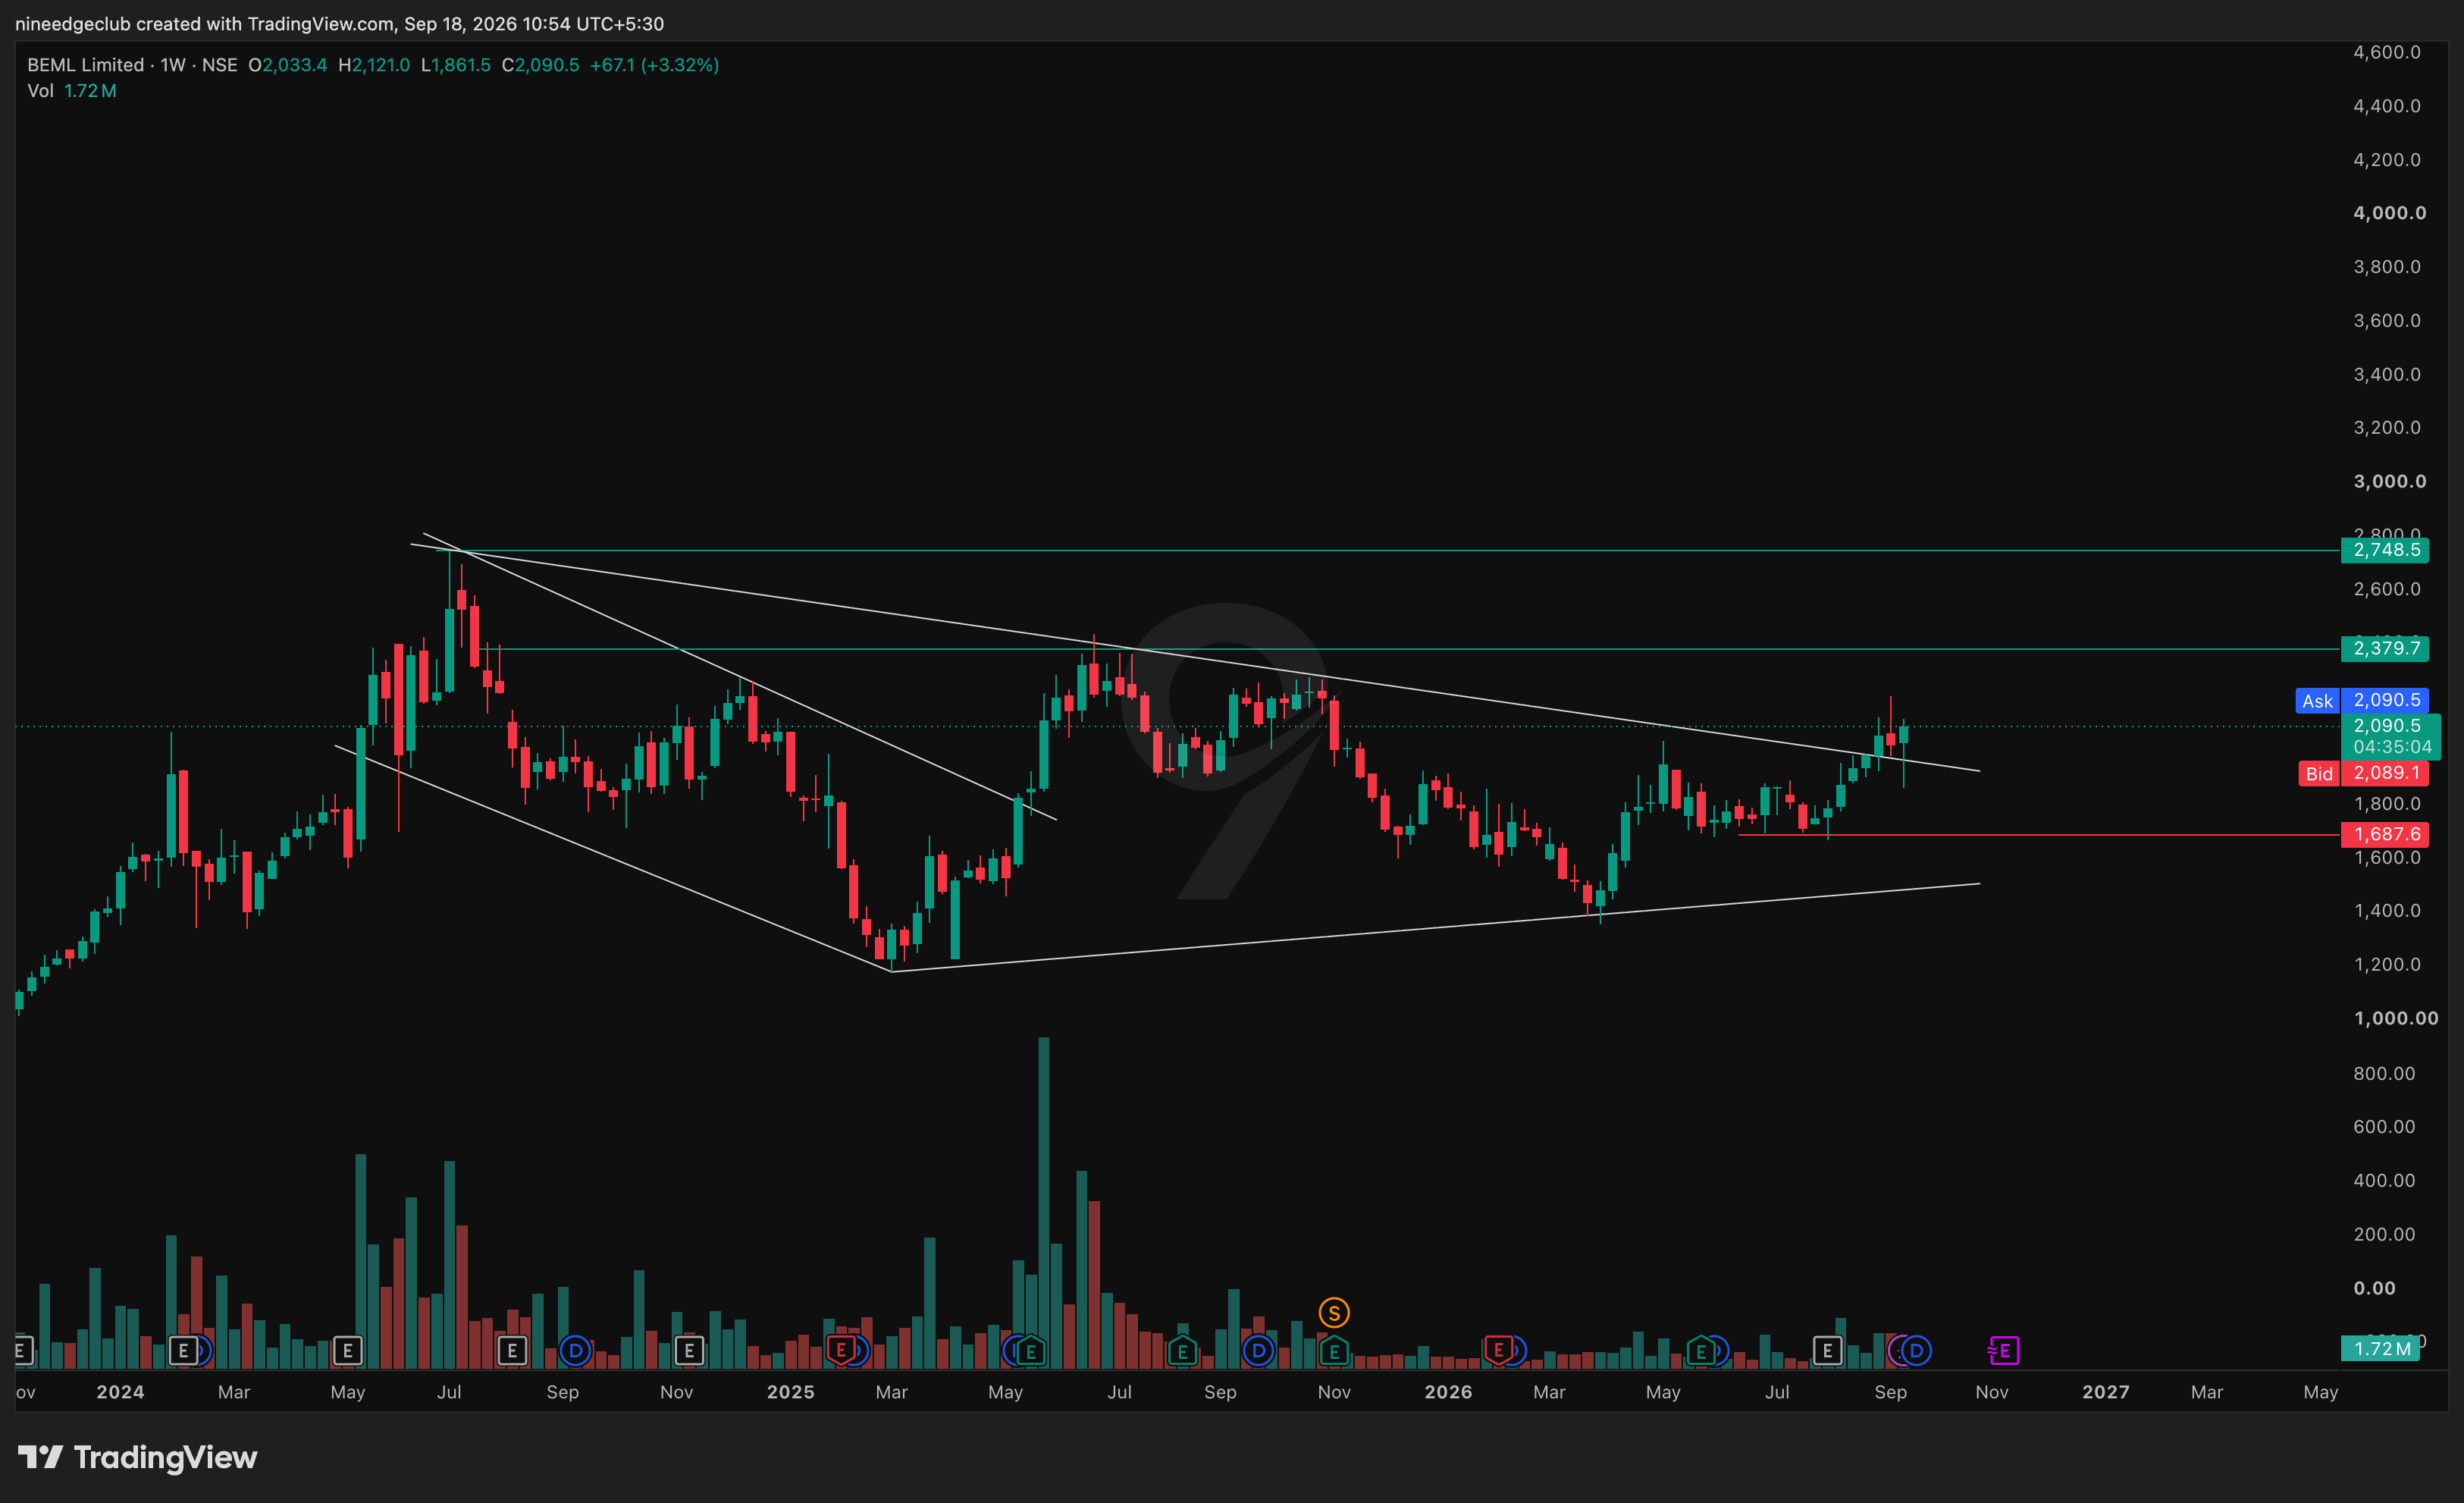
Technical Setup:
👉 Refer to the chart for my technical levels, support/resistance zones and price action view.
Disclaimer: Educational content only. Not investment advice. Please do your own research.