20 MICRONS
(NSE: 20MICRONS)
Business:
20 Microns is a leading Indian manufacturer of industrial minerals, ultrafine minerals and specialty chemicals.Its products find applications across paints & coatings, ceramics, plastics, rubber, construction, textiles, printing inks and agriculture.The company is gradually moving towards higher value specialty minerals & functional additives, which can support margin improvement.Q1 FY27 Performance 📊
Revenue: ₹244.7 Cr | -1.0% YoYEBITDA/Operating Profit: ~₹27 Cr | +1.2% YoYPAT: ₹17.8 Cr | +5.5% YoYEPS: ₹5.04 vs ₹4.78 YoYDespite almost flat revenue, profitability improved, indicating some operating efficiency.Key Positives 🟢
Diversified end-user exposure reduces dependence on a single industry.Established presence in industrial minerals and specialty chemicals.Increasing focus on value added products can improve realisations and margins.International footprint through operations/warehousing in markets including Vietnam, Malaysia, UAE and Turkey.Management has outlined a ₹100 Cr capex plan, which could support the next phase of growth.Company recently acquired 99.99% of Shree Shrest Minerals including a mining lease, strengthening its raw material/resource base.Growth Triggers 🚀
₹100 Cr capex getting commissioned and contributing to revenueHigher contribution from specialty chemicals / functional additivesNew mining resources and backward integrationExport expansionBetter utilisation of existing capacitiesImprovement in revenue growth while maintaining margins.What I’m Watching ⚠️
Q1 revenue growth was weak, with revenue down ~1% YoY and 6.3% QoQ.Profit growth was modest, so stronger top-line acceleration is required.Capex execution and the eventual return on capital will be important.Raw material prices and commodity linked demand can impact margins.After the recent stock appreciation, valuation leaves less room for earnings disappointment.Overall View:
20 Microns has an interesting industrial minerals + specialty chemicals + capacity expansion story.
The current numbers are more of a steady growth setup than an explosive earnings story. The major catalyst from here is whether the planned capex and higher value product mix can translate into stronger revenue growth and sustained margin expansion.
For me, the next few quarters will be important for confirming the growth + capex execution thesis.
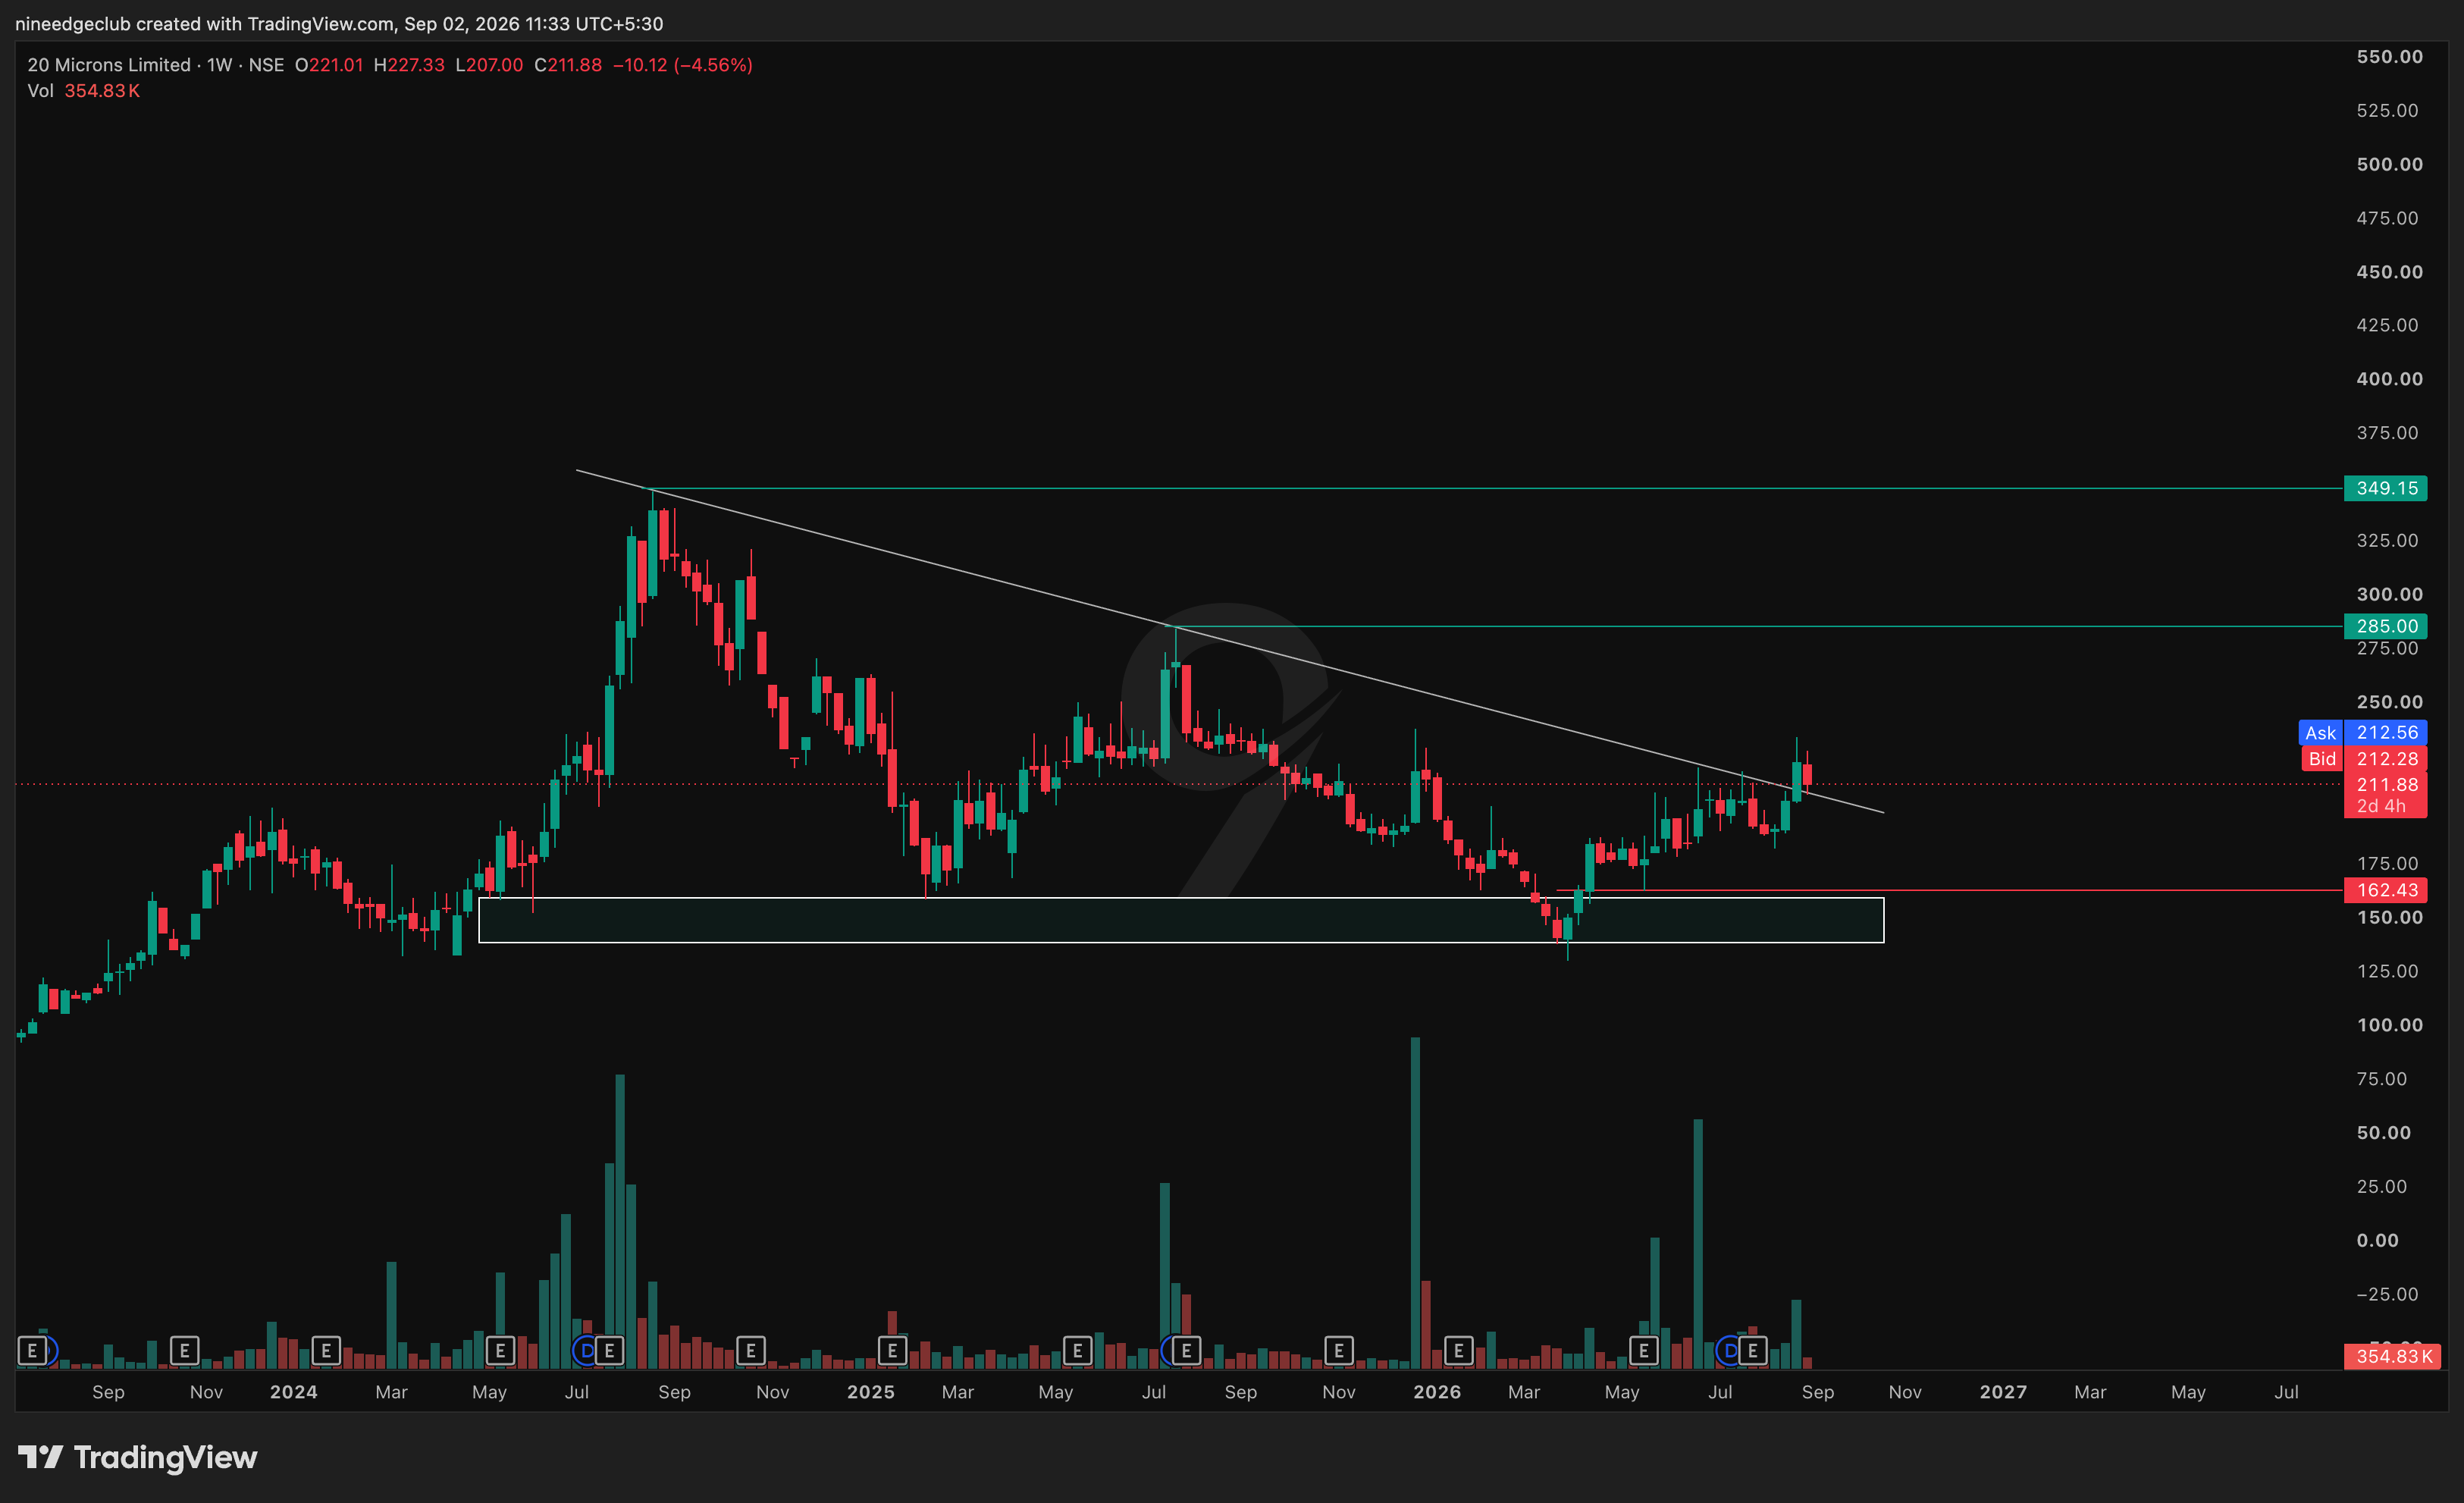
Technical Setup:
👉 Refer to the chart for my technical levels, support/resistance zones and price action view.
Disclaimer: Educational content only. Not investment advice. Please do your own research.